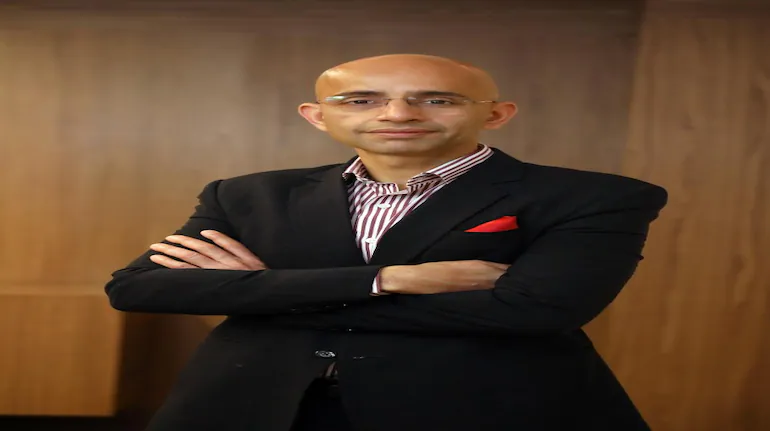
India’s growing alternative investment fund (AIF) industry needs a broader base of long-term domestic capital to sustain its expansion, with insurance companies and pension funds emerging as potential sources of funding for Private Credit and other alternative investment strategies. Aashwin Duggal, the newly appointed CEO of Nippon Alternatives, believes regulatory changes could encourage these institutions to increase their participation in the asset class.
Duggal has called for higher investment limits for life and general insurers and a carefully structured framework allowing pension funds such as the Employees’ Provident Fund Organisation (EPFO) to invest in Category II AIFs. Greater institutional participation, he said, could strengthen India’s domestic capital base and provide patient funding for private credit, private equity and related strategies.
His comments come as India’s AIF industry expands rapidly but remains heavily dependent on wealthy individuals and family offices. Bringing more institutional investors into the market could help diversify its funding sources and support the next phase of growth.
India’s AIF Industry Sees Strong Growth
India’s alternative investment industry has expanded significantly in recent years, particularly across Category I and Category II funds. According to Securities and Exchange Board of India (SEBI) data, total AIF commitments reached Rs 17.53 lakh crore as of June 2026, representing an increase of nearly 24% year-on-year.
Cumulative investments by AIFs also crossed Rs 7 lakh crore for the first time, highlighting the growing role of alternative funds in the country’s investment landscape.
Category II AIFs accounted for Rs 13.03 lakh crore in commitments as of June 2026. These funds include private equity, private debt, real estate and related investment strategies.
Despite this expansion, the industry continues to rely substantially on wealthy individuals and family offices. Duggal believes that attracting insurance companies and pension funds could create a more diversified domestic investor base and provide the long-term capital required by these funds.
The scale of the opportunity is also reflected in the number of registered funds. SEBI’s annual report recorded 1,829 registered AIFs as of March 2026, including 1,019 Category II funds.
Duggal Calls for Higher Insurance Investment Limits
One of Duggal’s key proposals is to reconsider the regulatory investment limits available to life and general insurance companies. He said the current limits stand at 3% for life insurers and 5% for general insurers, and argued that additional flexibility could encourage larger allocations to alternative investments.
In an interaction with Moneycontrol, Duggal said higher investment limits could allow insurance companies to gradually increase their exposure to alternatives and diversify their portfolios.
He also pointed to international markets, where insurance companies allocate a considerably higher proportion of their assets under management to alternative investments. According to Duggal, allocations of around 20% are seen in some markets.
He said: “One of the asks would be to consider increasing the regulatory investment limits for both life and general insurance companies, which are currently at 3 percent and 5 percent, respectively. Greater headroom could encourage larger domestic allocations over time.”
However, any increase in investment limits would need to be evaluated alongside insurers’ obligations to policyholders, portfolio risks and the liquidity requirements associated with their businesses.
Regulatory Changes Have Already Expanded Insurer Options
The regulatory framework for insurance investments has also been evolving. Earlier in 2026, the Insurance Regulatory and Development Authority of India widened the investment options available to insurers.
The changes included permission for insurers to invest in equity and debt instruments issued by private limited companies. The regulator also eased certain norms relating to infrastructure financing through special purpose vehicles.
Under the revised framework described in the report, life insurers can invest up to 3% of life or segregated funds, while general insurers can allocate up to 5% of their investment assets to private limited companies, AIFs and venture funds combined.
Duggal believes that additional regulatory headroom could encourage insurers to build larger and more diversified allocations over time. Private credit is particularly relevant because its longer-duration assets may align with the liability profiles of insurance companies.
Insurance companies manage funds against obligations that can extend over many years. Longer-term investments may therefore fit certain parts of their portfolios, provided the risks, liquidity requirements and expected returns are assessed carefully.
Insurers Increasingly Explore Private Credit
Interest from insurance companies in private credit has already started increasing. Industry reports indicate that insurers have nearly doubled their commitments to private credit funds over the past two years.
Some insurance companies are using AIF structures to diversify their investment portfolios and seek improved returns for policyholders. Private credit can provide exposure to lending opportunities outside traditional public debt markets, including financing for businesses that may not rely entirely on bank borrowing.
Duggal said private credit was attracting growing interest from domestic institutional investors, including insurers and family offices. He highlighted both performing credit and high-yield credit strategies as areas receiving attention.
The increasing interest reflects investors’ search for additional sources of yield and diversification beyond listed equities and conventional fixed-income instruments. However, private credit investments also involve risks related to borrower quality, repayment capacity, valuation and the ability to exit investments.
Duggal Supports Gradual EPFO Entry into Category II AIFs
Beyond insurance companies, Duggal believes pension funds could become an important source of long-term capital for India’s alternative investment industry. He has backed a gradual and safeguards-led approach to allowing institutions such as the EPFO to participate in Category II AIFs.
He said even a small initial allocation could help pension funds become familiar with the asset class and create a pathway for larger long-term investments in the future.
“There is a case for evaluating a calibrated framework for pension funds such as EPFO to participate in Category II AIFs. Even a small initial allocation could help build familiarity with the asset class and create a pathway for long-term capital over time,” Duggal said.
The EPFO is already considering a proposal to allocate up to 3% of fresh annual accretions to Category I and Category II AIFs. The proposal is expected to be placed before its Central Board of Trustees in November.
However, the retirement fund has not yet invested in SEBI-regulated Category I or Category II AIFs. Any investment decision would require approval from the trustees and detailed investment guidelines.
EPFO Proposal Could Bring Significant Institutional Capital
The potential participation of EPFO could be significant for India’s AIF industry because of the scale of the retirement fund’s savings. The organisation manages approximately Rs 30 lakh crore in savings for nearly 30 crore members.
Even a relatively small allocation from such a large pool of funds could provide a meaningful source of capital for eligible alternative investment funds. It could also encourage other long-term institutions to evaluate the asset class.
Initial investments may be routed through institutional platforms such as the National Investment and Infrastructure Fund and SIDBI’s Startup India Fund of Funds 2.0.
The proposed framework reportedly includes several safeguards intended to limit risks. These include a minimum AIF corpus of Rs 100 crore, restrictions on exposure to individual funds, limits relating to overseas-incorporated entities and requirements concerning the independence of fund managers.
These conditions would be important because pension savings serve a long-term retirement purpose. Any exposure to relatively illiquid alternative investments would need to be supported by strong governance, investment oversight and risk management.
Private Credit Demand Expands Among Institutional Investors
Private credit is emerging as one of the more active areas of interest within India’s alternative investment market. Duggal said domestic institutional investors, particularly insurers and family offices, were showing increasing interest in performing credit and high-yield strategies.
Private credit funds generally provide financing outside conventional public debt markets. They can offer companies another source of borrowing while giving investors access to credit opportunities that may not be available through listed bonds or traditional fixed-income products.
For investors, the attraction can include portfolio diversification and the potential for higher returns. However, these opportunities come with additional considerations, including borrower defaults, limited liquidity and the difficulty of assessing the value of privately held debt instruments.
The expansion of India’s AIF sector provides a broader platform for such strategies. Category II funds, which include private debt and private equity, account for a substantial share of total AIF commitments.
Category II Funds Need Patient Capital
Despite growing investor interest, Duggal cautioned that Category II AIFs are not suitable for investors seeking short-term access to their money. These strategies are inherently illiquid and often involve investment horizons extending over several years.
“Category II investments are inherently illiquid and often have multi-year horizons. That is why they require long-term, patient capital,” he said.
This is central to the argument for greater participation from insurers and pension funds. Such institutions may be able to hold investments across market cycles because their financial obligations often extend over long periods.
However, their ability to invest in private equity, private debt and real assets depends on appropriate governance, reliable valuation practices and careful management of liquidity and concentration risks.
For pension funds in particular, protecting retirement savings must remain a central consideration. A gradual investment approach with clear exposure limits and independent oversight could help institutions evaluate the asset class without taking on excessive risk.
What Duggal’s Appointment Means for Nippon Alternatives
Duggal brings more than 27 years of experience across asset management, banking and financial services to his new role as CEO of Nippon Alternatives. He previously served as Deputy Head of Alternatives at Nippon India and Co-Chief Business Officer.
He joined Nippon in 2007 and has also worked with Tata Asset Management, Kotak Mahindra Bank and ING Investment Management. The alternatives business was previously led by Ashish Chhugani as Head of Alternative Investments.
His comments on institutional capital come at a time when India’s alternative investment industry is looking to broaden its investor base. Greater participation from insurers and pension funds could provide more stable sources of funding, particularly for strategies that require capital to remain invested over several years.
Institutional Capital Could Shape the Next Phase of India’s AIF Market
India’s AIF industry has grown rapidly, but its continued expansion will depend partly on whether it can attract a wider range of domestic investors. Insurance companies and pension funds represent a potentially important source of long-term capital, although their participation will depend on regulatory permissions and appropriate safeguards.
Higher investment limits for insurers could encourage greater exposure to private credit, while a carefully designed EPFO framework could introduce pension savings to Category II AIFs. Both developments would require strong governance and clear rules to manage the risks associated with illiquid investments.
For fund managers, institutional participation could improve access to patient capital and support the financing of businesses and assets across the economy. For investors, it could broaden the range of investment opportunities available through professionally managed funds.
Duggal’s broader objective is to deepen India’s domestic capital base and provide long-term institutions with more diversified investment options. Whether that vision translates into larger allocations will depend on regulatory decisions, institutional risk assessments and the ability of private credit funds to demonstrate disciplined investment management.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0