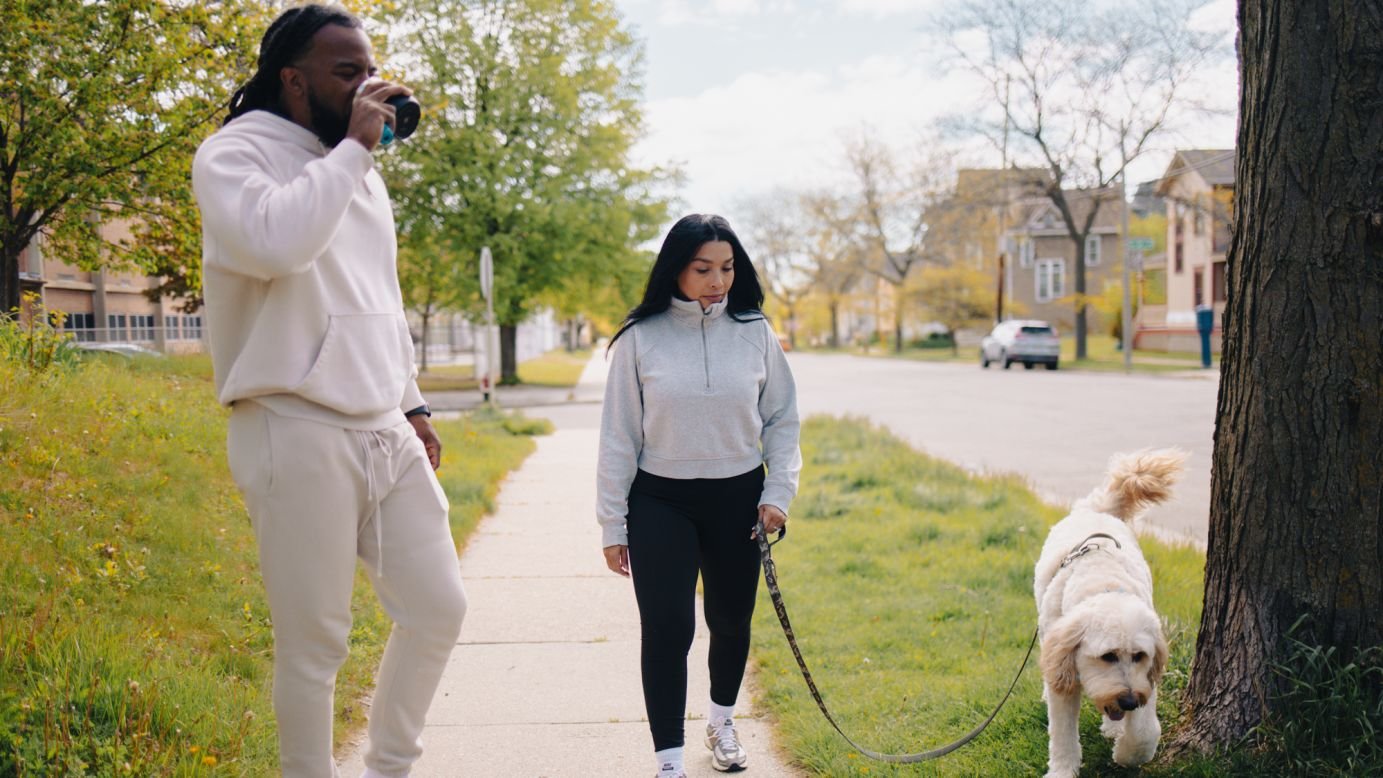
A modest inheritance helped Milwaukee couple Mariza and Geffrey Gordon clear their credit card debt and improve their credit scores by more than 100 points to approximately 750. However, becoming debt-free has not completely resolved their financial challenges. The couple is still living paycheck to paycheck and has limited Savings to manage unexpected expenses.
Through their participation in a Savings Challenge with financial educator Tiffany Aliche, the couple has started examining their spending habits and making changes to improve their financial stability. Their experience has highlighted the importance of distinguishing essential expenses from discretionary purchases, maintaining savings and avoiding unnecessary debt.
Although their financial progress has been affected by Mariza’s job loss, the couple is working towards building better money habits and preparing for future emergencies.
Key Highlights
- A modest inheritance helped Mariza and Geffrey Gordon clear their credit card debt.
- Their credit scores increased by more than 100 points to approximately 750.
- The couple has started separating essential expenses from non-essential spending.
- Mariza’s unemployment has made it difficult to maintain their savings.
- Their long-term goal is to build an emergency fund covering six months of expenses.
Inheritance Helps Couple Clear Credit Card Debt
The inheritance received by Mariza and Geffrey Gordon provided an opportunity to eliminate their outstanding credit card balances. Clearing the debt also helped improve their credit scores by more than 100 points, bringing them to approximately 750.
While the improvement in their credit profiles was an important achievement, it did not automatically solve their broader financial problems. The couple continued to face the challenge of managing monthly expenses without having sufficient savings to deal with emergencies.
The experience showed them that becoming debt-free is only one part of financial stability. Developing consistent spending habits and building a financial cushion are equally important for long-term security.
Separating Wants and Needs to Control Spending
One of the biggest lessons from the Savings Challenge was the importance of honestly examining their financial habits. Geffrey said that facing their spending patterns, including both good and bad decisions, was among the most difficult but valuable parts of the process.
The couple has started asking whether a purchase is necessary or simply something they would like to have. This approach has encouraged them to reduce spending on clothes, travel, concerts and sporting events.
They have also reconsidered some household purchases. For example, although they bought a garbage disposal to replace their broken unit, they decided against installing it because of the additional cost. They realised they could manage without it for the time being.
These decisions reflect a shift towards prioritising essential expenses rather than making purchases simply because they are desirable or convenient.
Why the Couple Still Made Some Major Home Purchases
Despite cutting back on discretionary spending, the Gordons proceeded with two significant household expenses. They installed new carpeting because the old carpet continued to smell unpleasant even after cleaning.
They also purchased furniture for their bedroom, which previously contained little beyond the bed. Mariza explained that the purchase was intended to make the room more functional and comfortable.
The couple paid $400 in cash towards the furniture and financed the remaining amount through a store credit card offering a 0% interest rate. Their improved credit scores helped them qualify for the financing arrangement.
Mariza said they were making monthly payments and expected to clear the balance before the promotional interest-free period ended.
However, financial educator Tiffany Aliche advised against taking on additional debt unless it was necessary to protect their health or safety. Her guidance highlighted the importance of avoiding new financial commitments while the household was still working towards greater stability.
Maintaining Savings Becomes the Immediate Priority
The couple’s savings strategy has also changed because of Mariza’s employment situation. She was laid off earlier in the year from her position as a plan consultant at a financial services firm and had not secured a new full-time role at the time of the report.
Given the loss of one household income, Aliche advised the couple to focus on maintaining their existing savings rather than aggressively increasing them. Preserving available funds can be particularly important when employment and monthly income are uncertain.
However, the couple has been using part of their remaining inheritance and the savings automatically transferred from Geffrey’s paycheck to cover regular expenses. These include Mariza’s monthly car payment of $555 and other household costs.
Geffrey said he was glad he had arranged an automatic deposit of 20% of his paycheck into savings. He expects this arrangement to become more useful once Mariza finds another job and the household returns to having two incomes.
Six-Month Emergency Fund Is the Long-Term Goal
One of the couple’s major financial objectives is to build an emergency fund capable of covering six months of expenses. Such a fund could provide protection if either partner loses their job or the household faces an unexpected financial challenge.
For now, maintaining existing savings remains more important than setting aside larger amounts while Mariza is unemployed. Once both partners are earning again, they plan to prioritise emergency savings in line with Aliche’s advice.
An emergency fund can help households avoid relying on credit cards or loans when unexpected expenses arise. It can also provide greater financial flexibility during periods of unemployment or reduced income.
Job Search and Health Insurance Remain Challenges
Mariza’s employment situation continues to be an important factor in the family’s financial planning. At the time of the report, she had been attending job interviews and had also completed freelance work curating an art exhibition featuring local artists.
Health insurance is another concern. Mariza said she was currently managing without coverage and planned to join her husband’s health insurance plan in 2027 if she had not found a job by then.
Until their household income improves, the couple is also looking for ways to reduce everyday expenses. They plan to continue purchasing groceries and other goods in bulk from Costco and prepare more meals at home to manage food costs.
Keeping Perspective During Financial Uncertainty
The Savings Challenge has coincided with a difficult period for the couple, particularly because of Mariza’s layoff. However, the experience has also encouraged her to become more mindful of the positive aspects of her life and avoid taking financial and personal stability for granted.
Mariza said the process helped her maintain perspective even when she felt discouraged about her job search. Her experience highlights how financial planning involves not only managing numbers but also developing realistic expectations and making thoughtful decisions during uncertain periods.
Lessons From the Milwaukee Couple’s Financial Journey
The Gordons’ experience offers several practical lessons for households trying to improve their financial situation:
- Track spending habits: Understanding where money goes is an important first step towards controlling expenses.
- Separate wants from needs: Prioritising essential purchases can help reduce unnecessary spending.
- Avoid unnecessary debt: New borrowing can create additional pressure, even when promotional interest rates are available.
- Protect existing savings: Maintaining an emergency reserve is particularly important during unemployment.
- Automate savings: Regular transfers from income can make saving more consistent when finances improve.
- Plan for emergencies: Building a fund that covers six months of expenses can provide a financial safety net.
Conclusion
Mariza and Geffrey Gordon’s financial journey demonstrates that clearing credit card debt and improving credit scores are important milestones, but they do not guarantee long-term financial security. Their experience has shown the importance of changing spending habits, avoiding unnecessary borrowing and protecting savings during periods of uncertainty.
With Mariza continuing her job search and the couple working to control household expenses, their immediate priority is to maintain financial stability. Their longer-term goal of building a six-month emergency fund reflects a shift towards more disciplined money management and greater preparation for unexpected events.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0