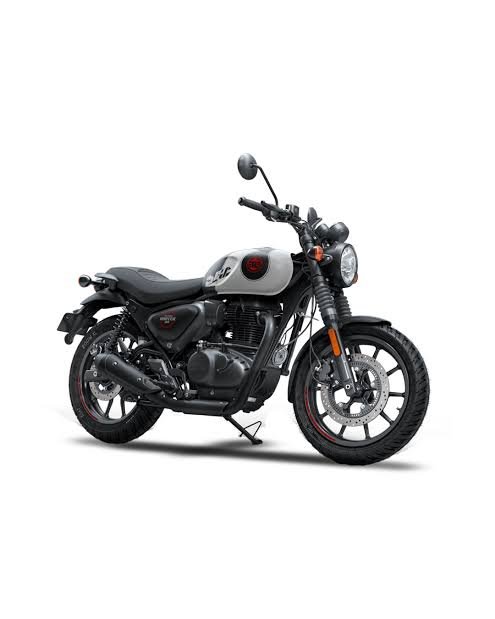
The Royal Enfield Hunter 350 is the most affordable motorcycle in the brand’s lineup, making it an attractive option for buyers looking for a modern roadster with classic Royal Enfield styling. Among its variants, the Base Premium offers a good balance of price and equipment, adding alloy wheels, tubeless tyres and premium switchgear over the entry-level version.
Priced at Rs 1,52,235 (ex-showroom, Delhi), the Hunter 350 Base Premium can be purchased through financing to reduce the initial financial burden. Here is a breakdown of its estimated on-road price, down payment and monthly EMIs across three different loan tenures.
Royal Enfield Hunter 350 Base Premium: Price And On-Road Cost
The Hunter 350 Base Premium is priced at Rs 1,52,235 (ex-showroom, Delhi). After adding estimated RTO charges of Rs 19,643 and insurance costs of Rs 11,250, its approximate on-road price comes to Rs 1,83,128.
For this EMI calculation, we have considered a down payment of Rs 20,000 and an annual interest rate of 9.6 per cent. This brings the estimated loan amount to Rs 1,63,128.
| Price Details | Amount |
|---|---|
| Ex-showroom price | Rs 1,52,235 |
| Estimated RTO charges | Rs 19,643 |
| Insurance | Rs 11,250 |
| Estimated on-road price | Rs 1,83,128 |
| Down payment | Rs 20,000 |
| Loan amount | Rs 1,63,128 |
| Annual interest rate | 9.6% |
Royal Enfield Hunter 350 EMI Options
The monthly EMI depends largely on the loan tenure. A shorter repayment period means higher monthly instalments but lower overall interest, while a longer tenure reduces the monthly payment at the cost of increasing the total amount paid to the lender.
18-Month Loan: Lowest Overall Interest
The 18-month repayment option is suitable for buyers who can comfortably manage a higher monthly EMI and want to clear their loan quickly. Under this plan, the estimated monthly instalment is Rs 9,981.
The total interest payable over the loan period is Rs 12,959. This takes the total loan repayment, including the principal and interest, to Rs 1,79,658.
Although the monthly financial commitment is the highest among the three options, this tenure helps minimise the additional cost of financing. It is worth considering if your monthly budget allows you to pay nearly Rs 10,000 towards the motorcycle.
24-Month Loan: A Balanced Option
The 24-month plan offers a middle ground between monthly affordability and overall interest costs. The estimated EMI drops to Rs 7,662, making it easier to manage compared with the 18-month option.
However, extending the repayment period increases the interest outgo. You will pay Rs 17,189 in interest over two years, taking the total loan repayment to Rs 1,83,888.
This option may suit buyers who want to keep their monthly instalments relatively manageable without extending the loan for too long. The additional interest compared with the 18-month plan is a trade-off for the lower monthly payment.
36-Month Loan: Lowest Monthly EMI
If keeping the monthly financial commitment low is your priority, the 36-month repayment option offers the lowest EMI of the three plans. The estimated monthly instalment comes to Rs 5,348.
The downside is the higher overall interest cost. Over the three-year tenure, the interest payable reaches Rs 25,829, taking the total loan repayment to Rs 1,92,528.
Compared with the 18-month option, this plan costs approximately Rs 12,870 more in interest. It may be suitable for buyers who need a lower monthly EMI, but it is important to consider the higher overall cost before choosing a longer repayment period.
Hunter 350 Base Premium: EMI Comparison
| Loan Tenure | Monthly EMI | Total Interest | Total Loan Repayment |
|---|---|---|---|
| 18 months | Rs 9,981 | Rs 12,959 | Rs 1,79,658 |
| 24 months | Rs 7,662 | Rs 17,189 | Rs 1,83,888 |
| 36 months | Rs 5,348 | Rs 25,829 | Rs 1,92,528 |
Note: These are estimated figures based on the stated loan amount and interest rate. Actual EMI and repayment amounts may vary depending on the lender’s calculations and applicable charges.
Is The Hunter 350 Base Premium Worth Buying?
The Base Premium variant makes a strong case for itself because it adds some useful equipment without moving too far up the price ladder. Its most notable advantage over the entry-level Base variant is the inclusion of alloy wheels with tubeless tyres.
Tubeless tyres are generally more convenient when dealing with punctures, as they can often retain air for longer after a puncture than conventional tube-type tyres. This can make everyday ownership easier, particularly for riders who regularly travel through busy city roads.
The variant also gets a Tarmac Black paint scheme and premium switchgear, along with an assist and slipper clutch. These additions improve the overall package while retaining the Hunter’s accessible positioning within the Royal Enfield range.
However, the Base Premium is available in only one black colour option. Buyers looking for more colour choices may need to consider other variants.
What To Consider Before Taking A Bike Loan
Financing the Hunter 350 can make the purchase easier by spreading the cost over several months instead of paying the entire amount upfront. However, the total amount paid will be higher because of the interest charged by the lender.
Your credit score, income and loan eligibility can influence the interest rate and financing terms offered by a bank or financial institution. The down payment and final EMI may also differ depending on the lender and dealership.
Before signing a loan agreement, check the processing fees, repayment schedule, foreclosure conditions and any additional charges. It is also important to choose an EMI that comfortably fits your monthly budget rather than focusing only on getting the motorcycle quickly.
Our Take
The Royal Enfield Hunter 350 Base Premium is a sensible choice for buyers who want the brand’s roadster experience without stretching their budget too much. Its alloy wheels, tubeless tyres, premium switchgear and assist and slipper clutch make it a more appealing purchase than the entry-level Base variant.
Among the three financing options, the 18-month plan is the most economical in terms of total interest, provided you can manage its higher EMI. The 24-month option offers a reasonable balance between monthly payments and interest costs, while the 36-month plan is better suited to buyers who need to keep their monthly outgo lower.
Ultimately, the right loan tenure depends on your financial situation. Compare the available offers, check the final on-road price at your dealership and read the loan terms carefully before making a decision.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Automobile on thefoxdaily.com.


COMMENTS 0