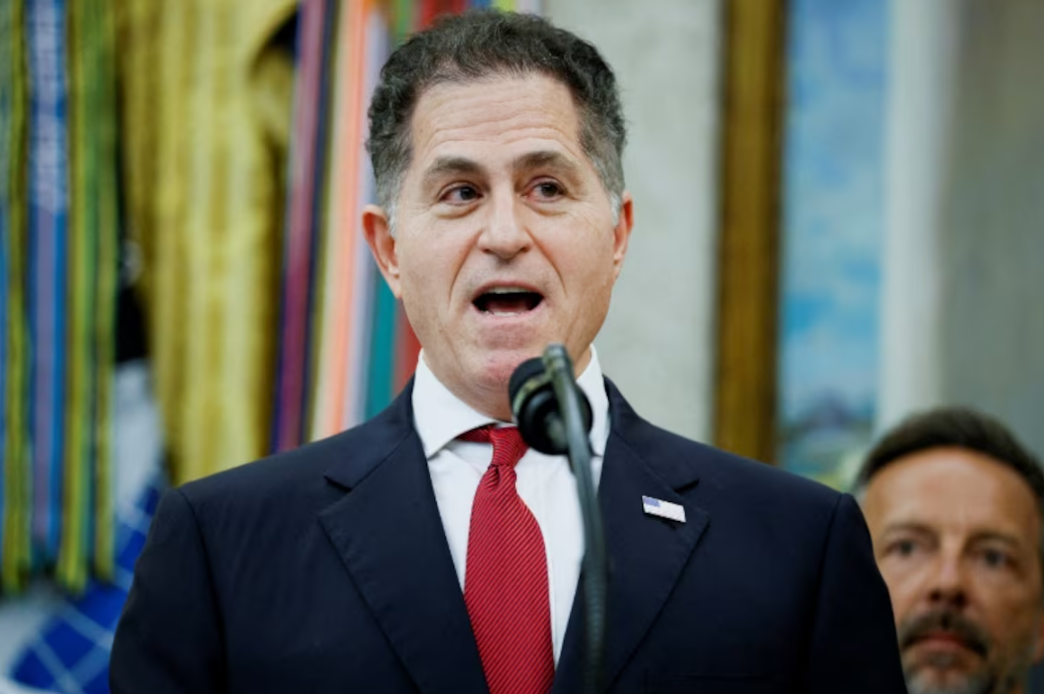
Baldwin Insurance Group is set to become a privately held company after DFO Management, associated with Dell Technologies founder and CEO Michael Dell, and Sequence Holdings agreed to acquire the insurance services company in a deal valued at approximately $7.7 billion.
Under the agreement, Baldwin shareholders will receive $32.50 in cash for each share. The transaction represents a substantial premium to Baldwin’s pre-deal market value and gives investors a clear cash exit while opening a new chapter for the insurance technology and risk-management company under private ownership.
The proposed transaction is also notable because of Michael Dell’s involvement through DFO Management. Dell has built one of the world’s largest technology businesses, and his participation adds a prominent technology-investment dimension to a deal involving a company that combines insurance advisory services with technology-enabled underwriting and risk-management solutions.
Baldwin Insurance Group Deal Valued at $7.7 Billion
DFO Management and Sequence Holdings announced on September 14 that they had reached an agreement to take Baldwin Insurance Group private. The transaction values the company at approximately $7.7 billion.
The agreed consideration is $32.50 per Baldwin share in cash. For shareholders, the all-cash structure provides certainty about the headline purchase price rather than leaving the value dependent on the future performance of the acquiring companies or broader stock-market conditions.
Baldwin’s shares were trading around $31.69 in premarket trading after the announcement, up 6.9%. The stock had been valued at roughly $4.14 billion before the deal-related repricing.
The acquisition therefore represents a significant step-up from Baldwin’s earlier public-market valuation.
| Deal detail | Information |
|---|---|
| Target | The Baldwin Insurance Group |
| Buyers | DFO Management and Sequence Holdings |
| Deal value | Approximately $7.7 billion |
| Cash consideration | $32.50 per share |
| Premium | About 88% to the June 17 closing price |
| Earlier market value | Approximately $4.14 billion |
| Transaction structure | Take-private acquisition |
Why the $32.50 Per-Share Price Matters
The $32.50 cash offer represents an approximately 88% premium to Baldwin’s June 17 closing price, the day before media reports emerged about a potential go-private transaction.
Using a pre-rumor date is important when evaluating an acquisition premium. Once reports of a possible transaction enter the market, the target company’s share price can rise as investors begin anticipating a takeover. Comparing the final offer with an unaffected share price gives a clearer picture of the premium being offered to shareholders before deal speculation influenced trading.
The premium also illustrates the difference between public-market valuation and the price a strategic or financial buyer may be willing to pay for control of a business.
Public investors value companies continuously based on expected earnings, market conditions, interest rates and industry sentiment. A private buyer, by contrast, can place additional value on long-term strategy, operational changes, technology investments or opportunities that may take years to produce results.
What Is Baldwin Insurance Group?
The Baldwin Insurance Group operates in the insurance and risk-management industry. Its business includes risk management solutions, insurance advisory services and technology-enabled underwriting for businesses and individuals.
This combination is important because insurance is increasingly influenced by data, technology and specialized risk analysis. Companies and individuals need more than traditional insurance placement when risks become complex, while insurers need better information and technology to evaluate and price those risks.
Baldwin’s technology-enabled approach places it at the intersection of traditional insurance services and a more digitally driven insurance ecosystem.
Key Areas of Baldwin’s Business
- Risk management: Helping clients identify and manage financial and operational risks.
- Insurance advisory: Providing guidance around insurance coverage and related requirements.
- Underwriting technology: Using technology-enabled processes to support insurance underwriting.
- Business insurance: Serving companies with insurance and risk-related requirements.
- Individual solutions: Providing insurance-related services to individuals as well as organizations.
Why Take Baldwin Private?
The deal raises a broader question: why would investors choose to take an established insurance company private rather than continue operating it as a listed business?
One potential advantage of private ownership is greater flexibility. Public companies must regularly communicate with shareholders and operate under the pressure of quarterly market expectations. Private owners can potentially take a longer-term approach to technology investments, acquisitions, organizational changes and business expansion.
For a company operating across insurance advisory and technology-enabled underwriting, that flexibility could be particularly relevant if management believes significant investments are required before their full benefits become visible in financial results.
Private ownership can also make it easier to restructure a business or pursue strategic initiatives without the same level of immediate public-market scrutiny. However, these advantages come with substantial financial commitments for the buyers, who must ultimately generate sufficient returns from the acquired business.
Michael Dell’s Role Adds a Technology Dimension
DFO Management’s connection to Michael Dell makes the transaction especially noteworthy outside the insurance industry.
Dell is best known for building Dell Technologies into a major global technology company. His participation through DFO Management places an experienced technology entrepreneur and investor behind a transaction involving a company whose business model includes technology-enabled insurance operations.
That does not mean Baldwin is becoming part of Dell Technologies. The transaction is being undertaken by DFO Management and Sequence Holdings, and Baldwin’s business remains focused on insurance and risk management.
Nevertheless, Dell’s involvement could attract additional attention to the potential role of technology, data and digital processes in the future of insurance services.
Insurance and Technology Are Becoming More Closely Connected
Modern insurance increasingly depends on technology. Insurers and insurance intermediaries use data to understand risks, automate processes, improve customer experiences and support underwriting decisions.
Technology can also help insurance businesses process large amounts of information more efficiently. For risk-management companies, digital tools can improve how risks are identified, monitored and communicated to clients.
This makes businesses combining insurance expertise with technology potentially attractive to investors looking for exposure to both sectors.
Baldwin’s positioning in risk management, insurance advisory and technology-enabled underwriting means its future strategy could benefit from continued digitization across the insurance industry.
Potential Strategic Opportunities Under Private Ownership
- Greater flexibility to invest in technology and digital infrastructure.
- Potential expansion of technology-enabled underwriting capabilities.
- Opportunities to pursue acquisitions or partnerships.
- Longer-term investment horizons without quarterly public-market pressure.
- Potential operational restructuring or efficiency improvements.
These are potential strategic benefits of private ownership rather than confirmed plans announced as part of the transaction. The eventual strategy will depend on the buyers and Baldwin’s management after the deal closes.
The Deal Comes With a Large Valuation Gap
One of the most striking aspects of the transaction is the gap between Baldwin’s earlier market valuation and the agreed takeover value.
The company had a market value of approximately $4.14 billion, while the proposed transaction is valued at about $7.7 billion. The difference demonstrates the scale of the control premium and other transaction considerations reflected in the proposed purchase.
It is important not to interpret the two figures as a simple measure of shareholder profit, because transaction value and equity market capitalization are not always directly comparable. Deal value can incorporate factors such as debt and other financial obligations, depending on the structure of the transaction.
Still, the figures demonstrate that buyers are offering a substantial premium compared with Baldwin’s earlier public-market valuation.
| Measure | Amount | What it indicates |
|---|---|---|
| Earlier Baldwin market value | About $4.14 billion | Public-market valuation before the transaction |
| Take-private deal value | About $7.7 billion | Value associated with the proposed acquisition |
| Offer price | $32.50 per share | Cash consideration for shareholders |
| Premium to June 17 close | About 88% | Premium measured against the pre-rumor price |
What the Transaction Means for Baldwin Shareholders
For existing Baldwin shareholders, the most immediate consequence is the opportunity to receive cash at the agreed offer price if the transaction closes under the announced terms.
The large premium can be particularly attractive to investors who purchased shares before the takeover speculation emerged. Instead of continuing to face the uncertainty of public-market trading, shareholders would receive a defined cash consideration through the transaction process.
However, as with any major acquisition, the transaction still needs to progress through the applicable closing conditions and processes. Until a deal formally closes, shareholders remain exposed to the possibility that circumstances could change.
What a Take-Private Deal Means for Public Investors
When a publicly traded company is acquired and taken private, its shares generally cease to trade publicly after completion of the transaction, subject to the deal’s final structure and closing process.
This changes the company’s relationship with public investors. Baldwin would no longer have to operate as a publicly listed company after the transaction closes, while the new owners would assume responsibility for the company’s future growth and financial performance.
For the broader market, large take-private transactions can also indicate that private capital sees opportunities in companies whose public-market valuations may not fully reflect their long-term potential.
Why the Deal Is Significant for the Insurance Sector
The Baldwin transaction highlights the continuing attractiveness of insurance-related businesses to investment groups. Insurance companies and intermediaries can generate recurring demand because businesses and individuals need coverage and risk-management services across economic cycles.
At the same time, the industry is undergoing technological change. Digital underwriting, data analysis and technology-supported advisory services are reshaping how insurance risks are assessed and managed.
A large take-private transaction involving a company with both insurance expertise and technology-enabled operations therefore provides another example of how financial investors may view insurance as a technology-driven growth opportunity rather than simply a traditional financial-services business.
Potential Challenges for the New Owners
Despite the attractive strategic possibilities, paying a substantial premium creates a demanding financial challenge for the buyers. The new owners will need Baldwin’s underlying business performance to justify the acquisition price over time.
Insurance markets can also be affected by economic conditions, changing risks, competition, regulatory requirements and shifts in customer demand. Technology investments can improve efficiency but require capital and careful execution.
The buyers will therefore need to balance growth ambitions with operational discipline.
Key Risks to Monitor
- Integration risk: Combining ownership, management and strategic priorities can create execution challenges.
- Valuation risk: A high acquisition price increases the pressure to deliver future growth.
- Insurance-cycle risk: Industry pricing and competitive conditions can change over time.
- Technology investment risk: Digital initiatives require capital and successful implementation.
- Regulatory considerations: Insurance businesses operate within extensive regulatory frameworks.
What Investors Should Watch Next
The next stage of the Baldwin transaction will focus on the formal process required to complete the acquisition. Investors will want to monitor the company’s disclosures for information about closing conditions, regulatory approvals, shareholder-related procedures and the expected completion timeline.
Beyond the transaction itself, the market will also watch what the new owners intend to do with Baldwin once it becomes private.
Questions around technology investment, business expansion, operational efficiency and potential acquisitions could provide clues about how DFO Management and Sequence Holdings intend to create value from the deal.
Key Takeaways From the Baldwin Take-Private Deal
- DFO Management and Sequence Holdings agreed to acquire Baldwin Insurance Group in a deal valued at approximately $7.7 billion.
- Baldwin shareholders are set to receive $32.50 in cash per share under the announced agreement.
- The offer represents an approximately 88% premium to Baldwin’s June 17 closing price before reports of a potential go-private transaction emerged.
- Baldwin provides risk management, insurance advisory and technology-enabled underwriting solutions.
- Michael Dell’s involvement through DFO Management adds a major technology-investment angle to the insurance transaction.
- The deal could give Baldwin greater flexibility to pursue long-term technology and strategic initiatives away from public-market pressures.
Conclusion: $7.7 Billion Baldwin Deal Signals Confidence in Insurance and Technology
The proposed $7.7 billion Baldwin Insurance Group take-private deal is significant both for the insurance sector and for the broader private-investment market. The $32.50-per-share cash offer provides shareholders with a substantial premium, while the buyers gain control of a company operating across risk management, insurance advisory and technology-enabled underwriting.
Michael Dell’s involvement through DFO Management adds another layer of interest because technology is becoming increasingly important to the insurance industry’s future. Baldwin’s combination of insurance expertise and technology-driven services could provide opportunities for the new owners to pursue long-term growth and operational improvements.
The biggest question now is how the buyers will translate the premium paid for Baldwin into future value. The transaction demonstrates confidence in the company’s business, but the success of the deal will ultimately depend on execution, industry conditions and the ability to build a stronger and more technology-driven insurance platform under private ownership.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0