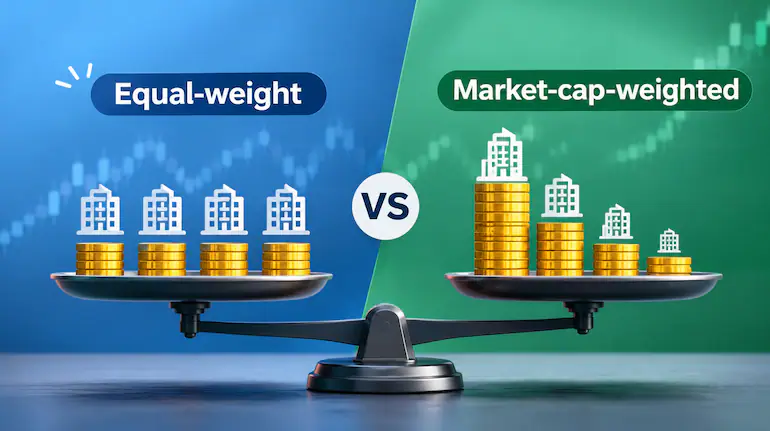
Investing in leading companies does not always mean investing in them in the same way. The method used to allocate capital across stocks can significantly influence a portfolio’s concentration, sector exposure and overall performance. Two widely used approaches are equal-weight investing and market-capitalisation-weighted investing.
In India’s evolving equity market, companies are benefiting from structural trends such as economic growth, rising consumption, financialisation and infrastructure development. However, identifying which companies will lead the next phase of market performance remains difficult. Investors can therefore consider different index-weighting methods to determine how they participate in the performance of established businesses.
Market-capitalisation-weighted indices allocate more capital to companies with larger investible market values. Equal-weight indices, in contrast, distribute capital evenly among their constituents. Neither approach guarantees better returns, but each offers a distinct way of gaining exposure to market leaders.
What Is Equal-Weight Investing?
Equal-weight investing is an index strategy in which every constituent receives the same allocation, regardless of its market capitalisation. Unlike conventional indices, where the largest companies have the greatest influence on performance, an equal-weight index gives each selected stock a comparable starting weight.
This approach allows investors to participate in the performance of leading companies while reducing their dependence on a small number of the largest constituents. It also gives relatively smaller companies within the selected universe a more meaningful role in determining portfolio returns.
The Nifty Top 15 Equal Weight Index illustrates this investment approach. It comprises 15 companies selected from the Nifty 50 universe based on their six-month average free-float market capitalisation. At the time of rebalancing, each constituent receives an equal weight of approximately 6.67%.
These allocations do not remain exactly equal throughout the period. Changes in individual stock prices cause constituent weights to fluctuate until the next scheduled rebalancing restores the intended structure.
How Market-Capitalisation-Weighted Indices Work
A market-capitalisation-weighted index assigns weights to companies according to their investible market value. In indices such as those based on free-float market capitalisation, the calculation considers the market value of shares available for public investment rather than the company’s entire equity value.
Under this method, companies with larger free-float market capitalisations receive higher index weights. Their share-price movements consequently have a greater influence on the index’s overall performance. Smaller constituents receive lower allocations and make a relatively limited contribution to returns.
One advantage of this structure is that it broadly reflects the relative size of companies in the investible equity market. It also adjusts automatically as stock prices and market values change, without requiring frequent reallocation to maintain market-cap-based weights.
However, the approach can lead to portfolio concentration. When a few large companies account for a substantial share of an index, their performance can become a major driver of overall returns. If these stocks decline, the impact on the index may be significant even when several smaller constituents perform well.
Equal-Weight vs Market-Cap-Weighted Index: Key Differences
The primary difference between the two approaches lies in how capital is distributed among index constituents. Market-capitalisation weighting gives greater influence to larger companies, while equal weighting provides the same initial allocation to every selected stock.
Consider a simple example involving two companies. Suppose a market-capitalisation-weighted index allocates 10% to one company and 2% to another. If both stocks rise by 10%, the first company contributes one percentage point to the index return, while the second contributes 0.2 percentage points, assuming other factors remain unchanged.
In an equal-weight portfolio, both companies initially receive the same allocation. An identical percentage movement in either stock would therefore have the same initial impact on portfolio returns.
The distinction is not that smaller companies will necessarily outperform larger ones. Instead, equal weighting changes how much influence each constituent has on the portfolio.
Major Differences Between the Two Strategies
- Capital allocation: Market-cap-weighted indices allocate capital according to investible market value, while equal-weight indices distribute it evenly among constituents.
- Influence of large companies: Larger companies have a greater impact on market-cap-weighted index performance. Equal weighting reduces their relative influence.
- Exposure to smaller constituents: Equal-weight strategies give relatively smaller companies within the selected universe a higher allocation than they generally receive in market-cap-weighted indices.
- Rebalancing: Market-cap-weighted indices adjust naturally with changes in market values, while equal-weight indices require periodic rebalancing to restore equal allocations.
- Portfolio concentration: Market-cap weighting can increase dependence on the largest stocks, whereas equal weighting limits concentration at the individual-stock level, although sector concentration can still occur.
Why Periodic Rebalancing Matters in Equal-Weight Investing
Rebalancing is an essential part of an equal-weight strategy because stock prices change continuously. When some constituents outperform others, their portfolio weights increase. Underperforming stocks gradually account for a smaller share of the portfolio.
Without periodic adjustments, an equal-weight portfolio would gradually move away from its original allocation structure and become increasingly influenced by stocks that have appreciated more strongly.
The Nifty Top 15 Equal Weight Index realigns constituent weights quarterly, generally at the end of March, June, September and December. Its constituent composition is reviewed semi-annually, in March and September.
During the rebalancing process, allocations to stocks whose weights have increased are reduced, while allocations to those whose weights have declined are increased. This restores the equal-weight structure at the scheduled adjustment point.
How Rebalancing Can Affect Portfolio Returns
The process creates a systematic mechanism for trimming relative outperformers and adding to relative underperformers. However, it should not be interpreted as a signal that an underperforming company is undervalued or likely to recover.
A stock that has declined may continue to fall, while a stock that has performed strongly may continue to outperform. Rebalancing follows the index methodology rather than making a prediction about future stock prices.
For investors, this provides a disciplined way to maintain the intended allocation without requiring them to make individual stock-selection or market-timing decisions. However, the process can also generate portfolio turnover and associated transaction costs.
When Can Equal-Weight Investing Perform Better?
Equal-weight investing can benefit from periods when market participation broadens beyond a small group of large companies. When relatively smaller constituents within an index perform strongly, their higher allocations can contribute more meaningfully to portfolio returns.
For example, if several companies outside the largest market leaders experience stronger earnings growth or benefit from improving economic conditions, an equal-weight portfolio may capture more of their performance than a market-cap-weighted index.
However, this does not mean that equal-weight strategies will consistently outperform. Their performance depends on the relative returns of individual constituents and the broader market environment.
When Can Market-Cap Weighting Have an Advantage?
Market-capitalisation-weighted indices may perform better when a relatively small group of large companies drives the broader market rally. Since these companies already have higher allocations, their gains have a greater influence on index performance.
This structure can be particularly relevant when established market leaders benefit from strong earnings, favourable business conditions or investor demand. In such periods, an equal-weight index may not capture as much of the rally because it assigns smaller initial allocations to the largest companies.
Market-cap weighting also offers investors exposure that broadly follows the relative size of companies in the investible market. For those seeking to track the market’s existing composition, this can be an important consideration.
Risks and Trade-Offs Investors Should Understand
Equal weighting changes the distribution of portfolio exposure, but it does not eliminate equity-market risk. Investors should understand several trade-offs before choosing between the two approaches.
1. Higher Portfolio Turnover
Equal-weight indices require periodic rebalancing to maintain their allocation structure. This can lead to more frequent buying and selling compared with market-cap-weighted indices, potentially increasing transaction costs and other expenses.
2. Greater Sensitivity to Smaller Companies
Equal weighting gives relatively smaller companies within the selected universe a greater role in portfolio performance. This can be beneficial when these companies outperform, but it can also increase sensitivity to their price declines and business-related risks.
3. Sector Concentration
Equal weighting individual stocks does not mean that every sector receives an equal allocation. If several constituents belong to the same sector, that sector may account for a relatively large share of the portfolio. Investors should therefore examine sector exposure rather than assuming that equal stock weights automatically create sector diversification.
4. No Guarantee of Recovery
Adding to an underperforming stock during rebalancing does not guarantee that its price will recover. A company may continue to face weak earnings, competitive pressures or other business challenges. Equal weighting is a portfolio-construction method, not a substitute for evaluating investment risks.
5. Performance Can Vary Across Market Cycles
There may be periods when large companies lead the market and market-cap-weighted indices benefit from their higher allocations. In other phases, broader participation among smaller constituents may favour equal-weight strategies. Investors should avoid judging either method solely on its performance over a short period.
Which Index Weighting Strategy Should Investors Consider?
The choice between equal-weight and market-capitalisation-weighted investing depends on an investor’s objectives, risk appetite and investment horizon.
Investors seeking exposure that reflects the relative size of companies in the investible market may prefer market-capitalisation weighting. Its structure allows larger companies to have a proportionately greater influence on returns and does not require regular rebalancing to maintain market-value-based allocations.
Investors who want to reduce their dependence on the largest constituents and give relatively smaller companies within a selected index a greater role may consider equal weighting. However, they should also account for rebalancing requirements, transaction costs and the possibility of greater exposure to smaller-company performance.
It is also important to examine the underlying index before investing. The number of constituents, selection criteria, sector distribution, rebalancing schedule and associated costs can all influence the experience of holding an index-linked investment. An equal-weight index containing a limited number of companies, for instance, may still have meaningful concentration risks.
Conclusion: Two Different Ways to Participate in Market Leadership
Equal-weight and market-capitalisation-weighted indices offer different ways to invest in leading companies. The former gives every constituent an equal starting allocation and uses periodic rebalancing to maintain that structure. The latter distributes capital according to companies’ investible market values, allowing larger businesses to have a greater influence on index returns.
Neither methodology is inherently superior. Market-cap weighting may benefit when the largest companies lead market performance, while equal weighting may gain from broader participation across constituents. Both approaches remain exposed to market fluctuations and company-specific risks.
Ultimately, equal-weight investing is not about predicting the next market winner or outperforming the broader market in every cycle. It is about changing how investors participate in the fortunes of leading companies. Rather than allowing market size alone to determine portfolio influence, it gives every constituent a more balanced opportunity to contribute to returns.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.

COMMENTS 0