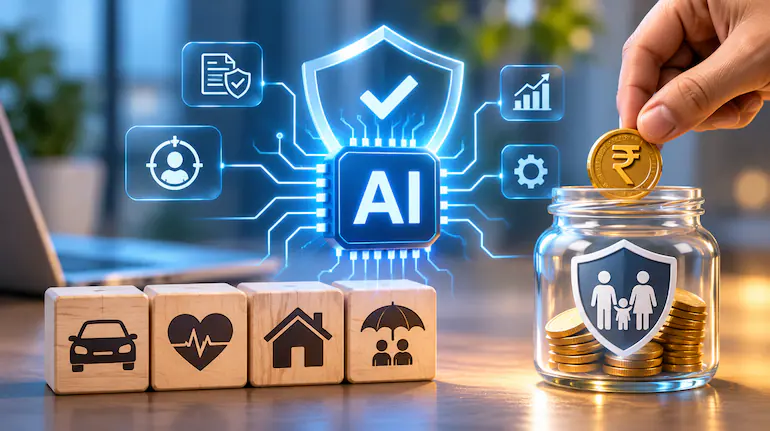
Artificial Intelligence (AI) is steadily changing how Insurance companies assess risk, determine premiums, process claims and interact with customers. While many of these developments happen behind the scenes, their impact can extend to the cost and convenience of insurance for policyholders.
Traditionally, insurance has focused on protecting individuals and businesses against unforeseen financial losses. Insurers relied on established information such as vehicle details, customer profiles, geographical location and historical claims to estimate the likelihood of future claims. AI is expanding this approach by analysing larger volumes of information, identifying patterns and supporting more detailed risk assessments.
This shift could help insurers price policies more appropriately, detect fraudulent claims, improve customer service and reduce operational expenses. For customers, these changes may translate into more suitable coverage, faster claim settlements and opportunities for savings.
However, AI does not automatically guarantee lower premiums. The benefits depend on the quality of data, the way insurers use technology and whether operational savings are passed on to policyholders.
How AI Is Making Insurance Risk Assessment More Accurate
Insurance pricing depends heavily on understanding risk. The likelihood of a customer making a claim can vary according to several factors, and no single parameter can provide a complete picture.
In motor insurance, traditional assessments may consider a vehicle’s make and model, registration location, customer profile and claims history. Health insurers may examine healthcare costs, geographical factors and previous claims. While these indicators remain important, AI can analyse multiple relevant data points together to identify patterns that conventional assessment methods may overlook.
Machine learning algorithms can process large datasets, identify correlations and help insurers develop more detailed risk profiles. This can support more personalised underwriting and pricing decisions, subject to applicable regulations and customer consent.
Role of KYC and Consent-Based Data Sharing
Mandatory Know Your Customer (KYC) processes and consent-based data-sharing frameworks, such as Account Aggregators, can provide additional information for financial assessments. Where customers provide the required consent and the information is relevant and legally permissible, insurers may use these insights alongside existing insurance records to develop a more comprehensive understanding of risk.
For example, a customer’s financial commitments and repayment patterns may offer additional context for certain risk assessments. AI can help identify meaningful relationships within the available information, although financial behaviour should not automatically be treated as a direct measure of insurance risk.
Such an approach could help insurers move beyond broad customer categories and evaluate individual risk more precisely. Customers with favourable claims histories, for instance, may have opportunities to receive more differentiated pricing, depending on the insurer’s underwriting framework and applicable rules.
How AI Can Help Reduce Motor Insurance Costs
Motor insurance is one of the areas where AI-based risk assessment can create visible benefits. Traditional policies often rely on factors such as vehicle type, location and historical claims. AI can supplement these indicators by analysing driving behaviour and vehicle usage information.
Pay-As-You-Drive Insurance
Pay-As-You-Drive (PAYD) insurance is an example of how technology can help align coverage with actual vehicle usage. Instead of relying only on conventional policy structures, these offerings can consider the distance a vehicle is expected to travel.
AI can analyse relevant usage patterns and help insurers estimate driving exposure. Customers who drive less may be able to select kilometre-based coverage that better matches their expected usage rather than paying for a higher distance allowance they may not need.
For someone who uses a car occasionally or primarily for short journeys, this type of policy may offer an opportunity to manage insurance expenses more efficiently. The actual savings, however, depend on the policy terms, premium structure and selected coverage.
More Personalised Risk Assessment
AI can also help insurers evaluate claims histories and other relevant information when assessing a customer’s risk profile. For instance, a policyholder with a favourable claims record across multiple vehicles may be considered for differentiated pricing when insuring another car, where the insurer’s underwriting rules permit it.
Such assessments can make pricing more responsive to individual circumstances. However, a lower-risk assessment does not guarantee a discount, as premiums also depend on coverage requirements, vehicle characteristics and other underwriting considerations.
AI Is Improving Health Insurance Assessment and Wellness Benefits
Health insurance presents another significant opportunity for AI applications. Healthcare costs and claims patterns can vary considerably across geographical areas, hospitals and treatment categories. AI can help insurers analyse these variations at a more granular level, including smaller geographical clusters and specific PIN codes.
By identifying patterns in claims and healthcare expenses, insurers may be able to improve their understanding of local risk and develop more relevant insurance products. This could support more detailed assessments instead of relying entirely on broad geographical categories.
Wellness Data and Preventive Healthcare
AI can also support wellness-linked insurance offerings by analysing relevant activity information, where customers have consented to its use. Data such as daily movement and exercise patterns may help insurers design benefits that encourage healthier habits.
For example, some insurance propositions may offer incentives or discounts linked to participation in wellness activities. These programmes can encourage preventive healthcare while giving customers an additional reason to maintain an active lifestyle.
However, activity data should not be treated as a definitive measure of an individual’s health. Such information needs to be interpreted carefully, with appropriate safeguards for privacy, fairness and customer consent.
Faster Claims Settlement Through AI-Powered Assessment
One of the most noticeable ways AI is changing insurance is through claims processing. Traditionally, claim assessments could involve several stages, including document verification, damage inspection, information matching and manual review. These steps may take time, particularly when the information is incomplete or requires further investigation.
AI-powered systems can automate parts of this process by analysing documents, photographs, claims histories and other relevant information. This can help insurers identify inconsistencies and prioritise cases that require human assessment.
AI in Motor Insurance Claims
In motor insurance, AI can analyse vehicle damage images, accident photographs and previous claims records to assess whether reported damage appears consistent with the incident. These systems can identify unusual patterns or potential discrepancies that may require further investigation.
AI-powered motor claim assessments can now take around 20 minutes, reducing waiting times for customers in processes where the technology is suitable and the available information is sufficient.
Faster assessments can improve the customer experience by reducing delays between claim submission and initial evaluation. Nevertheless, complex cases may still require physical inspections, additional documentation or human intervention before a final decision is made.
Detecting Fraud in Health Insurance
Health insurance claims can involve multiple stakeholders, including policyholders, hospitals, healthcare professionals and intermediaries. Identifying unusual billing patterns or potentially suspicious relationships across these participants can be challenging when information is spread across large datasets.
AI can analyse claims, billing information and treatment records to flag unusual patterns that may indicate possible fraud or collusion. Identifying such trends before claims are settled can help insurers investigate suspicious cases and prevent avoidable losses.
Fraudulent claims can contribute to the overall cost of insurance. Better detection may therefore support the financial sustainability of the insurance ecosystem and help protect genuine policyholders from costs associated with fraudulent activity.
However, an AI-generated alert should not be treated as proof of fraud. Human judgement, verification and due process must remain central to claim decisions to prevent genuine policyholders from being unfairly denied coverage.
Climate Intelligence: Helping Insurers and Customers Prepare for Risks
AI is also expanding the role of insurance beyond responding to losses after an event. Climate intelligence tools can analyse historical weather information, changing climate patterns and environmental data to help insurers understand exposure to events such as heavy rainfall and storms.
These insights can support better risk assessment for individuals and businesses located in areas vulnerable to extreme weather. Insurers may also use relevant information to provide timely alerts and encourage customers to take preventive measures.
For example, businesses can use risk information to assess whether their existing coverage is adequate before a severe weather event. Individuals may also be encouraged to review their protection against location-specific risks rather than waiting until damage occurs.
This creates an opportunity to shift the focus from financial protection after a loss towards greater preparedness before an event. Although AI cannot prevent extreme weather, better information can help insurers and customers make more informed decisions.
How AI Can Reduce Insurance Operating Costs
AI’s impact extends beyond underwriting, pricing and claims. It can also change the cost of delivering insurance by automating routine business operations and customer-service activities.
Insurance companies handle a large volume of customer interactions, including policy enquiries, premium-related questions, document requests and claim-status updates. Traditionally, many of these activities required employee involvement, increasing the time and resources needed to serve customers.
AI-powered chatbots, automated calling systems and digital assistants can manage a significant share of routine interactions. These tools can provide responses, guide customers through standard processes and direct more complicated requests to employees.
Lower Expenses and Better Customer Service
Automation can help insurers improve productivity and manage their Expenses of Management (EoM). By reducing the time spent on repetitive activities, employees can focus on cases that require human judgement, specialist knowledge or personalised assistance.
Digital bots are already serving around seven in ten customers, indicating how technology is becoming part of everyday insurance interactions. Customers may not always recognise that an AI-powered system is handling a request, but they may experience the benefits through quicker responses and more convenient servicing.
As these systems scale, insurers may be able to reduce operational overheads and improve efficiency. Lower operating costs can create opportunities for more competitive insurance offerings and better value for customers.
However, efficiency gains do not automatically translate into lower premiums. Whether customers benefit financially depends on insurers’ pricing decisions, competitive conditions and the extent to which cost savings are passed on to policyholders.
What Customers Should Know About AI in Insurance
Although AI can improve insurance processes, customers should understand how their information is being used and what role technology plays in important decisions.
- Check data consent: Customers should understand what information an insurer collects, why it is required and whether it will be shared with other parties.
- Review policy conditions: AI-enabled pricing or usage-based coverage may involve specific eligibility requirements, limits and conditions.
- Do not assume every automated decision is final: Customers should have access to appropriate channels for clarification or review when a claim or policy decision is disputed.
- Compare coverage, not just premiums: A lower premium may involve different coverage limits, exclusions or conditions. The overall value of a policy matters more than price alone.
- Protect personal information: Customers should pay attention to privacy safeguards and the security of sensitive financial, health and activity data.
Challenges: Why Responsible AI Implementation Matters
AI is not a guaranteed solution to every challenge in insurance. Its effectiveness depends on the accuracy, relevance and reliability of the information used to train and operate these systems. Poor-quality or incomplete data can produce inaccurate assessments and potentially unfair outcomes.
Privacy is another important consideration. Insurance companies may process sensitive financial, health and behavioural information. Responsible use requires appropriate consent, data protection and compliance with applicable regulations.
There is also a need for transparency. Customers should be able to understand the basis of important policy and claim decisions, particularly when automated systems influence the outcome. Human oversight remains essential in situations involving complex claims, disputed information or potential fraud.
Insurers must therefore balance technological efficiency with fairness, accountability and customer protection. The objective should be to use AI to improve decision-making, not simply to automate processes without considering their impact on policyholders.
Conclusion: AI Could Make Insurance More Efficient and Affordable
Artificial Intelligence is changing insurance by helping companies understand risk more accurately, improve pricing assessments, identify potentially fraudulent claims and process genuine requests more efficiently. Its applications extend from Pay-As-You-Drive motor policies and wellness-linked health insurance to automated customer service and climate-risk analysis.
For customers, the benefits may appear in the form of more relevant coverage, faster claim assessments, improved service and potential cost savings. Much of this change may happen behind the scenes, without policyholders directly interacting with AI systems.
However, better technology does not automatically mean cheaper insurance. The real benefits will depend on responsible data use, reliable assessments, regulatory compliance and whether efficiency gains reach customers.
Ultimately, AI’s value in insurance will not be measured simply by how many processes are automated or how quickly a claim is settled. It will be measured by whether it helps insurers understand risk more accurately, price it more appropriately and serve customers more efficiently. Perhaps the smartest insurance saving is not the money received after something goes wrong, but the money potentially saved because better risk intelligence helps prevent avoidable losses in the first place.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0