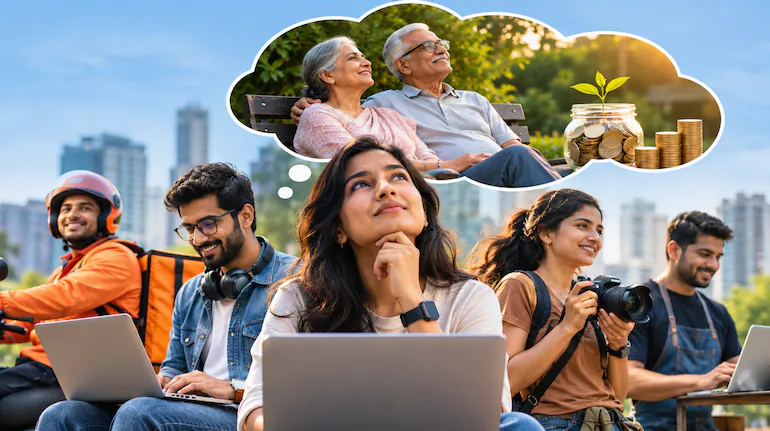
India’s retirement system faces a growing challenge as gig work, freelancing, consulting and self-employment become increasingly common. Traditional pension arrangements have largely been designed around stable employment, predictable monthly salaries and regular contributions. But for workers whose earnings fluctuate from month to month, maintaining a fixed retirement-saving schedule can be difficult.
The scale of this workforce is expanding rapidly. India’s gig workforce increased from 77 lakh in 2020-21 to 1.2 crore in 2024-25, marking a 55% rise over four years, according to the Economic Survey 2025-26. Non-agricultural gig workers are projected to account for 6.7% of the total workforce by 2029-30.
This expansion raises an important question: can India’s pension ecosystem provide meaningful retirement security to people who do not have a fixed salary, employer-sponsored contributions or a predictable career path?
The challenge is not limited to accumulating savings. Retirement products must also help people convert their accumulated wealth into sustainable income after they stop working. With longer life expectancy and rising living costs, retirees increasingly need flexible withdrawal choices, inflation protection and options that reflect their individual financial circumstances.
Why India’s Traditional Retirement Model Does Not Fit Every Worker
India’s Retirement Planning framework has historically been built around a relatively predictable employment journey. An individual enters salaried employment, contributes regularly to a provident fund, accumulates savings over several decades and uses the resulting corpus to support life after retirement.
For employees in the organised sector, mechanisms such as the Employees’ Provident Fund (EPF) provide a structured way to accumulate retirement savings. Employer-linked contributions and regular salary deductions make the process easier to maintain.
However, the same structure may not work for a freelancer, self-employed professional or platform-based worker. Their earnings can vary significantly depending on the availability of projects, customer demand, working hours and business conditions.
A delivery partner may earn more during a busy month and considerably less during a slower period. A freelancer may receive payments only after completing a project, while a consultant could experience gaps between assignments. Workers who frequently move between salaried employment and independent work may also struggle to maintain consistent contributions.
Vishwajeet Goel, Head of Pensionbazaar, said India’s workforce was becoming more diverse, but retirement planning remained structured around predictable monthly salaries, stable employment and employer-linked contributions.
He argued that this traditional model does not adequately reflect the financial realities of a growing section of the workforce.
Flexible Pension Contributions Are Becoming Essential
One of the biggest barriers to retirement planning for gig workers is the expectation that contributions should be made at fixed intervals. When income is irregular, committing to the same amount every month can become difficult.
Goel said the problem was not necessarily a lack of willingness to save. Instead, conventional retirement products may not provide enough flexibility to accommodate changing cash flows.
He suggested that pension products should allow workers to increase contributions when earnings are higher, reduce them during financially difficult periods and resume saving without unnecessary restrictions.
Such flexibility could make retirement planning more practical for people who do not receive a regular salary. A worker earning a higher amount during a particular month could contribute more, while someone experiencing a temporary decline in income could make smaller contributions without abandoning the savings habit entirely.
Low minimum contribution requirements could also help bring more workers into the retirement system. For individuals with limited financial reserves, even a relatively small starting contribution may be easier to manage than a rigid monthly commitment.
However, flexibility alone will not solve the problem. Retirement products must also be affordable, easy to understand and accessible through simple digital processes. Workers need to understand how contributions are invested, what charges apply and how their savings can be accessed later.
Why Portable Retirement Accounts Matter for Gig Workers
Another important requirement is portability. Traditional employment arrangements often make retirement contributions easier to track because savings are linked to an employer or a formal payroll system.
Gig workers and freelancers may move between multiple employers, digital platforms and independent assignments. Some may return to salaried employment after spending time in self-employment, while others may combine different sources of income throughout their working lives.
If retirement savings are difficult to transfer or manage across these transitions, workers may lose continuity in their long-term financial planning.
Portable retirement accounts could help address this problem by allowing individuals to maintain their accumulated savings even when their employment arrangements change. Instead of starting a new retirement plan every time they switch jobs or platforms, workers could continue building a single long-term corpus.
This is particularly important as careers become less linear. Retirement planning systems will increasingly need to recognise individuals rather than simply their current employer or employment category.
Can the National Pension System Help Self-Employed Workers?
The National Pension System (NPS) is one option through which individuals can build a market-linked retirement corpus outside traditional employer-linked arrangements. Its voluntary structure and digital access make it relevant to self-employed professionals and other individuals who want to save independently.
Unlike retirement arrangements that depend on regular employer contributions, the NPS provides a framework through which individuals can make their own retirement investments. This can be useful for freelancers, consultants and gig workers who want to establish a long-term savings habit.
However, participation depends on several practical factors. Workers must be aware of the scheme, understand its features and have sufficient financial capacity to contribute. Income volatility can also make regular investments difficult, even when a suitable savings product is available.
For gig workers, the challenge is therefore not simply whether a pension product exists. It is whether the product can accommodate irregular earnings without creating unnecessary financial pressure.
Government Steps to Expand Pension Coverage for Gig Workers
India has taken steps towards recognising the need for social security arrangements for gig and platform workers. One development is the National Pension System e-Shramik model, introduced by the Pension Fund Regulatory and Development Authority (PFRDA) in October 2025.
The initiative is intended to bring gig and platform workers into the pension system. The regulator subsequently extended the incentive framework for the model to FY27, providing a further policy measure aimed at expanding participation.
The government’s broader social security framework has also recognised gig and platform workers through the Code on Social Security, 2020, which came into force on November 21, 2025.
The Code provides for social security measures covering areas such as life and disability protection, accident insurance, health and maternity benefits, and old-age protection.
However, the distinction between legal provisions and actual benefits is important. The Code creates a framework for social security measures, but it does not automatically guarantee a pension to every gig worker. The benefits available will depend on the schemes framed and implemented under its provisions.
The next challenge is ensuring that these policy measures translate into accessible and meaningful support. Workers need clear information about eligibility, enrolment, contribution requirements and the benefits available to them.
Why Small Contributions and Early Planning Can Make a Difference
For workers with irregular earnings, retirement planning often competes with more immediate financial priorities. Paying rent, repaying loans, managing household expenses and maintaining an emergency fund may take precedence over saving for retirement.
This is understandable, particularly for individuals whose income is uncertain. A freelancer may need to retain money for business expenses, while a self-employed professional may have to manage periods when customers delay payments.
Nevertheless, postponing retirement planning for too long can reduce the time available to accumulate savings. Starting early, even with relatively small contributions, can provide a longer investment horizon.
Flexible pension products could help workers maintain this habit without forcing them to commit to amounts they cannot comfortably afford. The ability to pause and restart contributions may also make retirement saving more realistic during periods of financial uncertainty.
Financial awareness remains equally important. Workers need to understand the difference between emergency savings and retirement investments, assess their financial obligations and choose contribution levels that do not undermine their short-term stability.
A sustainable retirement plan should account for income fluctuations rather than assume that every worker can save the same amount every month.
Building a Retirement Corpus Is Only Half the Challenge
Retirement planning does not end when an individual accumulates a large savings corpus. The money must also generate income that can support expenses over several decades.
This becomes increasingly important as people live longer and face rising healthcare and everyday living costs. A retirement corpus that appears sufficient at the time of retirement may lose purchasing power over time if withdrawals and investment returns do not keep pace with inflation.
Annuities are one way to address the income requirement. They convert a lump sum into a regular stream of payments, helping retirees receive predictable income after leaving employment.
However, traditional annuity products may not provide enough flexibility for people with different retirement needs.
Goel said retirees should not be treated as a homogeneous group. Someone retiring at 58 with other investments and family responsibilities may have different requirements from someone retiring at 70 who prioritises predictable monthly income.
He argued that the industry needs to move towards greater personalisation in annuity design.
Retirement products could therefore benefit from more flexible payout structures, spouse benefits, liquidity options and greater transparency. Inflation protection is another important consideration because a fixed income stream may become less valuable as living costs increase.
Can Flexible Withdrawal Plans Improve Retirement Security?
One possible direction for India’s retirement-income market is to combine guaranteed annuity income with systematic withdrawal solutions. Such an approach could allow retirees to secure a basic income stream while keeping another portion of their retirement savings invested and accessible.
This combination could provide a balance between predictable income and flexibility. A retiree might use an annuity to meet essential recurring expenses while retaining an invested corpus for healthcare costs, unexpected financial needs or other future requirements.
The National Pension System’s Retirement Income Scheme (RIS), introduced in 2026, represents another development in this direction. It allows eligible retirees to receive systematic payouts from their withdrawable NPS corpus while the remaining funds continue to be invested.
However, these payouts are market-linked and should not be confused with guaranteed annuity income. The amount available to retirees can depend on investment performance and withdrawal decisions.
Goel said such solutions could give retirees greater control over how they use their accumulated savings. At the same time, he emphasised the need for clear communication about market risks, withdrawal rates and the possibility of exhausting the retirement corpus.
Inflation and Longer Life Expectancy Create New Retirement Risks
Retirement products must address two major long-term risks: inflation and longevity. Inflation gradually reduces the purchasing power of money, meaning retirees may need more income in later years to maintain the same standard of living.
Longevity creates another challenge. Individuals who live longer after retirement must make their savings last for a greater number of years. Withdrawing too much too early could leave them with insufficient funds later in life.
These risks make retirement-income planning more complicated than simply calculating how much money a person needs on their final working day.
For gig workers, the challenge can be even greater because they may not have employer-backed retirement benefits or a predictable contribution history. They may need to build their retirement corpus independently and decide how to convert it into income without a regular pension arrangement.
A combination of long-term investments, appropriate annuity products and carefully planned withdrawals could help address different retirement needs. However, the right balance will depend on an individual’s age, savings, income requirements, risk tolerance and other financial resources.
Is India’s Retirement System Ready for the Gig Economy?
India’s growing gig workforce is exposing a gap between traditional retirement arrangements and the changing nature of employment. Pension systems designed around stable salaries and employer-linked contributions may not be sufficient for workers who earn irregularly or move frequently between different forms of work.
Policy initiatives such as the NPS e-Shramik model and the social security framework for gig workers indicate that the issue is receiving greater attention. However, wider participation will depend on whether workers can access affordable products that match their financial realities.
The pension industry will also need to rethink how retirement savings are converted into income. More personalised annuities, flexible withdrawals, spouse benefits and better protection against inflation could help retirees manage financial needs over longer periods.
Ultimately, retirement security should not depend entirely on whether someone has a fixed salary or remains with one employer throughout their career. As India’s workforce becomes more diverse, the retirement system will need to become more portable, flexible and inclusive.
The central question is no longer just how much workers can save during their careers. It is whether the system can help them save when income is irregular and provide reliable financial support when regular work eventually stops.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.

COMMENTS 0