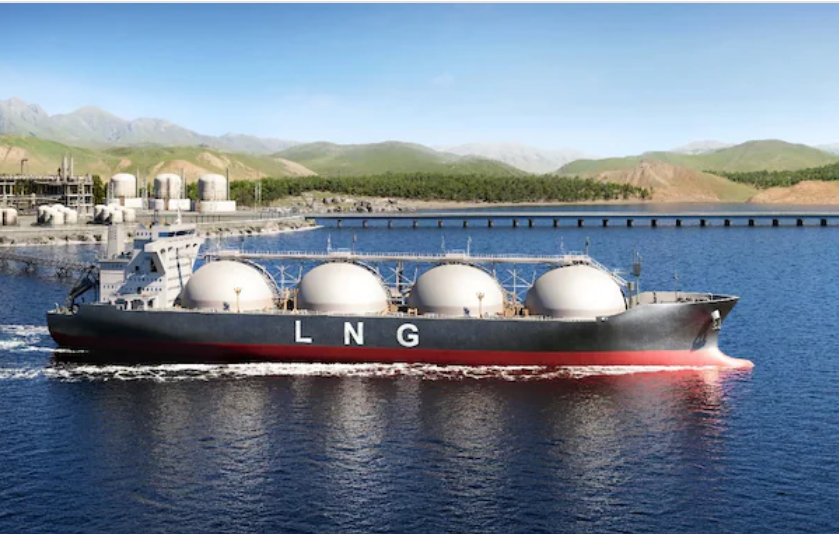
LNG demand in China, India and Pakistan could recover from multi-year lows once the Middle East supply crunch eases and new liquefied natural gas supplies enter the global market. The current disruption has pushed Asian spot LNG prices close to $30 per million British thermal units (MMBtu), compared with roughly $10 per MMBtu before the war.
The sharp increase in prices has forced some industrial and power-sector consumers to reduce natural gas consumption or switch to alternative fuels such as coal and oil. However, industry executives expect this weakness to be temporary if prices return to more affordable levels and additional LNG becomes available.
Why LNG Supplies Have Been Disrupted
The Iran war has severely affected LNG flows from the Middle East. Qatar and the United Arab Emirates normally rely heavily on shipping routes through the Strait of Hormuz, but the conflict has prevented most LNG from moving through this strategically important waterway.
The disruption has removed a substantial amount of supply from the international market. Shell estimates that around 36 million tonnes of LNG from the Middle East have been lost so far this year.
Because LNG is traded globally, a disruption in one major producing region can quickly affect buyers thousands of kilometres away. Asian consumers have consequently faced higher spot prices and greater competition for alternative cargoes.
| Market | Current Pressure | Potential Recovery Trigger |
|---|---|---|
| China | High LNG prices and reduced gas-fired power demand | Prices returning toward $7–$9/MMBtu and stronger electricity consumption |
| India | Price-sensitive industrial demand and supply disruption | Lower LNG prices and greater availability of alternative cargoes |
| Pakistan | Affordability constraints and supply limitations | Additional LNG volumes at more competitive prices |
Asian LNG Prices Have Nearly Tripled
The scale of the price shock explains why demand has weakened. Asian spot LNG prices have climbed to nearly $30/MMBtu, compared with approximately $10/MMBtu before the conflict.
For consumers that can switch between fuels, such a large increase changes the economics of energy consumption. Industries may reduce gas use, delay purchases or shift toward cheaper alternatives when possible.
This means that the decline in LNG demand should not necessarily be interpreted as a permanent change in consumption patterns. Much of the current weakness is driven by affordability rather than a fundamental loss of interest in natural gas.
India’s LNG Demand Is Highly Price Sensitive
India is among the markets expected to benefit significantly if LNG prices normalise. The country has expanded its gas infrastructure and uses natural gas across industries, power generation, city gas distribution and other applications.
However, the current price environment has exposed the sensitivity of several Indian consumers to LNG costs.
GAIL Chairman Deepak Gupta said several sectors can switch to other fuels when natural gas becomes too expensive. That flexibility protects businesses from extreme gas prices but also means LNG demand can fall quickly during a supply shock.
Petronet LNG CEO Akshay Kumar Singh similarly highlighted affordability as a major challenge. Consumers continue to need gas, but they are looking for prices that provide greater stability and predictability.
India Has Started Restoring Gas Supplies
India initially had to restrict gas consumption because of the Middle East supply disruption. The situation has subsequently improved, with supplies restored to around 90% to 95% of earlier levels as Indian buyers sourced LNG from other markets.
This response demonstrates the importance of diversification. Instead of depending entirely on a single producing region, Indian companies can search for cargoes from other international suppliers when Middle Eastern shipments are disrupted.
GAIL and PetroChina have deployed trading teams to identify alternative LNG cargoes and replace some supplies affected by the crisis.
India Could See a Major Increase in LNG Supply
The medium-term supply outlook could also support demand. GAIL expects approximately 150 million to 200 million tonnes of LNG to come online over the next four to five years.
If this additional supply reaches the global market as expected, competition among sellers could improve availability and potentially reduce some of the extreme price pressure seen during the current disruption.
For India, additional supply would be particularly important because affordability remains one of the main barriers to wider gas adoption. More available LNG could give industrial users greater confidence to return to gas-based operations.
Pakistan’s LNG Demand Could Also Recover
Pakistan is another price-sensitive LNG market. The country has faced energy supply challenges, and affordability plays an important role in determining how much LNG consumers can purchase.
Pakistan LNG CEO Masood Nabi expects demand could increase if additional volumes become available at more affordable prices.
Solar power has expanded in Pakistan and has helped address electricity shortages, but natural gas continues to serve households and other parts of the economy. This means cheaper LNG could still support a recovery in gas consumption even as renewable energy becomes more important.
The key variable is likely to be the delivered cost of gas. If LNG remains close to crisis-level prices, consumers will have strong incentives to find alternatives. If prices move lower, previously uneconomic demand can return.
China Could Become a Major Source of LNG Demand Recovery
China’s LNG market has enormous potential to rebound because of its large gas consumption base and extensive import infrastructure.
PetroChina International CEO Luo Yizhou expects demand from gas-fired power plants to recover when LNG prices return to a more normal range of approximately $7 to $9/MMBtu.
Electricity demand is expected to provide an important foundation for this recovery. When power consumption increases, gas-fired generation can become more attractive, particularly when gas prices are competitive with alternative fuels.
The current price shock has therefore created a temporary gap between China’s potential gas demand and the amount consumers are willing or able to purchase at elevated prices.
China’s LNG Infrastructure Supports Long-Term Demand
ExxonMobil expects substantial long-term LNG demand growth in China. One factor supporting that outlook is China’s extensive LNG import infrastructure, particularly along its eastern coastline.
A large network of import terminals gives China the physical capacity to receive international LNG cargoes. As additional global supply becomes available, this infrastructure can help the country absorb more imports.
ExxonMobil is also maintaining a diversified LNG portfolio with interests across the United States, Mozambique, Qatar, Papua New Guinea and Australia. Such geographic diversification is increasingly important in a market where geopolitical disruptions can suddenly affect individual supply routes.
Why the LNG Market Could Change Quickly After the War
The current crisis demonstrates how closely LNG demand is linked to price. When prices rise from $10 to nearly $30/MMBtu, some consumers immediately reconsider whether natural gas remains economical.
But the opposite can also happen.
If Middle Eastern supply routes reopen, additional LNG projects begin supplying the market and shipping conditions improve, prices could fall. Consumers that had temporarily switched to coal, oil or other fuels could then return to natural gas.
This creates the possibility of a relatively rapid demand recovery rather than a permanent destruction of LNG consumption.
| Factor | Effect on LNG Demand |
|---|---|
| High LNG prices | Reduces demand and encourages fuel switching |
| Lower global LNG prices | Improves affordability and encourages consumers to return |
| More LNG supply | Reduces competition for cargoes and improves availability |
| Hormuz reopening | Could restore Middle Eastern LNG flows and ease supply pressure |
| Strong electricity demand | Supports gas-fired power generation, especially in China |
| Fuel-switching flexibility | Allows industrial consumers to move between gas and alternative fuels |
LNG Demand Recovery Will Depend on Affordability
The biggest lesson from the current disruption is that gas demand does not depend only on whether consumers need energy. It also depends on whether they can afford LNG compared with alternative fuels.
For industries, the decision is often economic. If LNG becomes substantially more expensive than coal or oil, businesses with flexible equipment may change their fuel mix. If LNG becomes competitive again, gas consumption can recover.
This explains why executives from GAIL, PetroChina and other companies remain relatively optimistic about long-term demand despite the current decline.
Supply Diversification Is Becoming More Important
The crisis is also encouraging LNG buyers to rethink their supply strategies. GAIL and PetroChina are actively searching for alternative cargoes, demonstrating the importance of having access to multiple sources.
For buyers, diversification can reduce the impact of a disruption affecting one geographic region. For sellers, meanwhile, a diversified portfolio can create opportunities to redirect cargoes toward markets experiencing shortages.
The growing importance of LNG trading teams also highlights how the physical gas market is becoming increasingly interconnected. Cargo availability, shipping routes, storage, pricing and geopolitical risk can all influence where LNG ultimately flows.
What Could Happen to LNG Prices Next?
The path of Asian LNG prices will largely depend on how quickly the Middle East supply disruption is resolved and how much new LNG enters the market.
A prolonged disruption would keep prices elevated and could cause further fuel switching in price-sensitive markets. India, Pakistan and parts of China’s power and industrial sectors could remain under pressure in such a scenario.
A faster improvement in shipping conditions could have the opposite effect. Restored Middle Eastern exports would increase available supply, while additional cargoes from other producers could further ease competition.
The $7–$9/MMBtu range identified by PetroChina’s Luo Yizhou provides an indication of the price environment in which China’s gas-fired power demand could become considerably stronger again. It should be viewed as an industry expectation rather than a guaranteed future price.
What to Watch in the Global LNG Market
- Strait of Hormuz: Any improvement in shipping conditions could quickly affect Middle Eastern LNG exports.
- Asian spot prices: A sustained decline from crisis levels would improve demand economics.
- New LNG projects: Additional global supply could ease the current shortage.
- India’s alternative sourcing: Continued diversification will determine how resilient Indian LNG supplies remain.
- China’s power demand: Strong electricity consumption could accelerate gas-fired generation.
- Fuel switching: Industrial users returning from coal or oil to gas would be an early sign of demand recovery.
- Pakistan’s affordability: Lower LNG prices and additional volumes could unlock previously suppressed demand.
Bottom Line
LNG demand in China, India and Pakistan is likely to remain under pressure while prices stay near crisis levels, but industry executives expect consumption to rebound when supply improves and prices become more affordable.
The current decline is largely a response to an extraordinary supply disruption rather than clear evidence that long-term LNG demand has disappeared. Middle Eastern export restrictions have pushed Asian spot LNG prices close to $30/MMBtu, encouraging consumers to switch to coal and oil.
India is already restoring supplies through alternative sourcing, while China has significant potential for renewed gas-fired power demand when LNG prices return toward more normal levels. Pakistan could also see consumption increase as new cargoes become available.
The next phase of the LNG market will therefore depend on two variables: how quickly disrupted supplies return and how much new LNG reaches global markets. If both improve, the current demand weakness across South Asia and China could prove temporary, setting the stage for a significant recovery in Asian LNG consumption.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0