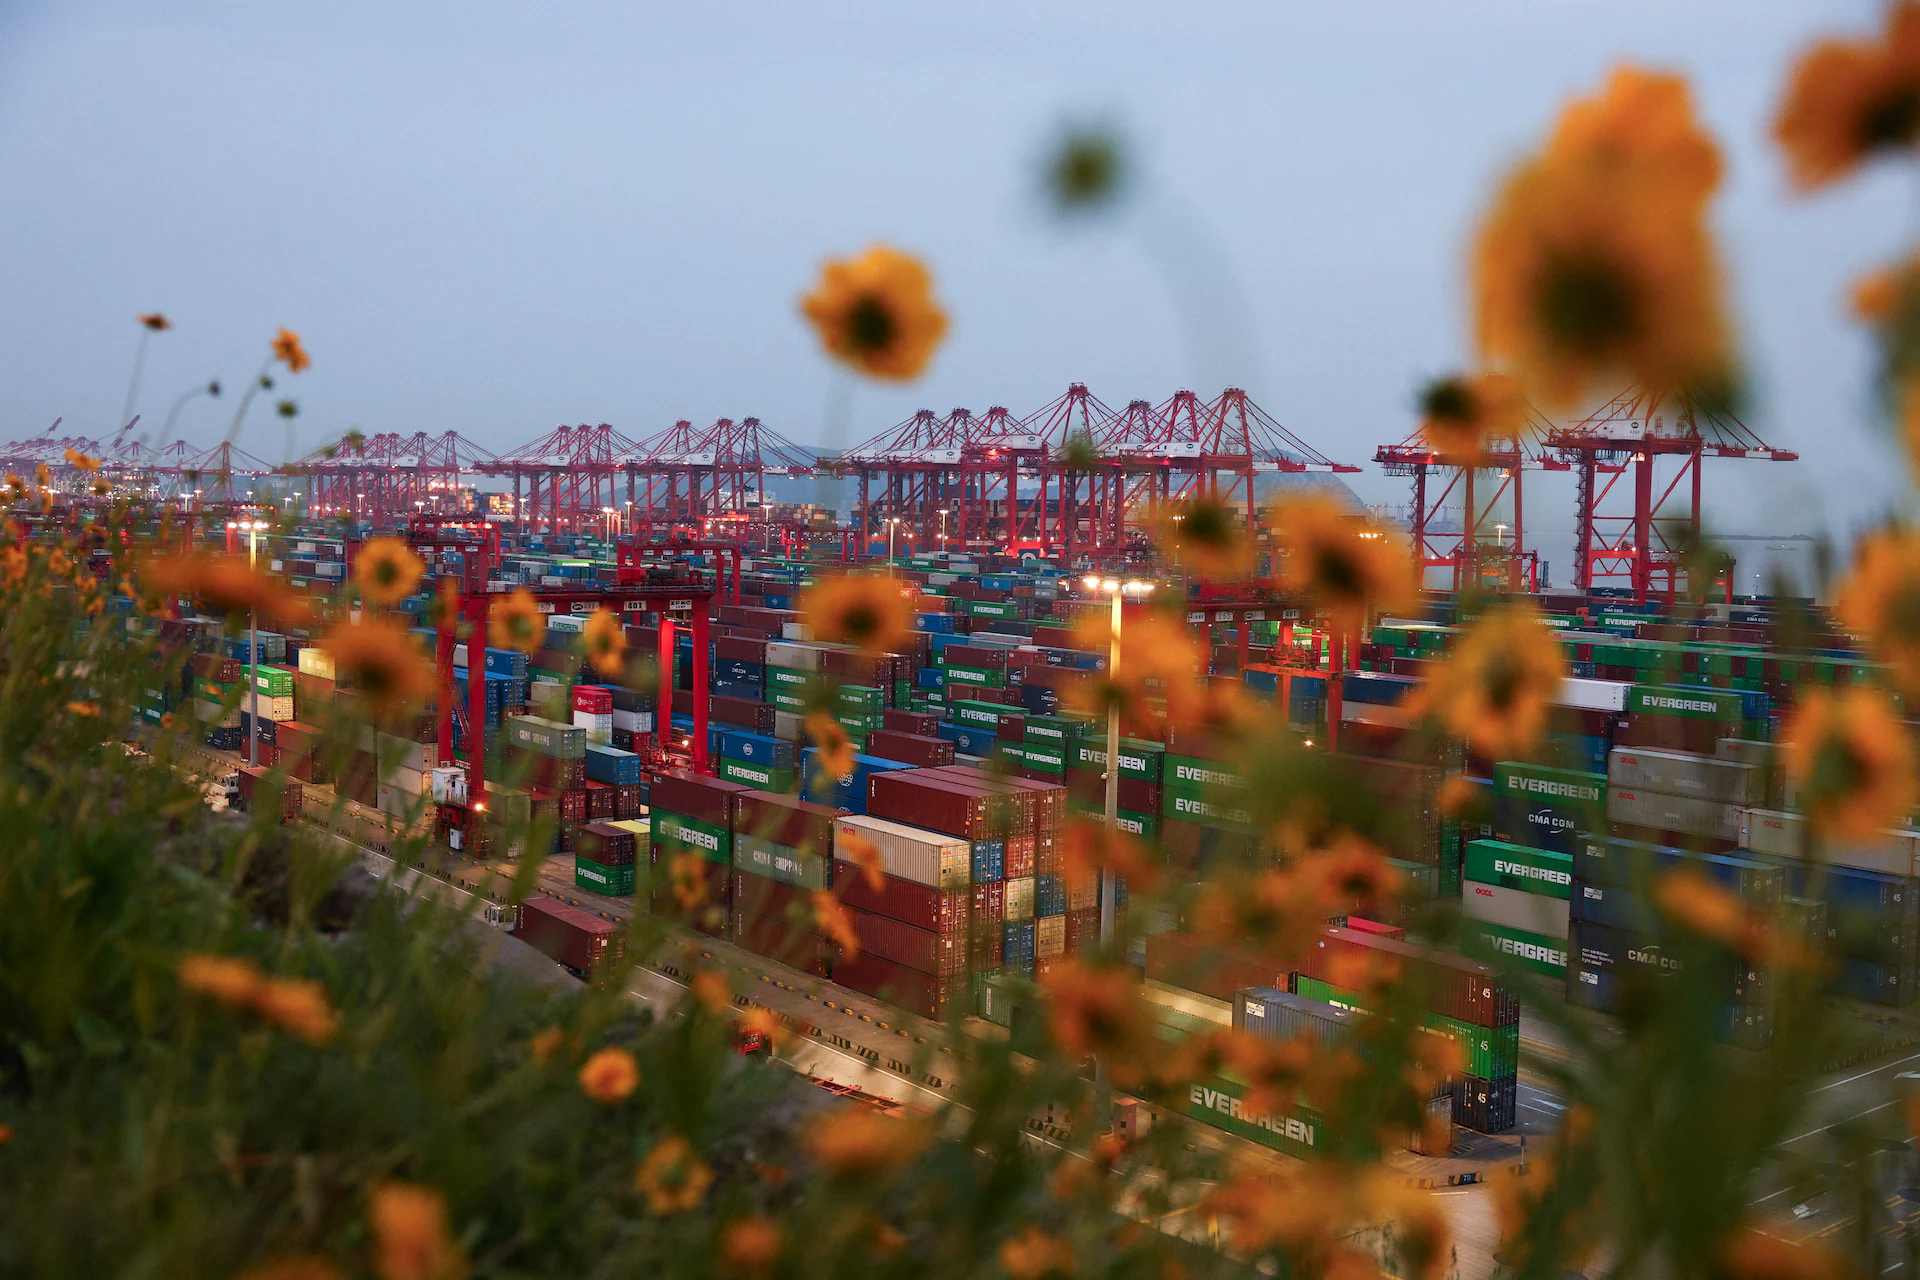
China’s Economic Growth accelerated to 4.5% year-on-year in the third quarter of 2026, beating market expectations and improving from a more than three-year low in the previous quarter. The stronger-than-expected performance could ease immediate pressure on policymakers to introduce more aggressive stimulus measures, although persistent weakness in domestic demand and the property sector continues to cloud the outlook.
Data released by China’s National Bureau of Statistics (NBS) on Monday, October 19, showed that gross domestic product (GDP) grew 4.5% in July-September, compared with 4.3% in the April-June quarter. Economists polled by Reuters had expected third-quarter growth of 4.4%.
The economy also expanded faster on a quarterly basis. GDP rose 1.2% from the previous quarter, exceeding the 1.1% forecast and improving from 0.9% growth in the second quarter.
Other indicators released alongside the GDP figures showed stronger retail sales and continued industrial expansion in September. However, investment in property remained under pressure, highlighting the uneven nature of China’s recovery as policymakers seek to maintain growth while encouraging domestic consumption and stabilising the real estate market.
China GDP Growth Beats Forecasts in Third Quarter
The latest figures suggest that China’s economy gained momentum during the third quarter after slowing to 4.3% growth in the previous three months. The 4.5% expansion exceeded the Reuters poll forecast by 0.1 percentage point, offering some reassurance that economic activity remains resilient despite several structural challenges.
The quarterly growth rate also improved, rising to 1.2% from 0.9% in April-June. This measure compares economic output with the immediately preceding quarter, while the year-on-year figure compares output with the same period a year earlier.
The improvement matters for policymakers because China is targeting annual economic growth of around 4.5% to 5% in 2026, according to the supplied Reuters report. Stronger third-quarter figures bring that objective within reach, although the pace of activity in the final quarter will remain important.
Economists quoted in the report offered different assessments of what the figures mean for policy. Some argued that stronger growth could reduce the need for immediate, broad-based stimulus, while others warned that the economy’s underlying weaknesses remain unresolved.
The headline GDP number alone does not show whether the recovery is becoming self-sustaining. Industrial output and exports have supported activity, but household spending, private investment and the property market continue to present challenges.
September Retail Sales Rise More Than Expected
China’s retail sales grew 1.1% year-on-year in September, outperforming the Reuters forecast of 0.6%. The result also marked an improvement from the 0.4% growth recorded in August.
The stronger reading suggests that consumer spending gained some momentum towards the end of the third quarter. Retail sales are an important indicator of household demand because they track spending across a broad range of consumer goods and related retail activity.
However, the improvement does not necessarily indicate a broad recovery in household consumption. Zhiwei Zhang, chief economist at Pinpoint Asset Management in Hong Kong, said retail sales growth had rebounded slightly but added that real retail sales, after adjusting for inflation, had barely grown compared with a year earlier.
That distinction is important when assessing the strength of domestic demand. Nominal sales growth can be influenced by changes in prices, meaning that an increase in reported spending does not always translate into a comparable rise in the volume of goods purchased.
Weak household demand remains a challenge for China’s economic rebalancing. A more durable recovery would require consumption to make a stronger contribution alongside manufacturing and exports, rather than relying heavily on external demand to support overall activity.
Industrial Output Grows 5.5% in September
China’s industrial output increased 5.5% year-on-year in September, matching the Reuters forecast and improving from 5.2% growth in August.
The data indicate that manufacturing continued to provide support for economic activity. Industrial production has been one of the more resilient parts of China’s economy, supported by exports and investment in advanced manufacturing and technology-related industries.
Andy Ji, an Asian foreign exchange and rates analyst at ITC Markets in Shanghai, pointed to high-tech manufacturing, chip output, new energy vehicles (NEVs) and export delivery values as signs of industrial upgrading.
These areas are important to China’s strategy of strengthening its position in higher-value manufacturing. Semiconductor production, advanced technology and electric vehicles can support exports and help domestic companies compete in international markets.
Nevertheless, industrial strength does not automatically translate into stronger household demand. If factories continue to expand output while consumers remain cautious, the economy can experience an imbalance between production and spending.
This disconnect is one of the central challenges facing Chinese policymakers. Sustaining industrial growth while encouraging household consumption and private-sector investment will be important to the longer-term outlook.
Fixed Asset Investment Remains Weak
Fixed asset investment fell 7.2% year-on-year during the January-September period, according to the NBS figures cited in the Reuters report. The decline was slightly smaller than the 7.3% contraction forecast by economists and matched the decrease recorded during January-August.
Fixed asset investment covers spending on long-term assets, including infrastructure, industrial facilities and property-related development. Its performance offers an indication of how businesses and other investors are committing resources to future productive capacity.
The continued decline suggests that investment remains a weak point in the economy, despite stronger GDP growth and industrial output. Businesses may remain cautious about expanding capacity when domestic demand is uncertain and the property downturn continues to weigh on confidence.
Weak investment can also create challenges for policymakers seeking to support growth without relying excessively on exports or state-led projects. A sustained recovery would require investment to become more broadly supported by credible demand prospects and improved business confidence.
The January-September figure shows that the weakness persisted through the first nine months of the year. Although the result was marginally better than economists expected, it does not yet indicate a turnaround in overall investment activity.
China’s Property Sector Remains Under Pressure
Property investment declined 20.6% year-on-year during January-September, deepening from the 19.9% contraction recorded in January-August.
The continued deterioration highlights the depth of the real estate downturn, which remains one of the biggest obstacles to a more balanced economic recovery. The property sector has broad links to construction, household wealth, building materials and local economic activity.
When property investment falls sharply, the effects can extend beyond developers. Weaker construction activity can affect suppliers and related industries, while uncertainty in the housing market can influence household confidence and spending decisions.
The latest figures suggest that the improvement in headline GDP growth has not been accompanied by a recovery in property investment. The sector’s prolonged weakness continues to complicate efforts to strengthen domestic demand and restore confidence.
Raymond Yeung, chief China economist at ANZ in Hong Kong, said weak domestic demand, persistent deflationary pressure and the ongoing property downturn continued to constrain economic activity.
Property investment’s deeper contraction also reinforces the uneven nature of China’s growth. Manufacturing and exports have supported overall output, but the property sector has yet to show convincing signs of stabilisation in the reported data.
Will China Need More Economic Stimulus?
The stronger-than-expected GDP figures could reduce the immediate pressure on Beijing to announce additional broad-based stimulus measures. However, economists remain divided over whether the improvement is sufficient to justify maintaining the current policy stance.
Zhang of Pinpoint Asset Management noted that growth during the first three quarters combined had reached 4.6%, above the lower end of the government’s growth target range. He questioned whether the latest figures would mean policymakers would not need to make a significant change to their policy stance in the fourth quarter to achieve the annual target.
Ho Woei Chen, an economist at UOB in Singapore, said external demand was still helping sustain the economy. In her assessment, the government was providing targeted support, while broad-based easing appeared less likely because growth remained within the lower part of the forecast range.
Chen’s assessment points to a distinction between measures aimed at specific sectors and a wider stimulus programme designed to boost activity across the economy. Targeted support can address selected areas of weakness, while broad-based easing would represent a more extensive effort to stimulate demand.
Andy Ji also said the stronger GDP and retail sales figures reduced the urgency for immediate, broad-based easing. He noted that the People’s Bank of China had kept its policy rate unchanged since a cut in May 2025 and argued that fiscal policy was the more active area of debate.
The figures do not, however, establish that further support will be unnecessary. Weak domestic consumption, falling property investment and declining fixed asset investment remain significant constraints, while the outlook for exports could become less favourable.
Why Fiscal Policy Could Play a Bigger Role
China’s policy choices are shaped by the need to support growth while addressing weak demand and the prolonged property downturn. The latest figures provide some room for policymakers to maintain their existing stance, but the uneven recovery leaves questions about where additional support might be most effective.
Fiscal measures can support economic activity through public spending and other government-led initiatives. They may also be directed towards specific sectors or areas where policymakers want to encourage investment or consumption.
The supplied Reuters report suggests China is likely to rely more on fiscal stimulus as firmer producer prices and a pickup in consumer inflation limit the scope for aggressive monetary easing.
Monetary policy and fiscal policy work through different channels. Interest-rate changes can influence borrowing costs and financial conditions, while fiscal measures can directly affect spending and investment. The appropriate mix depends on the source of economic weakness and the government’s priorities.
Ji said the active policy debate was focused on fiscal measures, even as monetary policy remained effectively on hold. That assessment reflects the possibility that policymakers may prefer targeted fiscal support over an immediate, broad-based interest-rate response.
Still, the precise scale and timing of any new measures remain uncertain. The third-quarter GDP result provides information about recent economic performance, but it does not confirm what the government will announce in the final quarter.
Exports Continue to Support China’s Economy
Exports have played an important role in sustaining China’s economic growth this year, particularly as manufacturing activity has remained strong. Demand for technology products and components associated with artificial intelligence has provided support for some export industries.
However, the outlook is becoming more complicated. The supplied report identifies a cooling AI investment cycle as a potential risk to demand for technology products and components, which could weaken one of the areas supporting Chinese exports.
China also faces challenges in some vehicle export markets. A deal with the European Union to curb Chinese hybrid-vehicle shipments could weigh on one of the country’s fast-growing export industries, according to the report.
These developments matter because export demand has helped offset weaknesses in other parts of the economy. If overseas demand slows, domestic consumption and investment may need to contribute more to maintain growth momentum.
Yeung of ANZ said exports had provided an important buffer but were unlikely to fully offset softness elsewhere in the economy. He maintained that growth had stabilised but had not yet entered a self-sustaining recovery.
The outlook for exports therefore remains a key uncertainty. China’s manufacturing competitiveness has supported activity, but external demand can be affected by changes in global investment, trade conditions and demand for particular products.
China’s Economic Growth Outlook for 2026 and 2027
The third-quarter figures have improved the near-term picture, but the full-year outcome will depend on how the economy performs in the final three months of 2026.
Ji said the latest results put China’s 4.5%-5% annual growth target within reach, although he added that a strong fourth quarter would still be required. His assessment also highlighted the imbalance between export- and state-led growth and the weaker contribution from domestic demand.
Yeung said ANZ maintained its 2026 GDP growth forecast at 4.6%, while warning that risks remained tilted to the downside. He cited weak domestic demand, deflationary pressure and the property downturn as continuing constraints.
According to the Reuters poll cited in the report, China’s growth is expected to slow to 4.5% in 2026 from 5.0% in 2025, followed by a further moderation to 4.4% in 2027.
These projections point to a gradual slowdown rather than a sudden collapse in growth. However, forecasts remain sensitive to domestic demand, the property market, investment trends and the performance of export industries.
The stronger third-quarter reading is encouraging relative to expectations, but it does not remove the structural challenges identified by economists. Whether China can sustain growth will depend in part on its ability to reduce the gap between resilient production and weaker household spending.
What the Latest GDP Figures Mean for China’s Economy
China’s 4.5% GDP growth in the third quarter shows that economic activity improved from the previous quarter and exceeded market expectations. Stronger retail sales and continued industrial expansion also provided positive signals, while quarterly growth accelerated to 1.2%.
At the same time, falling fixed asset investment and a deeper contraction in property investment reveal that the recovery remains uneven. The economy continues to rely on manufacturing and exports, while household demand and private investment have yet to provide equally strong support.
The figures may give policymakers more flexibility in deciding whether to introduce immediate, broad-based stimulus. But the outlook for exports, the condition of the property sector and the pace of domestic spending will remain important considerations.
The key question is whether China can turn its recent growth performance into a more balanced recovery. Meeting the annual target would mark progress, but a durable improvement would require stronger domestic demand alongside the manufacturing and export activity that has helped sustain growth so far.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest World on thefoxdaily.com.

COMMENTS 0