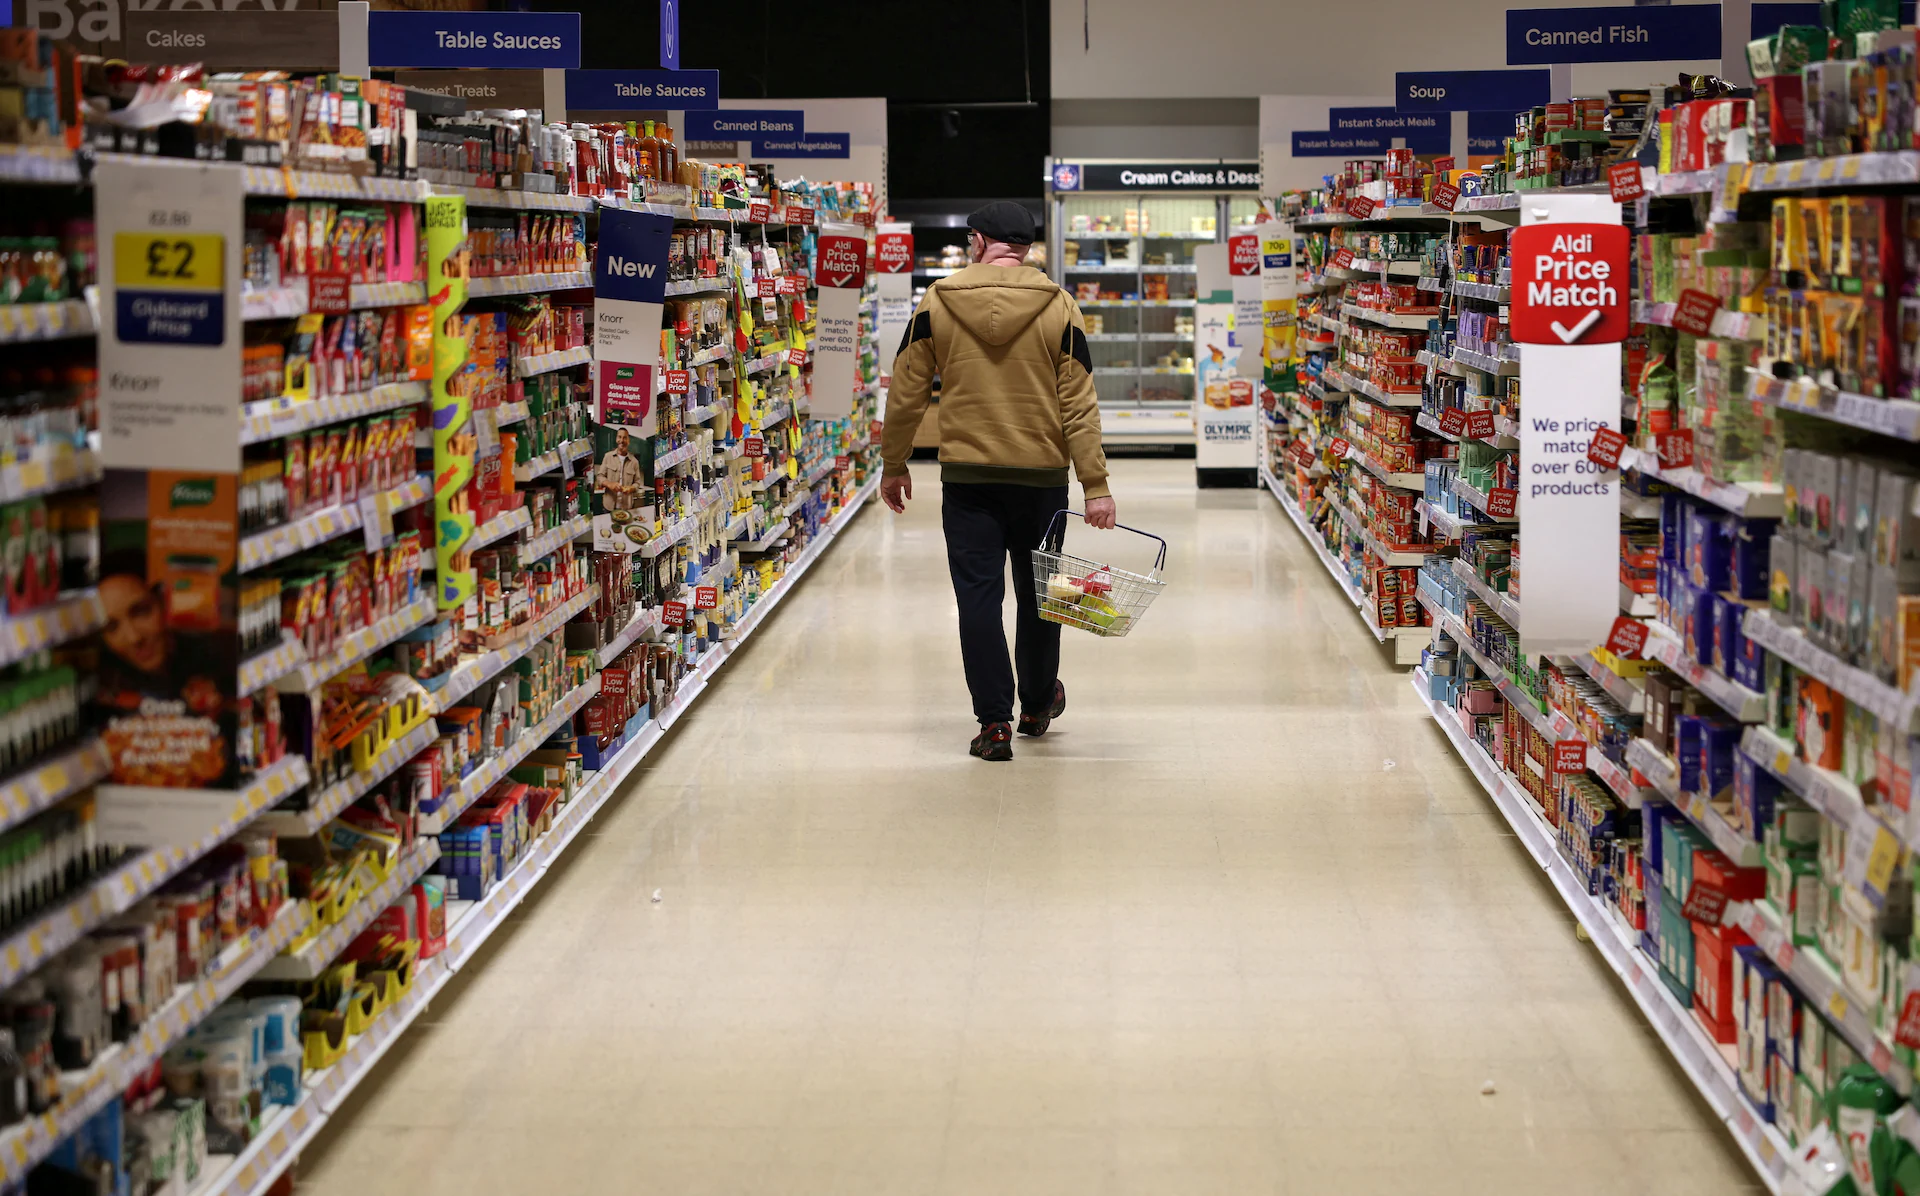
Bank of England policymaker Megan Greene has warned that the risk of a renewed rise in broader Inflation following the energy price shock associated with the Iran war is greater than the central bank had expected. She reiterated her support for higher interest rates, arguing that policymakers should act early to prevent temporary increases in energy costs from becoming a more persistent inflation problem.
Speaking at the London School of Economics on Tuesday, October 20, Greene said the Bank of England should proactively guard against so-called second-round inflation effects. These occur when an initial increase in costs, such as higher energy prices, feeds into wages, business expenses and the prices of other goods and services.
Greene is among the minority of members on the Bank of England’s Monetary Policy Committee who have supported raising borrowing costs. Her position differs from that of Governor Andrew Bailey, who has backed keeping interest rates unchanged while monitoring the economic consequences of the conflict.
The debate has become increasingly important as investors anticipate a possible increase in the Bank of England’s benchmark interest rate next month. According to the supplied Reuters report, financial markets expect a quarter-percentage-point increase that would take Bank Rate to 4%.
The central question for policymakers is whether the energy shock will produce a temporary increase in inflation or trigger a broader cycle of rising prices and wages. Greene believes the risks of the latter outcome are significant enough to justify a more proactive response.
Why Megan Greene believes the Bank of England should raise interest rates
Greene’s argument centres on the possibility that higher energy costs could spread through the British economy rather than remain confined to household fuel bills and other directly affected products.
Energy is an important input for businesses across multiple sectors. When energy prices rise, companies may face higher costs for production, transport, heating and distribution. Depending on market conditions, they may pass some of those increases on to customers.
The inflationary effects can become more persistent if workers also seek higher wages to compensate for increases in living costs. Employers facing higher wage bills may then increase prices further, creating a cycle in which wages and prices reinforce each other.
These indirect effects are known as second-round inflation. They are different from the initial increase in prices caused directly by an energy shock.
Greene said the Bank of England should act on the assumption that these second-round effects could be stronger than expected, while retaining the option to adjust policy later if the risks prove smaller than anticipated.
Her approach reflects a preference for preventing an energy-driven price increase from becoming embedded in the wider economy. If inflation spreads into wage negotiations and businesses’ pricing decisions, bringing it back under control could require a more prolonged period of restrictive monetary policy.
Higher interest rates are intended to reduce demand across the economy by increasing borrowing costs. That can moderate spending and investment, limiting businesses’ ability to raise prices and reducing pressure on inflation over time.
However, monetary policy cannot directly reverse an increase in global energy prices. The challenge is to prevent the initial shock from generating additional inflationary pressures after the original cause has begun to ease.
What are second-round inflation effects?
Second-round effects help explain why central banks sometimes respond to an increase in energy prices even when they cannot influence the original cause of the shock.
Consider a simplified sequence of events:
- Energy prices rise: The initial shock increases costs for households and businesses.
- Businesses adjust prices: Companies facing higher operating expenses may pass some costs on to consumers.
- Workers seek higher pay: Employees may negotiate wage increases to protect their purchasing power as living costs rise.
- Businesses face additional costs: Higher wages can add to production and service expenses.
- Inflation becomes more persistent: Further price increases can occur even beyond the goods and services directly affected by energy costs.
This sequence is not inevitable. Businesses may absorb some costs, wage settlements may remain moderate and weaker consumer demand may limit price increases. The extent of the effect depends on economic conditions and how households, workers and companies respond.
For the Bank of England, the important question is whether the energy shock is beginning to influence inflation expectations and wage-setting behaviour more broadly.
If businesses and workers expect inflation to remain elevated, they may make decisions that contribute to keeping it high. Policymakers must therefore assess not only current inflation but also the risk that temporary pressures will persist.
Greene’s position is that the central bank should not wait until those effects become fully visible before responding. She favours leaning against the risk early, with the possibility of changing course if subsequent evidence shows that inflationary pressures are weaker than anticipated.
Greene questions whether current monetary policy is restrictive enough
Greene also pointed to signs of resilience in Britain’s economy during the year, despite the increase in energy prices. She argued that the available economic evidence did not clearly demonstrate that monetary policy was exerting a sufficiently strong restraint on demand.
“It is not obvious to me from this data that our monetary policy stance is meaningfully restrictive,” Greene said during her speech.
The distinction matters because interest rates are intended to influence inflation partly by making borrowing more expensive and encouraging households and businesses to moderate spending.
If economic activity remains resilient, demand may continue to support price increases even as energy costs rise. Greene’s assessment suggests she sees the economy’s resilience as an additional reason to consider higher borrowing costs rather than assume that existing monetary conditions will automatically contain inflation.
Her argument does not establish that a rate increase is certain to be necessary. Instead, it reflects her interpretation of the available evidence and the risks facing the economy.
Other policymakers may place greater weight on the possibility that higher interest rates could weaken economic activity without substantially reducing the direct cost of energy. This creates a difficult trade-off between limiting inflation and avoiding an unnecessary slowdown.
Why wage growth and 2027 pay settlements matter
Greene expressed concern that wage growth in Britain was running higher than official data had suggested. She also warned that pay settlements due in early 2027 could be stronger than previously anticipated.
Her concern is linked to the possibility that inflation will be running at around 4% by that time. If workers expect living costs to continue rising, they may seek larger pay increases to preserve their purchasing power.
Wage growth is an important indicator for central banks because it can influence both household spending and the cost of providing goods and services.
Higher wages can support consumer demand, particularly when workers have more money available to spend. But wage increases can also raise business costs, especially in labour-intensive sectors. If companies respond by increasing prices, wage growth may contribute to persistent inflation.
The relationship is not automatic. Productivity improvements can help businesses accommodate higher wages without increasing prices, while weaker demand may limit their ability to pass on additional costs.
Nevertheless, Greene’s warning suggests she believes wage-setting decisions in early 2027 could become an important test of whether the energy shock is spreading through the economy.
For policymakers, the timing creates a challenge. Interest-rate decisions made now influence economic conditions over time, so the Monetary Policy Committee must consider where inflation may be heading rather than respond only to the latest available figures.
How the Iran war’s energy shock complicates the Bank of England’s decisions
The energy price shock associated with the Iran war has introduced another source of uncertainty for British monetary policy. Higher energy costs can put upward pressure on inflation while also reducing the amount of money households have available for other purchases.
For households, increased spending on energy can leave less room in budgets for food, transport, leisure and other expenses. Businesses can face a similar squeeze when higher energy bills reduce the money available for investment or expansion.
This creates a complicated policy problem. Higher interest rates may help contain broader inflation, but they can also increase mortgage payments and borrowing costs for households and companies with loans tied to variable rates or refinancing arrangements.
Meanwhile, keeping interest rates unchanged may provide some relief to borrowers but could leave the central bank exposed if higher energy costs feed into wages and wider prices.
The effect of the energy shock also depends on how long the disruption lasts. A short-lived increase may produce a temporary inflation spike, while a prolonged period of higher energy costs could have more lasting consequences for household finances and business decisions.
Greene’s warning reflects the possibility that the inflationary consequences may be greater than the Bank of England initially anticipated. Her position is that policymakers should prepare for a stronger effect rather than assume the shock will fade without further action.
Andrew Bailey and Megan Greene differ over the interest-rate outlook
Greene’s comments highlight a difference in emphasis within the Bank of England’s Monetary Policy Committee. While she has supported higher rates, Governor Andrew Bailey has backed holding borrowing costs steady as the central bank assesses the consequences of the energy shock.
Bailey has said that the longer the conflict continues, the more difficult it could become for the Bank of England to avoid responding. At the same time, he has described inflationary pressures as “quite subdued”.
The difference between the two positions reflects uncertainty about the balance of risks. Greene is concerned that inflation could spread through wages and prices more forcefully than expected. Bailey’s comments suggest a more cautious approach while the central bank evaluates how the shock develops.
Neither position eliminates the possibility of a change in policy. The eventual decision will depend on how the evidence develops, including the behaviour of wages, inflation expectations, energy prices and economic activity.
The Monetary Policy Committee must also consider the timing of any response. Raising rates too late could allow inflation to become more persistent, while tightening too aggressively could weaken demand when households and businesses are already dealing with higher energy costs.
The disagreement therefore reflects a broader challenge for central banks: deciding how much weight to place on inflation risks that have not yet fully materialised.
Markets expect Bank of England interest rates to reach 4%
Investors expect the Bank of England to raise its benchmark Bank Rate by a quarter of a percentage point to 4% next month, according to the supplied Reuters report.
Market expectations are not a final decision by the central bank. The Monetary Policy Committee will determine its position based on its assessment of the economic outlook and inflation risks.
A quarter-percentage-point increase would represent a measured tightening of monetary policy. Its purpose would be to make borrowing somewhat more expensive and help restrain demand, supporting efforts to prevent inflation from becoming entrenched.
For borrowers, a rate increase could mean higher costs on some variable-rate loans and mortgages, depending on the terms of their agreements. Businesses could also face more expensive financing, potentially affecting investment decisions.
Savers may benefit from higher interest rates if banks pass on some of the increase to deposit accounts, although the effect varies between providers and products.
For households already facing higher energy bills, the combination of elevated living costs and borrowing expenses could place additional pressure on budgets. The effects would not be uniform, as they would depend on individual financial circumstances and exposure to interest-rate changes.
What to watch before the next Bank of England decision
The next interest-rate decision will depend on whether policymakers see stronger evidence that inflation risks are spreading beyond energy prices.
Several indicators are likely to be important to the debate:
- Wage growth: Whether pay increases remain elevated and support Greene’s concern that official data may understate underlying pressures.
- Pay settlements: Whether employers and workers agree to wage increases that could influence inflation in early 2027.
- Energy prices: Whether the shock associated with the Iran war persists or begins to ease.
- Economic resilience: Whether spending and business activity remain strong enough to sustain broader price pressures.
- Inflation expectations: Whether households and businesses expect higher inflation to continue influencing wages and prices.
These factors will help the Monetary Policy Committee judge whether higher interest rates are necessary to prevent a temporary shock from becoming a lasting inflation problem.
Greene’s intervention makes clear that she believes the risks warrant a proactive response. Bailey’s more cautious position indicates that the central bank is still weighing the evidence rather than treating an increase as inevitable.
The central issue is whether the energy shock will remain a relatively contained increase in costs or spread through the wider economy. If wage growth and price-setting behaviour strengthen, the case for tighter monetary policy could become more compelling. If those effects remain limited, policymakers may have more room to avoid further increases in borrowing costs.
For British households, businesses and financial markets, the outcome will influence borrowing conditions and the path of inflation in the months ahead. The next decision will ultimately depend on the evidence available to the Bank of England and how policymakers assess the risk that the Iran war’s energy shock could leave a more persistent mark on the British economy.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest World on thefoxdaily.com.

COMMENTS 0