The Indian government is considering changes to long-term capital gains (LTCG) taxation ahead of the Union Budget 2027-28, including a possible reduction in the current 12.5% tax rate and allowing foreign investors to calculate taxable capital gains in dollar terms rather than rupees. The proposals are aimed at improving investor sentiment, attracting foreign capital and addressing concerns about the performance of India’s stock markets.
Government officials are discussing several options as domestic investors contend with weak stock market returns and limited wage growth. Policymakers are also examining concerns that Foreign Portfolio Investors (FPIs) may find India’s capital gains tax structure less attractive than the arrangements available in some competing markets.
However, the proposals remain under discussion. No final decision has been announced on reducing the LTCG tax rate or changing the way foreign investors calculate their taxable gains.
Why the Government Is Considering Capital Gains Tax Changes
Two major concerns are driving the debate ahead of Budget 2027-28. The first is the effect of weak stock market performance on household finances and investor confidence. The second is the growing uncertainty over whether domestic institutional investment can consistently offset large-scale withdrawals by foreign investors.
Officials are concerned that stagnant or negative stock market returns over an extended period, combined with weak wage growth, could further dampen consumer and investor sentiment. The impact is particularly significant because retail participation in Indian equity markets increased substantially after the Covid-19 pandemic.
For many households, investments in shares and mutual funds have become a way to diversify savings and supplement regular income. When markets fail to deliver satisfactory returns, investors may become more cautious about committing additional money to equities.
The government is therefore examining whether changes to capital gains taxation could make equity investments more attractive. A lower tax rate could increase the share of investment profits retained by investors, although its overall impact would depend on market conditions, investor behaviour and the government’s final policy design.
Retail Participation in Indian Stock Markets Has Expanded
Retail investors have become a more prominent part of India’s equity market since 2020. Data sourced from Prime Infobase show that retail shareholding in companies listed on the National Stock Exchange increased significantly during the post-pandemic market expansion before declining in the period leading up to March 2026.
In March 2020, retail investors held 6.58% of shares in NSE-listed companies, with the value of their holdings estimated at Rs 7.23 lakh crore. Their share rose to 7.66% in June 2024, when the value of their holdings reached Rs 33.16 lakh crore.
By March 2026, retail shareholding had declined to 7.12%, with holdings valued at Rs 28.97 lakh crore. The figures indicate that retail investors’ share of the market and the value of their investments have fluctuated alongside changing market conditions.
The number of demat accounts has also increased dramatically. Data cited in the report show that accounts with the Central Depository Services (India) Limited (CDSL) reached 19.34 crore in September 2026, compared with 2.12 crore in March 2020.
The growth in demat accounts reflects the wider availability of digital investment platforms and the expansion of participation in securities markets. However, the number of accounts does not necessarily represent the number of unique active investors, as individuals may hold multiple accounts.
With more households exposed to equity market movements, prolonged periods of weak returns can have wider implications for financial confidence. This is one reason the government is examining possible changes to the tax treatment of capital gains.
Foreign Investors Raise Concerns Over the 12.5% LTCG Tax
Long-term capital gains on relevant equity investments are currently subject to a 12.5% tax rate under the framework described in the report. Some global investors consider this rate relatively high compared with the treatment of capital gains in other markets.
The report notes that countries such as China, Indonesia and Brazil have either no capital gains tax in certain circumstances or comparatively limited levies. However, tax systems differ across jurisdictions, including in their treatment of asset classes, holding periods, investor categories and exemptions. Direct comparisons therefore require consideration of the specific rules applicable to each investment.
Foreign investors have also raised concerns about having to calculate gains in rupees. Changes in the rupee-dollar exchange rate can affect the value of an investment when measured in a foreign investor’s home currency.
For example, an overseas investor may sell an Indian asset for more rupees than originally invested but receive a smaller return in dollar terms if the rupee has depreciated during the holding period. Depending on the exchange rate movements, the investor could even record a dollar-denominated loss despite reporting a gain in rupees.
Under the current approach described in the report, the tax calculation for many relevant investments is based on gains measured in rupees. Foreign investors argue that this can result in tax being payable even when currency movements have reduced or eliminated their gains in dollar terms.
Allowing eligible foreign investors to calculate capital gains in dollars could address some of these concerns. However, the proposal would require clear rules on exchange rates, eligible investors, acquisition and sale dates, allowable costs and the treatment of foreign-exchange losses.
What the Income-tax Act Says About Foreign Currency Conversion
The Income-tax Act, 2025, includes provisions governing the computation of capital gains. Section 72 addresses the mode of computation, including the calculation of gains after deducting eligible transfer expenses, acquisition costs and improvement costs from the consideration received for a capital asset.
The report highlights Section 72(6), which provides foreign currency conversion relief to certain non-residents transferring shares or debentures of unlisted Indian companies. The provision is intended to prevent notional gains arising from rupee depreciation from being treated as taxable gains in the circumstances covered by the law.
However, the relief described in the report is limited to specified transactions involving unlisted Indian company shares or debentures. It does not provide the same treatment to domestic investors or foreign portfolio investors in the broader equity market.
The proposed dollar-based approach would therefore raise questions about the scope of existing relief and whether similar treatment should be extended to other categories of investors. Any change would need to specify the types of assets and investors covered and how the calculation would operate in practice.
Such a reform could make the tax treatment more closely reflect returns measured in an overseas investor’s base currency. At the same time, policymakers would need to consider administrative complexity, potential revenue implications and whether different investor categories should receive different treatment.
Domestic Mutual Funds Can No Longer Be Assumed to Offset FPI Outflows
Another concern for policymakers is the changing relationship between domestic investment flows and foreign portfolio investment. For much of the period leading up to 2024, domestic funds often purchased shares when foreign investors were selling, helping to absorb some of the pressure created by overseas withdrawals.
That pattern strengthened the belief that domestic mutual fund inflows could provide a degree of stability to Indian equity markets even during periods of foreign selling. However, confidence in this offsetting effect has weakened as questions have emerged about the sustainability of foreign investment and the strength of domestic market sentiment.
Foreign portfolio investors can move substantial amounts of capital across countries in response to changing valuations, interest rates, currency expectations and economic conditions. When they withdraw money from a market, domestic institutions may not always have the resources or willingness to absorb the entire amount being sold.
Domestic mutual fund inflows remain an important source of investment demand, but their effect depends on the scale and timing of foreign flows and the broader condition of the market. Policymakers are therefore examining whether tax changes could help improve India’s attractiveness to international investors.
Global Interest Rates and Technology Concerns Affect Foreign Investment
Capital gains taxation is only one factor influencing overseas investment decisions. The report identifies several other concerns that may be holding back large-scale FPI inflows, including the lack of a strong artificial intelligence investment theme, perceptions that some stocks remain expensive despite market corrections, and rising interest rates in developed economies.
Higher interest rates in major developed markets can make bonds and other relatively lower-risk assets more attractive compared with equities in emerging economies. Investors may also demand greater compensation for taking currency, market and policy risks when allocating money internationally.
Stock valuations are another consideration. If investors believe share prices remain high relative to expected earnings, they may delay new investments or reduce their exposure, even after a market correction.
The report also points to the growing importance of artificial intelligence in shaping expectations about future productivity, corporate profitability and technological leadership. Countries and companies perceived to be well positioned to benefit from AI development may attract a greater share of international investment.
In this environment, the government faces the challenge of improving India’s appeal to foreign investors without relying on tax incentives alone. Predictable regulation, credible growth prospects and competitive opportunities in emerging technologies can also influence where international capital is deployed.
Government Reviewing Options Ahead of Budget 2027-28
A senior government official said the government was discussing every option when asked whether measures to support stock markets could include reducing or removing capital gains tax.
The statement indicates that the issue is being considered as part of the policy discussions ahead of the next Union Budget. However, it does not establish that the government has decided to cut the tax rate or eliminate the levy.
A reduction in LTCG tax could improve post-tax returns for investors, while a dollar-based calculation for foreign investors could address concerns about currency depreciation. The two measures would have different implications and could be implemented separately, depending on the government’s assessment.
Policymakers would also need to weigh the potential benefits against the loss of tax revenue and the risk that tax changes may not produce a sustained increase in investment. Market performance depends on several factors, including corporate earnings, economic growth, valuations, liquidity and global financial conditions.
The final approach may therefore involve a broader assessment of the tax treatment of financial assets and the factors influencing investment flows, rather than a decision based exclusively on the headline capital gains tax rate.
Government Previously Removed Taxes on Certain Government Bond Investments
The government has already taken steps to attract overseas investment into India’s government bond market. According to the report, on June 5 it removed withholding tax as well as long-term and short-term capital gains tax on foreign investors’ investments in government bonds.
Before the change, foreign investors faced a 12.5% tax on long-term capital gains, a 30% tax on short-term capital gains and withholding tax of around 20% on interest income from their government bond holdings, as described in the report.
The move was intended to make government securities more attractive to overseas investors by reducing the tax burden associated with these investments. It also provides context for the current debate over whether the tax treatment of equity investments should be reviewed.
Government bonds and equities serve different purposes in investment portfolios. Bonds generally provide contractual interest payments and repayment terms, while equities expose investors to changes in company valuations and business performance. Tax changes that encourage investment in one asset class may not have the same effect on another.
The current discussions suggest that policymakers are considering how the wider tax framework affects India’s ability to attract international capital across different segments of its financial markets.
SBI Research Recommends Abolishing LTCG Tax on Equities
The State Bank of India has also weighed in on the debate. In its Ecowrap research report dated October 12, SBI said the government should seriously consider ways to anchor short-term or volatile capital flows in the equity market.
The report suggested extending the holding period for investments to two or three years and abolishing long-term capital gains tax on equities. Such a change, if adopted, would represent a significant shift in the tax treatment of equity investments.
SBI’s recommendation reflects the view that tax policy could influence investor behaviour and the duration for which capital remains invested. A longer holding period could potentially encourage a greater focus on medium- and long-term investment, although the effect would depend on the design of the rules and how investors respond.
Abolishing LTCG tax could increase post-tax returns on qualifying investments, but it would also have implications for government revenue. The government would need to assess whether the expected benefits for investment flows and market participation justified the fiscal cost.
The SBI report also emphasised the importance of India’s position in the global competition for artificial intelligence investment. It argued that regulatory certainty and a clear policy vision would become increasingly important as international investors evaluate opportunities linked to the next wave of technological growth.
Finance Minister Says Debate on Capital Gains Tax Is Healthy
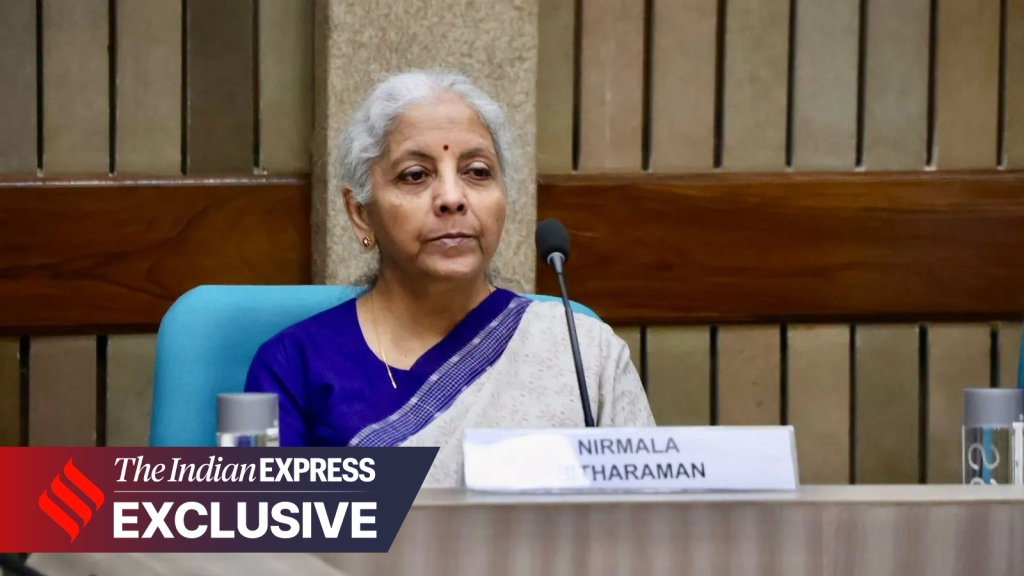
Finance Minister Nirmala Sitharaman has previously acknowledged the debate over long-term capital gains tax, describing it as healthy and expressing interest in hearing different views.
Speaking at the Bloomberg New Economy event earlier in October, Sitharaman said domestic and foreign investors had raised questions about LTCG tax and the Securities Transaction Tax (STT). She noted that the taxation of market investments and the treatment of different asset classes had been widely discussed.
The comments indicate that the issue has attracted attention from market participants and policymakers. However, acknowledging the debate does not amount to a commitment to reduce or abolish the tax.
The Securities Transaction Tax is levied on specified securities transactions, while capital gains tax applies to qualifying profits from the transfer of assets. The two taxes operate differently, and changes to either would have distinct implications for investors and government revenues.
Investors evaluating the potential reforms will be watching for details on whether the government proposes a lower LTCG rate, a broader exemption, a change in holding-period rules or a different calculation method for foreign investors.
Artificial Intelligence Emerges as a Factor in India’s Investment Strategy
The SBI Ecowrap report argues that recurring episodes of capital outflows should prompt a broader examination of how India positions itself for the next phase of global investment.
Soumya Kanti Ghosh, SBI’s Group Chief Economic Adviser, said artificial intelligence was increasingly influencing expectations about productivity, profitability and technological leadership. The report argued that policy certainty would be important as countries compete to attract investment linked to AI development.
AI-related investment depends on more than tax incentives. Investors also assess access to computing infrastructure, reliable electricity, skilled workers, regulatory clarity and the potential for businesses to turn new technologies into profitable products and services.
India’s ability to attract capital in this area may therefore depend on how effectively it combines a predictable policy environment with the infrastructure and workforce required to support technology development.
The report’s emphasis on AI adds another dimension to the capital gains tax debate. While lower taxes could improve the financial appeal of some investments, international investors also compare the long-term growth opportunities available across markets.
What a Capital Gains Tax Cut Could Mean for Investors
A reduction in the LTCG tax rate could increase the post-tax returns investors retain when they sell qualifying assets at a profit. It could also influence decisions about portfolio allocation and the timing of asset sales.
For domestic retail investors, any change would need to be assessed in the context of the applicable holding periods, exemptions and other tax rules. A lower headline rate would not necessarily guarantee stronger stock market performance, because share prices also depend on corporate earnings, economic conditions and investor expectations.
For foreign investors, dollar-based taxation could make the tax calculation more closely reflect gains or losses measured in their base currency. Such a system could address one concern about the current treatment of rupee-denominated investments, but its effectiveness would depend on the precise rules and the broader investment environment.
There are also trade-offs. Reducing or abolishing capital gains tax could lower government revenue, while a more complex currency-based calculation could increase compliance requirements unless the rules are clearly defined.
Any reform would therefore need to balance investor confidence, tax administration, fiscal considerations and the objective of encouraging stable long-term investment.
Budget 2027-28: Key Decisions to Watch
The capital gains tax debate is emerging as an important issue ahead of Budget 2027-28, with the government facing pressure to improve investor sentiment and strengthen India’s position in global capital markets.
The options under discussion include lowering the current 12.5% LTCG tax rate, allowing eligible foreign investors to calculate capital gains in dollar terms and reconsidering the holding-period requirements for equity investments. SBI has separately recommended abolishing LTCG tax on equities and extending the holding period to two or three years.
For now, these proposals remain part of the wider policy debate rather than confirmed changes. The government will need to consider their likely impact on market participation, foreign investment, tax revenue and long-term capital formation before deciding whether to include any measures in the Budget.
The outcome will be important for retail investors, domestic funds and foreign portfolio investors alike. Beyond taxation, the ability to attract sustainable investment will also depend on market valuations, corporate performance, global financial conditions and India’s capacity to offer credible growth opportunities in sectors such as artificial intelligence.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0