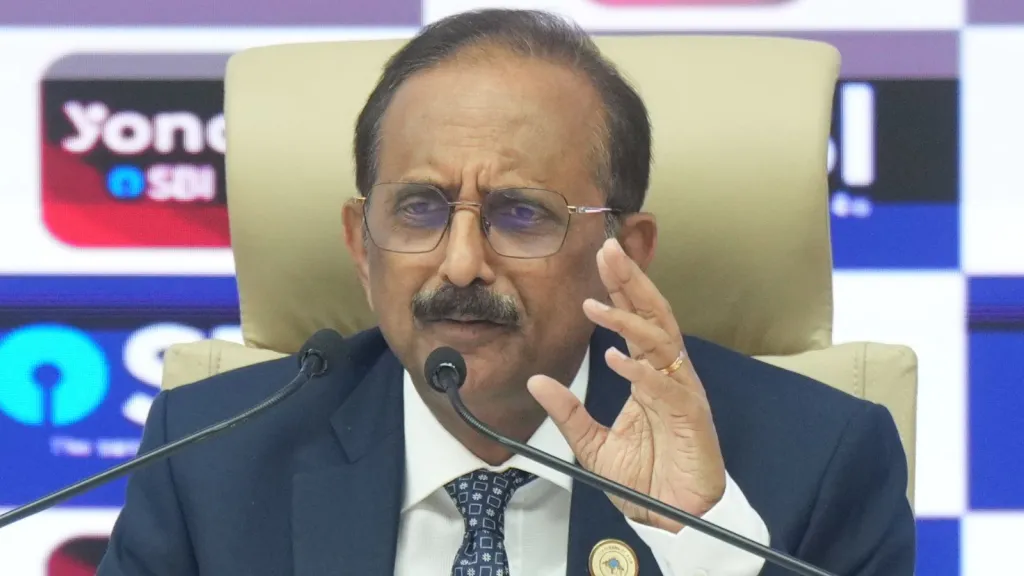
State Bank of India (SBI) reported double-digit growth in both net profit and net interest income during the July-September quarter, supported by strong loan growth and an improvement in its net interest margin. The country’s largest bank by asset size posted record quarterly figures, broadly exceeding the consensus estimates of most analysts.
SBI recorded a net profit of Rs 23,038 crore in the second quarter, marking an increase of more than 14% year-on-year. Net interest income (NII), which represents the difference between interest earned on loans and investments and the interest paid on deposits and borrowings, rose nearly 15% to Rs 49,143 crore.
The results highlighted the strength of the bank’s lending business and its ability to maintain margins above the 3% level. However, weaker treasury performance, higher expenses and slower operating profit growth affected the overall picture. The bank also faces questions about cybersecurity following a data breach reported last month.
SBI Q2 Results: Treasury Losses Weigh on Other Income
Despite divesting its stake in SBI Funds Management during the quarter, the bank’s other income declined on both a year-on-year and sequential basis. Losses from treasury operations, linked to higher bond yields, contributed to the decline.
Higher bond yields can reduce the market value of existing fixed-income securities. When these securities are marked to market, banks may have to recognise valuation losses, affecting their treasury income and overall profitability.
Explaining the impact, Anindya Paul, Deputy Managing Director of Finance at SBI, said the bank recorded mark-to-market devaluation and foreign exchange losses of nearly Rs 1,300 crore during the quarter. This compared with gains of around Rs 2,900 crore in the corresponding quarter of the previous year.
Paul attributed the difference to movements in yields, which affected the bank’s treasury performance. The losses illustrate how changes in interest rates and currency markets can influence a bank’s non-interest income, even when its core lending business is performing well.
SBI Chairman CS Setty said the Banking Sector continued to benefit from healthy credit demand, supported by strong capital positions and improving asset-quality indicators. He also expressed optimism about India’s medium-term growth prospects, while emphasising the need for banks to balance expansion with disciplined management of liquidity, funding, risk and capital.
Loan Growth Nears 18% as SBI Maintains Guidance
SBI’s loan portfolio expanded by nearly 18% year-on-year during the July-September quarter. Deposit growth was comparatively slower but remained in double digits, exceeding 12%.
The gap between loan and deposit growth is an important factor for banks because lending expansion needs to be supported by adequate and stable funding. Strong credit demand can improve interest income, but banks must also ensure that they have sufficient deposits and liquidity to support their growing loan books.
Despite the stronger-than-expected loan growth in the quarter, SBI retained its loan growth guidance of 14-15%. The bank explained that the exceptional growth during the reporting period was partly supported by funds raised through the Foreign Currency Non-Resident Bank (FCNR-B) deposit window.
SBI raised approximately $10 billion through FCNR-B deposits, with the window remaining open until the end of August. These deposits provided additional resources to support lending activity during the quarter.
FCNR-B Deposits and Currency Hedging Restrictions
Setty explained that restrictions imposed by the Reserve Bank of India (RBI) on hedging FCNR-B deposits meant that only a portion of the funds raised had been hedged. He added that most of these deposits had an average tenure of five years.
Under the RBI’s current guidelines, banks are permitted to hedge only the principal amount raised through the FCNR-B window. The interest component remains uncovered, leaving banks with a degree of exposure to foreign exchange movements.
The funding arrangement helped SBI support its credit expansion, but the bank must also manage the associated currency and liquidity risks. The distinction between principal and interest hedging is particularly relevant for deposits with longer maturities, as exchange-rate movements can affect the cost of foreign-currency funding.
Net Interest Margin Improves to 3.11%
SBI’s net interest margin (NIM) increased by three basis points to 3.11% during the quarter. The improvement kept the bank above its stated objective of maintaining NIM above the 3% mark.
NIM measures the difference between the interest income generated by a bank’s assets and the interest it pays on its liabilities, relative to its interest-earning assets. It is a key indicator of the profitability of a bank’s core lending and investment activities.
A higher NIM can support earnings by allowing a bank to generate more income from its interest-earning assets. However, maintaining margins depends on several factors, including lending rates, deposit costs, the composition of the loan book and changes in market interest rates.
For SBI, the improvement in NIM, combined with nearly 18% loan growth, helped drive the increase in net interest income. The bank’s ability to keep margins above 3% will remain an important factor in its performance over the coming quarters.
SBI Asset Quality Improves Further
The bank also reported an improvement in asset quality during the quarter. Both gross non-performing asset (GNPA) and net non-performing asset (NNPA) ratios declined.
Non-performing assets are loans on which borrowers have stopped making scheduled repayments for a specified period. The gross NPA ratio reflects the proportion of total advances classified as non-performing before accounting for provisions, while the net NPA ratio reflects the position after provisions.
Lower NPA ratios can reduce pressure on a bank’s balance sheet and limit the need for additional provisions against stressed loans. For a lender expanding its loan book, maintaining asset quality is essential to ensuring that faster credit growth translates into sustainable earnings.
SBI’s combination of stronger lending, improved margins and declining NPA ratios provided support to its Quarterly Results. Nevertheless, the impact of treasury losses and higher operating expenses showed that headline profit growth does not necessarily translate into equally strong growth across all operating measures.
SBI Shares Fall 1.7% After Quarterly Results
Despite reporting double-digit growth in net profit and net interest income, SBI shares ended 1.7% lower on Tuesday. The stock had traded more than 1% higher earlier in the day before reversing its gains following the earnings announcement.
Market reaction appeared to reflect concerns about the bank’s operating performance, particularly its operating profit growth. Operating profit increased by only 7% year-on-year, a slower pace than the growth recorded in net profit and net interest income.
Higher expenses and weaker treasury performance put pressure on the operating numbers. The treasury losses were particularly significant because the bank had benefited from gains in the corresponding period last year.
The difference between net profit growth and operating profit growth is important when assessing the sustainability of earnings. While net profit increased by more than 14%, the slower expansion in operating profit suggests that cost pressures and non-core income movements influenced the quarterly outcome.
Investors will therefore be watching whether SBI can maintain its loan growth momentum, protect its margins and manage operating expenses while improving the contribution from its core banking operations.
SBI Steps Up Cybersecurity Measures After Data Breach
Alongside its financial performance, cybersecurity emerged as a key issue during SBI’s post-results interaction. The bank is conducting a root cause analysis of the data breach reported last month and has started measures to contain the incident and identify the vulnerabilities that may have contributed to it.
Chairman CS Setty said the investigation was still underway and would take some time to complete. He explained that the bank’s immediate priorities included containment, identifying the weaknesses that led to the breach and implementing corrective measures.
SBI has also conducted a cybersecurity exercise involving an application programming interface (API) sweep and vulnerability assessments. APIs allow different software systems and applications to communicate with each other. They are widely used in digital banking services, making their security an important part of protecting customer information and financial systems.
The bank’s review is intended to identify potential weaknesses across its digital infrastructure and strengthen its ability to prevent similar incidents in the future.
Customer Information and System Security Remain Priorities
Setty emphasised that protecting the bank’s systems and customer information was a priority. He said the incident had reinforced SBI’s focus on strengthening its cybersecurity arrangements.
He also rejected concerns that funding constraints could limit the bank’s ability to invest in digital security. According to the chairman, SBI had never faced a shortage of funds for technology and digital solutions.
The comments underline the growing importance of cybersecurity investment as banks expand digital services. Mobile banking, internet banking, payment systems and interconnected financial platforms have increased convenience for customers, but they have also expanded the number of digital entry points that need protection.
Rising Digitalisation Expands the Banking Sector’s Cyber Risk
Setty described cyberattacks across the banking system as a serious concern, noting that increasing digitalisation was expanding the sector’s attack surface area. In cybersecurity, the term refers to the collection of systems, applications, devices and access points that could potentially be targeted by attackers.
As banks introduce more digital products and connect additional systems, the number of potential vulnerabilities can also increase. Security risks are no longer limited to a bank’s internal infrastructure; they can involve APIs, third-party service providers, customer-facing applications and other connected platforms.
This makes cybersecurity a shared concern across the financial system. A weakness in one institution or service provider can create risks beyond the organisation directly affected, particularly when financial institutions rely on interconnected technology and payment networks.
SBI Chairman Calls for Faster Information Sharing
Setty said information about cyber incidents was shared with regulators and security agencies. However, he also highlighted the potential value of a structured mechanism for sharing information among banks and other financial institutions immediately after an incident occurs.
According to the chairman, faster and more organised communication could help other institutions take preventive measures without delay. Early warnings about newly identified vulnerabilities, attack methods or compromised systems could allow banks to review their own security arrangements and reduce the risk of similar incidents.
Such coordination is particularly relevant as financial institutions increasingly depend on digital infrastructure and interconnected services. A structured information-sharing system could support faster responses and improve preparedness across the banking sector.
What SBI’s Q2 Performance Means for the Coming Quarters
SBI’s July-September results reflect the strength of credit demand and the bank’s ability to expand interest income while keeping its net interest margin above 3%. The 14% increase in net profit, nearly 15% growth in net interest income and improvement in asset quality provide important indicators of the bank’s operating position.
At the same time, the quarter highlighted several issues that could influence its future performance. Treasury losses linked to higher bond yields affected other income, while higher expenses limited operating profit growth to 7%. The slower pace of deposit growth compared with advances also makes funding management an important area to monitor.
The bank’s decision to retain its 14-15% loan growth guidance indicates that it is not treating the unusually strong quarterly expansion as its new baseline. Future growth will depend on credit demand, deposit mobilisation, funding costs and the bank’s ability to manage risk while expanding its balance sheet.
Cybersecurity will remain another important focus. The ongoing investigation into the data breach, API checks and vulnerability assessments are part of SBI’s effort to strengthen its digital defences. As banking services become increasingly technology-driven, protecting customer data and maintaining the reliability of digital systems will be as important as delivering financial growth.
For investors, SBI’s next results will offer further insight into whether the bank can sustain its lending momentum, defend its margins, control expenses and manage technology-related risks. The latest quarter delivered strong headline profit and interest income growth, but its treasury performance, operating costs and cybersecurity preparedness remain important areas of attention.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0