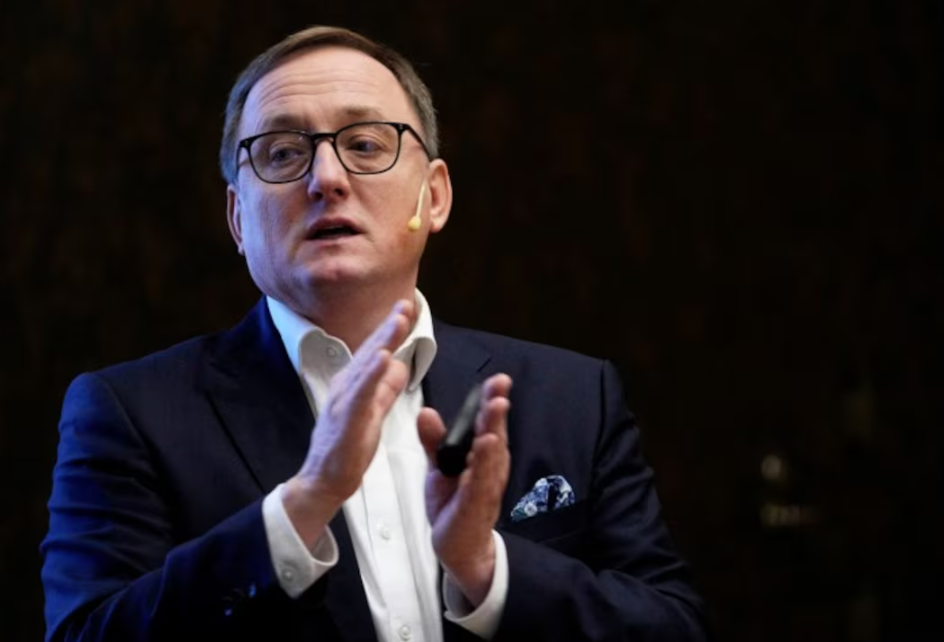
The European Central Bank is facing a more difficult inflation environment as higher energy prices threaten to keep consumer-price pressures elevated across the euro zone. ECB policymaker and Latvian central bank governor Martins Kazaks has warned that the case for additional interest-rate increases is becoming stronger, although he stressed that the central bank can act gradually rather than rushing into a series of aggressive moves.
The comments come after the ECB raised its key interest rate to 2.5% from 2.25%, marking its second rate increase of 2026. With euro zone inflation at 3.3% in August and the central bank expecting inflation to rise further in the coming months, policymakers are increasingly focused on whether the latest energy shock could become embedded in wages, services and other prices.
ECB May Need More Rate Hikes, Kazaks Says
Kazaks said the argument for further monetary tightening is strengthening as inflation remains above the ECB’s comfort zone and energy costs continue to rise. His comments indicate that the ECB’s latest rate increase should not necessarily be interpreted as the end of its tightening cycle.
The ECB currently views 2.5% as the upper end of a broadly neutral interest-rate range. A neutral rate is generally understood as a level that neither provides significant stimulus to economic activity nor deliberately restricts it. Kazaks, however, said policymakers should not treat 2.5% as a fixed ceiling.
If inflation risks continue to build, interest rates could move into restrictive territory, where borrowing conditions are deliberately tightened to weaken demand and prevent persistent price increases.
This distinction is important because the ECB is now dealing with an inflation shock that is not coming entirely from strong domestic demand. Higher fuel and energy costs can raise inflation directly while also increasing the costs faced by businesses, transport companies and households.
Why Energy Prices Are Becoming a Bigger ECB Concern
The escalation of energy prices linked to the Iran conflict has created a new challenge for central banks. Higher oil and fuel prices can initially push inflation higher through energy bills and transportation costs. The bigger concern for monetary policymakers is what happens afterward.
If businesses pass higher costs on to consumers, prices of goods and services can rise more broadly. Workers may then demand higher wages to compensate for the loss of purchasing power. Companies could respond to higher labour costs with further price increases, creating a more persistent inflation cycle.
Kazaks believes this risk deserves attention because the euro zone economy is operating close to capacity. When there is less unused economic capacity, businesses may have greater ability to pass higher input costs through to final prices.
What the ECB Is Watching
- Energy prices: A prolonged oil and fuel shock could keep headline inflation elevated.
- Wage growth: Faster wage increases could make inflation more persistent.
- Consumer behaviour: Repeated increases in everyday expenses can raise inflation expectations.
- Business pricing: Companies may pass higher energy and labour costs to customers.
- Economic capacity: A closing output gap can increase the risk of stronger price pass-through.
Euro Zone Inflation Remains Above the ECB’s Comfort Zone
Euro zone inflation stood at 3.3% in August. The ECB expects inflation to increase further, with its forecast putting inflation at around 3.6% in the final quarter of 2026.
That trajectory creates a difficult policy problem. Central banks normally want inflation to return sustainably toward their target rather than simply falling temporarily because of favourable base effects or weaker demand.
The current situation is particularly challenging because higher energy prices can simultaneously weaken household purchasing power and increase inflation. Consumers may have less money available for discretionary spending, while the headline inflation rate continues to rise because essential costs are increasing.
This creates a potential conflict between supporting economic activity and preventing inflation from becoming entrenched.
| Indicator | Latest information | Why it matters |
|---|---|---|
| ECB key rate | 2.5% | Current policy rate after the latest increase |
| Previous ECB rate | 2.25% | Level before the latest hike |
| Euro zone inflation | 3.3% in August | Shows inflation remains elevated |
| ECB Q4 inflation forecast | 3.6% | Signals further near-term price pressure |
| Negotiated wage growth | 2.44% in Q2 | Important for assessing second-round inflation effects |
Kazaks Says ECB Does Not Need to Rush
Although Kazaks sees a stronger case for additional tightening, he does not advocate a sudden or aggressive policy response. He said the ECB can move stepwise and without rush.
This suggests the central bank could assess incoming inflation, wage and energy data between meetings before deciding how far rates need to rise. Such an approach gives policymakers flexibility if the energy shock fades or if economic activity weakens more significantly.
It also reflects the uncertainty surrounding the current inflation environment. Monetary policy works with a delay, meaning that previous rate increases are still affecting borrowing costs, investment decisions, housing activity and consumer demand.
Moving gradually allows the ECB to determine whether earlier tightening is already sufficiently restraining demand or whether additional increases are necessary.
Will the ECB Raise Rates Again in October?
Kazaks did not commit to an October rate increase. His comments nevertheless strengthen expectations that another hike could be considered if inflation and energy-price pressures remain elevated.
The important point is that the ECB is no longer treating 2.5% as an automatic endpoint. Future decisions will depend on how quickly inflation is moving, whether energy costs remain high and whether those costs begin influencing wages and broader price-setting behaviour.
An October increase would therefore depend less on a predetermined schedule and more on evidence that inflation risks are becoming persistent.
Three Possible Policy Paths
Further gradual tightening: If energy prices remain high and underlying inflation stays elevated, the ECB could raise rates incrementally above 2.5%.
Pause and assess: If inflation begins stabilising or the economic impact of higher borrowing costs becomes more visible, policymakers could temporarily hold rates steady.
Stronger tightening: If energy prices rise sharply and wage and services inflation accelerate, the ECB could consider moving rates more decisively into restrictive territory.
The Output Gap Could Make Inflation More Persistent
One of Kazaks’ most important observations concerns the output gap. The output gap broadly describes the difference between an economy’s actual production and its estimated potential level of output.
When an economy has significant spare capacity, businesses may find it harder to increase prices because demand is weak. But when the economy operates near capacity, companies may have greater pricing power and supply constraints can become more influential.
Kazaks said the euro zone’s output gap is closing. In his assessment, this means the pass-through of higher fuel costs into prices and wages could become stronger.
For the ECB, that is an important warning. A temporary energy-price shock is easier to manage if it does not spread into other parts of the economy. The central bank becomes more concerned when an initial increase in fuel costs starts affecting wages, services and inflation expectations.
Wage Growth Is Another Key Inflation Test
Negotiated wages in the euro zone rose by 2.44% in the three months to June, down from a 2.56% increase in the first quarter.
The moderation in wage growth provides some reassurance because slower wage increases can reduce the risk of a self-reinforcing inflation cycle. However, Kazaks is concerned about what could happen if energy and food prices rise enough to change wage negotiations.
Workers are more likely to pay attention to inflation when they repeatedly see higher prices for necessities. Fuel and food are particularly important because households encounter these costs frequently.
If inflation remains above wage growth for a prolonged period, households may feel a greater loss of purchasing power. That could increase pressure for higher pay, particularly if employees and unions view inflation as a persistent rather than temporary problem.
Why Food and Fuel Prices Matter So Much
Not all inflation affects consumers psychologically in the same way. Everyday purchases such as fuel and food are highly visible because households encounter them regularly.
Kazaks described inflation as still being in an area where consumers and businesses may not be paying close attention to the broader inflation rate. But he warned that this could change if essential products become significantly more expensive.
This creates a risk for inflation expectations. When consumers repeatedly experience price increases at petrol stations or grocery stores, they may become more sensitive to inflation across the economy.
For the ECB, preventing that change in expectations is important because inflation expectations can influence wage negotiations, spending decisions and corporate pricing strategies.
Higher ECB Rates Could Affect the European Economy
Additional rate increases would not affect only financial markets. Higher borrowing costs can influence households, companies and governments across the euro zone.
For households, higher interest rates can increase the cost of new borrowing and make major purchases more expensive. Companies may reconsider investment projects when financing becomes more costly. Governments can also face higher refinancing costs as existing debt matures and is replaced with debt carrying higher interest rates.
At the same time, higher rates can help contain demand. If inflation is being driven partly by strong demand and the ability of businesses to pass costs through to consumers, tighter financial conditions can help reduce those pressures.
Potential Effects of More ECB Tightening
- Higher borrowing costs for households and businesses.
- Potentially weaker consumer and investment demand.
- Greater pressure on highly leveraged companies.
- Potential support for the euro if European interest rates rise relative to other economies.
- Lower risk of inflation becoming entrenched if tightening is effective.
Why the ECB Faces a Delicate Balancing Act
The ECB’s challenge is not simply whether inflation is high. Policymakers must determine why inflation is high and how persistent it is likely to become.
If the main driver is a temporary energy shock, aggressive rate increases could unnecessarily weaken economic growth while doing little to reduce the initial energy cost. oil prices, for example, are influenced by geopolitical and supply conditions that monetary policy cannot directly control.
However, if the energy shock begins spreading into wages and broader prices, monetary policy becomes more relevant. Higher interest rates can reduce demand and help prevent secondary inflation effects from becoming entrenched.
This is why Kazaks’ comments focus heavily on the risk of pass-through from energy prices to wages and other consumer prices.
What Markets Will Watch Next
Investors and economists are likely to focus on several indicators before the ECB’s next policy decisions. Inflation data will remain the central focus, but energy prices and wage trends may become equally important.
The direction of oil and gas prices will be especially significant because a sustained energy shock could alter the ECB’s inflation outlook. At the same time, policymakers will watch whether companies are passing higher costs through to consumers and whether wage negotiations begin accelerating again.
The broader economic performance of the euro zone will also matter. If growth remains resilient while inflation stays elevated, the argument for further tightening becomes stronger. If higher energy costs cause a significant slowdown, the ECB may have to balance inflation control against economic weakness.
Key Questions for the ECB
- Will euro zone inflation rise toward the ECB’s 3.6% fourth-quarter forecast?
- Will energy prices remain elevated for long enough to affect broader inflation?
- Will wage growth accelerate in response to higher living costs?
- Will the closing output gap increase price and wage pass-through?
- Will the ECB raise rates again in October or wait for additional evidence?
- How far above 2.5% would rates need to go if inflation becomes persistent?
What Kazaks’ Comments Mean for the ECB’s Rate Path
Kazaks’ remarks reinforce a significant shift in the ECB’s policy discussion. The debate is no longer simply about whether the latest rate increase was enough. Policymakers are increasingly considering whether interest rates need to move beyond the neutral range to ensure inflation returns to a sustainable level.
However, the comments also indicate that the ECB is not preparing for an emergency tightening cycle. The emphasis on moving stepwise and without rush suggests that policymakers want to preserve flexibility and respond to incoming data rather than commit to a predetermined sequence of hikes.
The biggest risk is that today’s energy shock becomes tomorrow’s broader inflation problem. If higher fuel and food prices begin influencing wages and service prices, the ECB could face pressure to tighten policy further.
Conclusion: ECB Keeps the Door Open to More Rate Hikes
The ECB’s latest interest-rate increase to 2.5% may not be the final step in its fight against inflation. Martins Kazaks’ assessment that the case for more tightening is building highlights growing concern about elevated inflation, higher energy prices and the closing output gap.
At the same time, his call for a stepwise approach shows that the ECB still has room to assess the effects of previous decisions. The central bank does not need to rush if inflation expectations remain contained and wage growth stays moderate.
The key issue for the coming months will be whether the energy shock remains concentrated in fuel and other commodities or spreads into wages, services and broader consumer prices. If that second-round effect emerges, the ECB could increasingly need to move interest rates into restrictive territory.
For financial markets, the message is clear: 2.5% should not automatically be viewed as the ceiling for ECB rates. Future policy will depend heavily on the persistence of inflation and the extent to which geopolitical energy pressures become embedded in the wider euro zone economy.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0