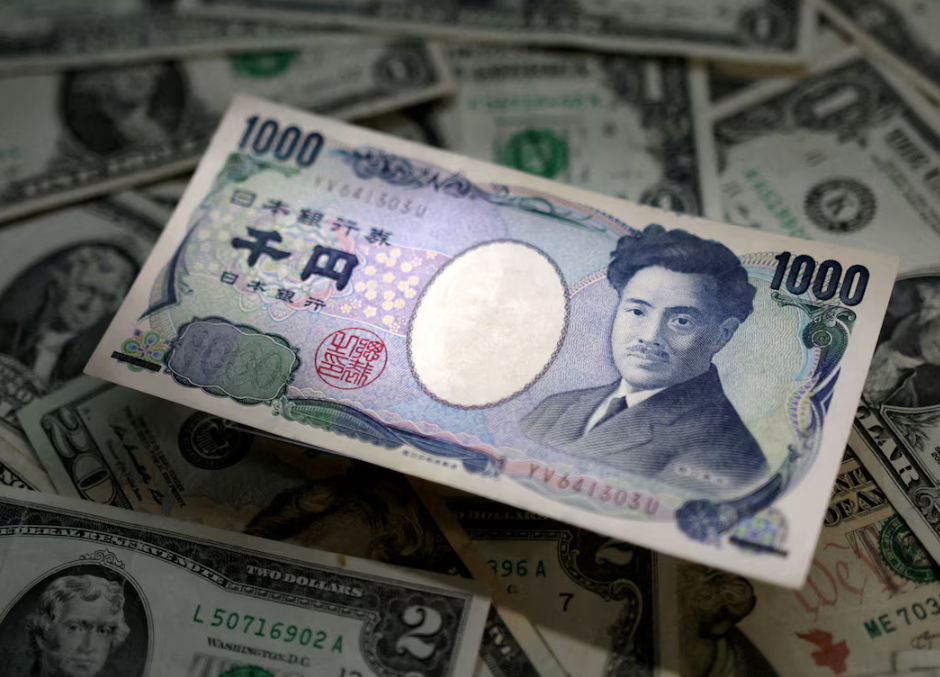
The Japanese yen weakened on Monday as currency traders weighed the possibility of intervention by Japanese authorities against the Bank of Japan’s latest interest-rate increase. Meanwhile, the US dollar remained broadly steady after strengthening last week, when the Federal Reserve delivered a hawkish policy signal.
The yen’s decline highlights a complicated situation for global currency markets: Japan has raised borrowing costs, but investors remain uncertain about the pace of future tightening. At the same time, expectations that US interest rates could remain elevated have supported the dollar.
Why the Japanese Yen Is Weakening Despite Higher Interest Rates
The yen came under renewed pressure after the Bank of Japan (BOJ) raised its policy rate to 1.25% on Friday, its highest level in 31 years, according to the Reuters report published on September 21, 2026.
Although an interest-rate increase can support a currency by improving the return on assets denominated in that currency, the market reaction depends heavily on what investors expect next. In this case, the BOJ’s decision did not provide a sufficiently clear signal that a faster series of rate increases would follow.
Two policymakers dissented from the decision, and the central bank did not provide explicitly hawkish guidance. Investors therefore remained cautious about buying the yen, even after the rate increase.
By Monday, the US dollar had risen 0.2% against the Japanese currency to 157.20 yen. The move reflected continued pressure on the yen as traders assessed the difference between the monetary-policy outlooks of Japan and the United States.
BOJ Rate Hike: Why the Market Reaction Was Not Straightforward
Interest-rate decisions are important to foreign-exchange markets, but the size of a rate increase is only one part of the story. Traders also examine the central bank’s communication, voting patterns, inflation outlook and indications about future policy.
The BOJ’s latest move raised the policy rate, but investors were left without a strong assurance that further increases would come quickly. That uncertainty limited the yen’s ability to benefit from the decision.
The distinction is important because currency markets respond to changes in expectations, not simply to whether rates have moved higher or lower. If investors had already anticipated a rate increase, the decision itself might provide limited additional support unless the accompanying guidance was more hawkish than expected.
Policy expectations matter as much as the rate itself
For the yen to gain sustained support from monetary policy, investors would need to assess whether Japan’s interest rates are likely to rise further and how that path compares with rates in other major economies.
If the BOJ signals a gradual approach while other central banks maintain a tighter stance, the relative appeal of the yen may remain constrained. Conversely, clearer guidance about future tightening could alter expectations and influence currency positioning.
Rate Checks Put Japanese Currency Intervention Back in Focus
Another factor shaping the yen’s movement is the possibility that Japanese authorities could intervene to limit excessive currency weakness.
Following the BOJ’s Friday decision, the yen fell sharply before recovering slightly. The Nikkei newspaper then reported that Japanese officials had conducted rate checks, a development often watched by traders for signs that authorities may be preparing to intervene.
A rate check generally involves officials contacting financial institutions to ask about exchange-rate conditions. Such checks can draw attention to the authorities’ concerns and influence traders’ expectations, although they do not automatically mean that an intervention will follow.
MUFG senior currency analyst Lee Hardman said the reported rate check could help reduce expectations about how far the yen might be allowed to weaken in the near term.
The market’s attention to intervention reflects the risk that a rapid currency move could prompt a policy response. Even without an immediate intervention, the possibility can make traders more cautious about building positions against the yen.
Why intervention threats can influence currency trading
Currency intervention occurs when authorities buy or sell currencies to influence exchange-rate conditions. In Japan’s case, selling foreign currency and buying yen can increase demand for the Japanese currency.
However, intervention is not a guaranteed way to create a lasting exchange-rate trend. Its impact can depend on the scale and timing of the action, broader monetary-policy conditions and whether market forces continue to push in the opposite direction.
For traders, the key issue is uncertainty. If authorities are perceived as increasingly concerned about yen weakness, positions that rely on further depreciation may become riskier.
Low Liquidity Adds to Yen Market Volatility
Japanese markets were closed for a three-day holiday on Monday, leaving currency trading conditions relatively thin. Lower liquidity can make markets more sensitive to large orders and sudden shifts in sentiment.
In a low-liquidity environment, price movements may become sharper because fewer market participants are available to absorb buying or selling pressure. This can complicate the interpretation of short-term currency moves.
The holiday also meant traders were watching closely for any signs of official action while Japanese domestic markets were closed. The combination of intervention concerns and reduced liquidity added another layer of uncertainty to yen trading.
For investors, this means Monday’s exchange-rate movement should be considered alongside the broader policy outlook rather than treated as a complete indication of the yen’s longer-term direction.
US Dollar Remains Supported by the Federal Reserve’s Hawkish Signal
The US dollar held broadly steady on Monday after gaining more than 1% last week. The dollar index, which measures the currency against a basket of six major peers, stood at 100.23.
The dollar’s recent strength followed the Federal Reserve’s interest-rate increase and its hawkish messaging. The Reuters report said traders were pricing in a 55% probability of another Fed rate hike at the October meeting, compared with 43% a week earlier, according to CME FedWatch data.
These market expectations show how quickly interest-rate forecasts can change after central-bank decisions. They are not a guarantee that the Fed will raise rates in October; they reflect the probability assigned by market participants at the time of the report.
How US interest rates affect the dollar
Higher US interest rates can support the dollar by increasing the potential returns available on dollar-denominated assets relative to assets in countries with lower rates.
When investors expect the Fed to maintain or increase rates while another central bank is expected to move more gradually, the difference in expected returns can influence currency demand.
That dynamic has been relevant to the yen-dollar exchange rate. The BOJ’s latest increase did not eliminate the perceived policy gap between Japan and the United States, leaving the dollar supported against the yen.
Middle East Conflict Keeps Inflation and Central Banks in Focus
The Reuters report also linked the wider interest-rate outlook to inflation concerns associated with the nearly seven-month-long war in the Middle East.
The Federal Reserve and European Central Bank raised rates this month and warned that additional tightening might be necessary to address inflation. The conflict has kept attention on energy prices and the possibility that higher costs could spread through the wider economy.
Energy-price movements can affect inflation expectations, household spending and business costs. Central banks may respond if they believe inflation will remain elevated, although the timing and scale of any policy response depend on incoming economic data.
For currency markets, the implication is that monetary policy remains closely connected to developments beyond domestic economic indicators. Changes in energy prices and inflation expectations can influence interest-rate forecasts, which in turn can affect exchange rates.
Euro and Sterling Remain Relatively Stable
While the yen weakened and the dollar held steady, other major currencies showed limited movement in Monday’s trading.
- Euro: Little changed at $1.149, as investors considered political developments in Germany alongside the broader monetary-policy outlook.
- British pound: Flat at $1.339 against the dollar.
- US dollar index: Steady at 100.23 after gaining more than 1% in the previous week.
- US dollar against yen: Up 0.2% to 157.20 yen.
The euro’s stability came as Germany’s Alternative for Germany party took first place in state elections in the country’s northeast, according to the report. Chancellor Friedrich Merz’s conservative party suffered a major regional setback, adding a political dimension to euro trading.
However, a single regional election does not by itself determine the euro’s direction. Currency movements also reflect economic data, interest-rate expectations, market positioning and developments across the wider euro area.
Investors Had Built Bullish Yen Positions Before the BOJ Meeting
The yen had strengthened to its highest level in seven months in early September, as traders anticipated a faster pace of BOJ rate increases and signs emerged that Japanese investors might bring funds back home.
That optimism was reflected in positioning data. According to weekly US regulatory figures cited by Reuters, speculators increased their net long-yen positions in the week to September 15. Their net-long exposure reached $9.7 billion, the largest level since July 2025.
A net-long position means that traders’ bullish exposure to the yen exceeds their bearish exposure. Such positioning can indicate confidence in a currency, but it can also make the market vulnerable if new information challenges that confidence.
Why crowded positions can increase volatility
When many investors hold similar positions, a shift in expectations can lead to rapid adjustments. If traders who had expected yen appreciation begin reducing those positions, selling pressure can increase.
That does not mean a reversal must occur. Positioning data is one indicator among many, and its significance depends on the economic and policy developments that follow.
In the current situation, the BOJ’s less-hawkish-than-expected communication and the Fed’s stronger policy signal tested the bullish yen outlook that had developed earlier in September.
Why the Federal Reserve’s Policy Signal Complicates the BOJ’s Task
HSBC chief Asia economist Fred Neumann said the BOJ’s communication had become more difficult because the Federal Reserve delivered a hawkish signal through a unanimous decision to raise its policy rate.
The contrast matters because the BOJ is trying to communicate its own policy direction while global investors are also evaluating the Fed’s stance. If US rates are expected to remain comparatively high, the yen may struggle to attract sustained demand solely because Japan has raised rates.
Neumann said the BOJ still faces a high bar in convincing markets of its hawkish position and anchoring expectations for the yen.
This highlights the importance of clear central-bank communication. Policymakers must explain how they interpret inflation, economic growth and financial conditions, while investors decide whether those explanations justify changing their currency positions.
Could the Yen Fall Further Before Intervention?
Thomas Mathews, head of markets for Asia-Pacific at Capital Economics, said the market clearly viewed the Federal Reserve as more hawkish than the BOJ, despite Japan’s rate increase.
Mathews also noted that the yen remained stronger than it had been previously, suggesting that a further decline might be needed before intervention returned to the immediate market discussion.
This is an attributed market assessment, not an official intervention threshold. Authorities do not necessarily act at a single exchange rate, and currency policy decisions can depend on the speed and volatility of a move as well as broader market conditions.
For that reason, the yen’s level alone cannot establish whether intervention will occur. Traders are likely to continue monitoring official comments, reports of rate checks and the pace of exchange-rate movements.
Historical Context: The Yen’s Four-Decade Low in July
The yen’s recent movements follow a period of substantial weakness. The currency fell to a four-decade low of 163.99 per dollar in July, according to Reuters.
A rare coordinated intervention by Tokyo and Washington helped lift the yen at that time. The episode remains relevant to current trading because it demonstrates that authorities have previously taken action when exchange-rate conditions became a major concern.
Still, past intervention does not establish when or whether authorities will act again. Market conditions, policy priorities and the scale of currency movements can differ from one episode to another.
The July episode therefore provides context for traders’ vigilance, rather than a reliable template for predicting the next policy move.
What Traders May Watch in the Coming Sessions
Several developments could influence the yen and dollar as markets reassess the global interest-rate outlook.
- Japanese official signals: Comments from policymakers and further reports of rate checks could affect expectations about possible intervention.
- BOJ communication: Investors will assess whether officials provide clearer indications about the pace and conditions for future rate increases.
- Federal Reserve expectations: Economic data and Fed commentary could change market pricing for the October meeting and subsequent policy decisions.
- Inflation and energy prices: Developments related to the Middle East conflict may influence inflation expectations and central-bank decisions.
- Market positioning: Changes in speculative yen positions could amplify currency moves if investor expectations shift.
- Liquidity conditions: Trading activity around Japanese market holidays and other periods of reduced liquidity may affect short-term volatility.
These factors interact with one another. For example, a change in Fed expectations could influence the dollar, while Japanese official comments could affect the perceived risk of holding short positions in the yen.
What the Yen-Dollar Outlook Means for Businesses and Investors
Movements in the yen-dollar exchange rate can affect companies, investors and households with exposure to international trade or overseas assets.
For Japanese importers, a weaker yen can raise the domestic cost of goods priced in dollars, including many internationally traded commodities. The extent of the impact depends on contract terms, hedging arrangements and the currency in which purchases are settled.
Japanese exporters may receive more yen when converting foreign-currency revenue, although the benefit depends on production costs, overseas operations and currency-hedging practices.
Investors holding international assets also face exchange-rate effects. A change in the yen’s value can alter the yen-denominated return on overseas investments, even when the underlying asset price remains unchanged in its local market.
These effects are not uniform across all businesses or investors. Currency exposure, pricing power, financial structure and hedging decisions all influence how exchange-rate movements translate into real-world outcomes.
Yen and Dollar: The Key Takeaway
The Japanese yen weakened on September 21 as traders balanced the BOJ’s latest rate increase against its cautious guidance, the Federal Reserve’s hawkish stance and the possibility of intervention by Japanese authorities.
The dollar’s recent gains reflect changing expectations about US monetary policy, while the yen’s earlier strength and bullish investor positioning have come under pressure. Reports of Japanese rate checks have added a further source of uncertainty, especially during a period of reduced liquidity.
The central question for currency markets is whether Japan’s policymakers can provide a clearer path for future tightening while the Fed maintains a comparatively hawkish signal. Until expectations become clearer, the yen-dollar exchange rate may remain sensitive to central-bank communication, intervention concerns and changes in market positioning.
For now, traders are watching both sides of the policy equation: the BOJ’s willingness to tighten further and the Fed’s approach to inflation. Neither the reported rate checks nor current market pricing guarantees a particular exchange-rate outcome.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0