Merchant cash advances are increasingly marketed as a quick financial lifeline for small businesses struggling to access traditional bank loans. Promising fast approvals, minimal paperwork and cash within 24 hours, these financing arrangements can appear attractive to business owners facing urgent cash-flow problems. However, extremely high financing costs and frequent withdrawals from company accounts can turn the short-term solution into a serious financial burden.
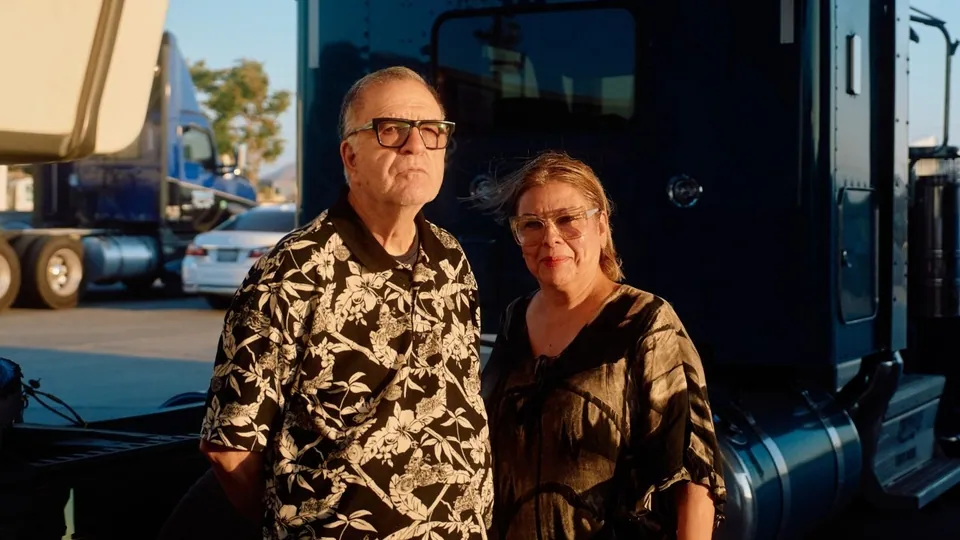
The experience of Triways, a family-owned trucking and warehouse business in Southern California, illustrates the risks. After operating for nearly five decades, the company struggled with mounting merchant cash advance obligations that eventually contributed to its financial collapse and closure.
Triways generated nearly $10 million in revenue in 2024 and employed around 60 people. Its chief executive, 70-year-old John Jauregui, had initially expected a new contract supplying Navy commissaries across California, Oregon, Washington and Florida to help the business expand nationwide.
To finance additional trailers and drivers, Jauregui turned to merchant cash advances, commonly known as MCAs. What appeared to be an easy source of funding eventually developed into a cycle of repeated borrowing, increasingly expensive repayments and severe cash-flow pressure.
What Are Merchant Cash Advances and Why Are They Risky?
Merchant cash advances are financing arrangements in which a business receives money upfront in exchange for a portion of its future revenue or an agreed repayment amount. Providers often market them as alternatives to conventional loans, particularly for businesses that struggle to qualify for bank financing.
Unlike traditional lenders, MCA funders generally argue that they are purchasing future business receivables rather than issuing loans. This distinction can allow them to operate under different regulatory requirements, depending on the jurisdiction and structure of the agreement.
The financing can be arranged quickly, with applications often requiring less documentation than conventional bank loans. However, the repayment terms can be expensive, and providers may withdraw money directly from a company’s bank account daily or weekly.
These automatic deductions can create problems when a business has unpredictable revenue or significant operating expenses. Even companies generating sales may struggle to pay employees, suppliers, rent and other bills after repeated withdrawals reduce their available cash.
One of Triways’s financing agreements carried an estimated annual percentage rate of 2,190%, according to a disclosure document. Jauregui said he had not understood how expensive the financing would become when he accepted the advances.
Bankruptcy attorneys warn that MCAs may be suitable only for businesses with a short-term funding requirement and a clear repayment plan. Michael Dal Lago, a bankruptcy attorney in Naples, Florida, said an advance might make sense for an immediate expense that can be repaid within 30 days, but using it as a regular line of credit can create serious financial problems.
Why Small Businesses Are Turning to Merchant Cash Advances
Small businesses across the United States are facing a challenging financing environment. Inflation, tariffs, higher operating costs and tighter credit conditions have increased the need for working capital, while access to traditional bank loans remains difficult for many companies.
Since the financial crisis nearly two decades ago, banks have pulled back from some areas of small-business lending. MCA providers have moved into this financing gap by offering businesses quicker access to cash, often when conventional lenders decline their applications.
A survey conducted by regional Federal Reserve Banks found that 12% of small businesses seeking financing applied for a merchant cash advance last year, compared with 9% in 2024.
The Federal Reserve Bank of Kansas City reported in October that small businesses were increasingly using MCAs to cover overhead expenses and payroll. However, the report also warned that the high costs of these arrangements had exacerbated financial difficulties for some businesses.
Bankruptcy figures underline the pressure facing smaller companies. Federal bankruptcy filings by small businesses with debts of no more than $3.4 million increased 36% during the first nine months of 2026 compared with the same period a year earlier, according to the American Bankruptcy Institute.
An analysis of bankruptcy filings by The Wall Street Journal found that companies offering merchant cash advances appeared among the creditors in more than half of those cases. Federal bankruptcy judge Caryl Delano of Tampa said virtually every small-business bankruptcy case she encountered involved at least one MCA provider, with some businesses owing money to several funders.
How Multiple Cash Advances Created a Debt Cycle at Triways
Triways’s financial difficulties began before its Navy supply contract. Jauregui already had a conventional line of credit but could not secure additional bank financing when he took his first merchant cash advance in the autumn of 2023.
He initially expected to repay the six-figure obligation quickly. However, the company encountered financial difficulties while waiting for a tax refund linked to federal relief for businesses affected by Covid-19 shutdowns.
In July 2024, a broker persuaded Jauregui to take another advance to help settle existing MCA obligations. Instead of resolving the problem, the additional financing left Triways owing money on both the earlier advances and the new agreement.
That autumn, the company began deliveries for the Navy. The contract offered an opportunity to expand, but the daily withdrawals by MCA providers left limited cash available to cover the additional operating costs, including drivers, trailers and other expenses. Triways began missing rent payments in December 2024.
When the delayed tax refund finally arrived in April 2025, Jauregui used the money to reduce the company’s MCA obligations. Despite the payment, Triways still owed between $300,000 and $400,000. By June, its unpaid rent had accumulated to approximately $1 million.
The situation became more difficult after revenue from a major customer fell by roughly half for eight months beginning in September 2025. Triways took out four additional MCAs, agreeing to repay an estimated $771,500 in exchange for approximately $470,000. Around $64,000 of the new funding went towards settling an earlier advance.
By the autumn of 2025, Jauregui had consulted a bankruptcy attorney. In an October letter to the landlord, a small-business lender and four MCA funders, the lawyer said Triways owed more than $700,000 to MCA providers and had net operating income of approximately $120,000 after rent.
The lawyer proposed a repayment arrangement, warning that creditors might recover only a third of the amount owed if the company stopped operating. He also advised Jauregui to consider bankruptcy liquidation if the funders refused to accept reduced payments.
Jauregui was reluctant to close the business and believed he could still turn its finances around. However, the company’s bank subsequently closed its accounts, adding another challenge to its efforts to remain operational.
Repeated Borrowing Leaves Little Money for Payroll
Triways continued taking out merchant cash advances as it struggled to meet its financial commitments. On a single day in November 2025, Jauregui entered into two new agreements.
One of those arrangements required Triways to repay an estimated $674,550 in exchange for $427,500, according to financing documents. Most of the money was used to settle three earlier MCAs and a small-business loan, leaving just $5,815.60 for operating expenses.
The company took out another advance 10 days later. It then entered into four additional MCA agreements over eight days in January 2026, followed by further advances in February and March.
Some of the later advances were for less than $50,000. Jauregui said he was borrowing increasingly small amounts because he was desperate to make payroll and keep the business running.
The repeated funding offers created a cycle in which new advances were used to pay earlier obligations, while the remaining money was insufficient to support normal operations. Jauregui said the ease of obtaining funds made the arrangement difficult to escape: the immediate financial problem appeared to be solved, but the situation became worse later.
At one point, Triways was receiving new MCA offers almost every day. As providers continued withdrawing money from its accounts, Jauregui and his wife, Jackie, struggled to manage bills and maintain operations.
The pressure also affected relationships with customers and suppliers. In an August message, a Triways customer service representative asked Mrs Jackie to use Zelle for a payment, explaining that another cheque might bounce.
How MCA Funders Use Legal Claims to Recover Money
When businesses fall behind on repayments, merchant cash advance providers may use legal mechanisms such as Uniform Commercial Code (UCC) lien notices to pursue money owed to them.
These notices can instruct customers who owe payments to a struggling business to redirect the money to the MCA funder or its legal representative. Depending on the agreement and applicable law, claims may also affect funds held by credit-card processors and payment platforms.
Triways experienced this pressure when one of its customers, Feast Kitchens, received a notice asking it to hold payments owed to the trucking company and direct them to a law firm representing Horizon Capital NY. Triways reportedly owed Horizon approximately $280,000.
A separate notice from another attorney stated that the company owed Square Funding Cali around $379,000. A lawyer for Square Funding Cali declined to comment and clarified that the company was not related to Block, which operates the Square payment platform.
Such notices can make it harder for a struggling business to maintain normal cash flow. Money that would otherwise be used to pay employees, suppliers or rent may instead be directed towards creditors, further weakening the company’s ability to operate.
Richard Cook, a bankruptcy attorney in Wilmington, North Carolina, said MCA providers may be less interested in keeping a struggling business operational than conventional lenders, which sometimes negotiate repayment arrangements to help borrowers remain in business.
Shane Heskin, a New York attorney representing Triways, argued that the high charges associated with MCAs allow funders to remain profitable even when only a portion of their contracts are repaid in full. He said the repayment pressure can push business owners towards selling assets, borrowing against their homes or taking out additional advances to meet existing obligations.
Regulatory Concerns and Legal Challenges Facing the MCA Industry
The growing use of merchant cash advances has attracted attention from lawmakers, regulators and bankruptcy courts in the United States. A central issue is whether some arrangements described as purchases of future receivables are effectively high-interest loans.
Lawmakers in a dozen states have introduced or passed measures addressing the industry. California, Vermont and New York require disclosures of estimated annual percentage rates for certain merchant cash advances. California also requires MCA brokers and funders to obtain licences as finance providers.
Some bankruptcy judges have concluded that particular MCA agreements should be treated as loans rather than purchases of future receivables, potentially bringing them under lending regulations.
A major legal development came last year when New York Attorney General Letitia James secured a $1 billion settlement with Yellowstone Capital over allegations that the company had issued merchant cash advances that were actually illegal high-interest loans. Yellowstone Capital neither admitted nor denied guilt as part of the settlement.
The Small Business Administration has also taken a more restrictive approach to these arrangements. It announced last year that it would no longer refinance merchant cash advances.
SBA Administrator Kelly Loeffler raised concerns about the high failure rates associated with businesses using such financing during a presentation to SBA lenders.
Industry representatives, however, argue that alternative financing remains important for companies that cannot obtain conventional credit or need money quickly.
Steve Denis, executive director of the Small Business Finance Association, which estimates the MCA market at approximately $20 billion, said its members offer different financing products to businesses that need access to capital.
Denis acknowledged that predatory providers operate in the industry but said the association was working to address abusive practices and prevent bad actors from continuing to operate. He maintained that responsible financing providers want businesses to succeed and survive.
Triways Files for Bankruptcy as Financial Pressure Intensifies
By April 2026, Triways’s financial position had deteriorated significantly. The company filed for Chapter 11 bankruptcy reorganisation, citing MCA payments of approximately $250,000 per month and the financial pressure created by UCC notices sent to its customers.
Court filings showed that Triways had assets worth approximately $2.1 million against nearly $6.8 million in liabilities. More than $1.2 million was owed to merchant cash advance providers.
However, the bankruptcy case was dismissed in June after the trustee reported that the company had missed payroll following the filing and did not have workers’ compensation insurance, which is required under California law.
In August, Jackie Jauregui contacted Horizon Capital NY and requested that the company release its lien of approximately $280,000 and restore a monthly repayment arrangement. She argued that eliminating Triways’s remaining source of revenue would harm all parties involved.
A lawyer representing Horizon responded that the company wanted a specific amount that Triways could commit to paying each week. The lawyer declined to comment on the matter, citing pending litigation.
Triways eventually ceased operations in September 2026. Jauregui said he had tried to keep the business alive for as long as possible.
Following the closure, two MCA providers asked a New York state court to enter default judgments exceeding $585,000 against Triways. A third provider sought confirmation of an arbitration award worth approximately $415,000.
Even after the company stopped operating, funding offers continued to arrive. Jauregui received several separate offers by text message within roughly two hours on a Wednesday, including one suggesting he could qualify for up to $200,000.
What Small Businesses Should Consider Before Taking an MCA
The Triways case highlights the importance of understanding the full cost and repayment structure of merchant cash advances before accepting funding. Quick access to money can help address an urgent need, but repeated advances can create obligations that exceed a company’s ability to generate cash.
Business owners considering an MCA should examine several factors before signing an agreement:
- Total repayment amount: Compare the money received with the full amount that must be repaid, rather than focusing only on the upfront funding.
- Effective financing cost: Review the estimated annual percentage rate and other charges to understand the actual cost of the arrangement.
- Repayment frequency: Daily or weekly withdrawals can put pressure on cash flow, particularly when revenue fluctuates.
- Impact on operating expenses: Calculate whether the business can continue paying employees, suppliers, rent and other essential costs after deductions.
- UCC liens and legal provisions: Understand whether the agreement allows the funder to claim future receivables or redirect payments from customers and payment processors.
- Repeated borrowing risks: Avoid relying on new advances to repay existing ones without a realistic plan to reduce the overall debt.
- Alternative financing: Compare bank credit, small-business financing programmes and other funding options before accepting expensive short-term capital.
Easy Access to Cash Can Come at a High Cost
Merchant cash advances have expanded partly because they address a genuine financing problem for small businesses: many companies need working capital but cannot secure traditional bank loans quickly or at affordable rates.
However, the speed and convenience of these arrangements can hide substantial financial risks. High repayment obligations, automatic withdrawals and legal claims against future receivables can leave businesses with little room to manage unexpected expenses or changes in revenue.
The experience of Triways demonstrates how an attempt to finance expansion can turn into a cycle of borrowing when cash-flow problems are addressed with additional advances rather than sustainable financing.
For small-business owners, the key lesson is that access to immediate cash does not necessarily mean access to affordable capital. Before accepting an offer, understanding the repayment terms, total cost and impact on daily operations can be essential to protecting the business and the jobs it supports.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0