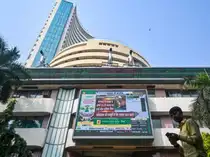
Indian equity markets enter the trading week beginning November 23 with bullish momentum intact after benchmark indices recorded their fourth consecutive weekly advance. The Nifty 50 and BSE Sensex both ended at their highest closing levels in nearly nine months, supported by strong foreign institutional investor (FII) buying, a recovery in the rupee and gains in banking stocks.
The Nifty gained 2.61% during the week ended November 20, closing at 25,800.60, while the Sensex advanced 2.85% to 83,919.71. The rally has brought the Nifty within reach of the psychologically important 26,000 mark, a level that could become the next major test for market participants.
However, the domestic market’s strong performance has come against a difficult global backdrop. Technology and artificial intelligence-related stocks have faced selling pressure in several international markets, while concerns about inflation, interest rates and corporate earnings continue to influence investor decisions.
As a result, the coming week could be important in determining whether the Nifty extends its gains or pauses after its recent advance. Five major factors are likely to influence market direction: foreign investor flows, inflation data, crude oil prices, rupee movements and global market developments.
1. FII Buying: Can Foreign Investors Sustain Their Strong Support?
Foreign institutional investor activity has emerged as one of the strongest supports for the recent recovery in Indian equities. Overseas investors have returned to domestic shares in substantial numbers during November, helping the benchmark indices advance despite weakness across several global markets.
According to market data, FIIs recorded net purchases of approximately Rs 1.12 lakh crore in Indian equities during November up to November 20. The buying streak has continued for four consecutive weeks, providing significant support to large-cap stocks, particularly banks and financial services companies.
On November 20 alone, foreign investors made net purchases worth approximately Rs 10,308 crore, their largest buying session of the week. Their cumulative Investment has helped offset selling by domestic institutional investors (DIIs), who have booked profits during the market’s recovery.
The sustainability of these inflows will be crucial. Continued foreign buying could provide the liquidity needed to push the Nifty through 26,000. It could also support heavyweight stocks that have a significant influence on benchmark movements.
However, the direction of global interest rates, bond yields and international risk appetite could influence whether overseas investors continue allocating money to Indian equities. A reversal in foreign flows could increase selling pressure, particularly after the recent rise in stock prices.
Investors will therefore watch daily institutional activity to assess whether November’s strong foreign buying momentum remains intact.
2. Inflation and Economic Data: Global Numbers Could Influence Market Sentiment
Inflation developments and economic indicators will be another important factor for equities during the week. Investors will monitor data from the United States because it could influence expectations about the Federal Reserve’s future interest-rate decisions.
One of the key releases scheduled for November 25 is the US core Personal Consumption Expenditures (PCE) price index. The measure is closely watched because it provides an indication of underlying inflation trends and is an important input for the Federal Reserve’s monetary policy assessment.
Investors will also examine the second estimate of US third-quarter GDP growth and durable goods orders scheduled for the same day. Together, these releases could provide clues about the strength of economic activity, consumer demand and business investment.
Stronger-than-expected inflation could reinforce concerns that interest rates may remain elevated for longer. Higher borrowing costs can make equities less attractive relative to fixed-income investments and may put pressure on market valuations.
Conversely, signs of moderating inflation without a sharp deterioration in economic growth could improve investor confidence. Such a combination may support risk appetite and encourage further investment in emerging markets, including India.
Domestic investors will also look ahead to India’s second-quarter FY27 GDP growth figures and October industrial production data, both scheduled for November 30. Although these releases fall immediately after the coming trading week, expectations around them could influence sentiment towards the end of November.
3. Crude Oil Prices: Lower Energy Costs Could Support Indian Equities
Crude oil prices remain an important variable for the Indian stock market because India depends heavily on imported energy. Changes in international oil prices can influence the country’s import bill, inflation outlook, currency stability and corporate operating costs.
Recent weakness in crude prices has supported sentiment towards Indian equities. Brent crude declined significantly during November amid hopes of reduced tensions between the United States and Iran and improving energy shipments from the Middle East.
Lower oil prices can benefit several parts of the Indian Economy. They may reduce input costs for industries that depend on petroleum products, ease pressure on transportation and manufacturing expenses, and help limit imported inflation.
For the broader market, a sustained decline in crude prices could also reduce concerns about India’s external balance and provide some support to the rupee. These developments may strengthen investor confidence in domestic equities.
However, the direction of oil prices remains uncertain. Any renewed geopolitical tensions, disruption to supply routes or changes in production policy could trigger a recovery in crude prices.
Investors will pay particular attention to the major OPEC+ meeting scheduled for November 29, when members are expected to review oil production policy. Although the meeting falls after the coming trading week, its potential implications for supply and prices could influence market expectations in advance.
A continued decline in crude oil could support the rally, while a sharp rebound may create fresh concerns about inflation and India’s import costs.
4. Rupee Movement: Currency Strength Could Encourage Foreign Investment
The Indian rupee has strengthened against the US dollar, providing another supportive factor for domestic equities. The currency gained approximately 1.66% during the week ended November 20, closing at around Rs 92.67 per dollar, its strongest level in seven months.
The recovery has coincided with strong foreign investment flows into Indian shares and easing crude oil prices. A stronger rupee can improve the returns foreign investors receive when converting their Indian investments back into dollars, assuming other market factors remain unchanged.
Currency stability can also help reduce uncertainty for companies that depend on imported raw materials, machinery and energy. It may ease some pressure on businesses with significant foreign-currency expenses.
However, the rupee’s direction will depend on several factors, including global dollar movements, foreign capital flows, crude oil prices and international interest-rate expectations.
If the currency maintains its recent gains, it could reinforce the positive sentiment supporting Indian equities. On the other hand, renewed depreciation could increase concerns about imported inflation and foreign investor returns.
Market participants will therefore monitor currency movements alongside institutional investment data to understand whether the supportive conditions behind the recent rally remain in place.
5. Global Market Cues: AI-Related Selling and Central Bank Decisions Remain Risks
Global market developments could create the biggest external challenge for Indian equities during the coming week. Several international markets have experienced sharp declines in technology and artificial intelligence-related stocks as investors reassess valuations, spending plans and the prospects for future returns.
The weakness has raised questions about whether heavy investment in artificial intelligence infrastructure will generate sufficient profits to justify current market valuations. Concerns about higher interest rates have added to the pressure on technology shares, which are often sensitive to changes in borrowing costs and future earnings expectations.
Indian equities have so far demonstrated relative resilience, attracting foreign investment even as several Asian and US markets faced selling pressure. Banking and financial stocks have played a major role in this divergence.
Nevertheless, a prolonged global sell-off could affect investor confidence and encourage international funds to reduce exposure to emerging markets. Any significant deterioration in global risk appetite could therefore interrupt the domestic rally.
Investors will also track the Bank of Korea’s interest-rate decision scheduled for November 26 and Tokyo inflation data due on November 27. These developments could provide additional signals about monetary policy and economic conditions across Asia.
The US Thanksgiving holiday on November 26 will close Wall Street for the day, while US markets are scheduled for an early close on November 27. The shortened trading week could affect global trading activity and liquidity.
Nifty Technical Outlook: 26,000 Becomes the Next Major Test
From a technical perspective, the Nifty’s move above 25,800 has strengthened the positive market structure. The index gained more than 1% on November 20 and closed at 25,800.60, extending its winning streak to four weeks.
Market analysts are watching 26,000 as the immediate psychological resistance level. A decisive move above this mark could open the possibility of the index approaching its previous record-high zone around 26,350–26,373.
However, the recent rally has also pushed the index significantly higher over a relatively short period. Technical indicators suggest that momentum remains strong, but the possibility of consolidation or profit-booking cannot be ruled out.
On the downside, the 25,500 level has emerged as an important support area, followed by the 25,300–25,350 range. A sustained hold above these levels could help preserve the broader positive trend, while a decisive break below them may weaken near-term sentiment.
Market volatility also deserves attention. India VIX, which measures expected market volatility, rose 7.51% to 17.32 on November 20. Its increase alongside rising equity prices suggests that investors are not entirely comfortable with the market’s near-term direction.
Banking Stocks Remain a Major Driver of the Rally
Banking and financial services shares have been among the strongest contributors to the market’s recent gains. The Nifty Bank index advanced approximately 5.9% during the week, while the Nifty PSU Bank and Nifty Private Bank indices gained around 6.7% and 5.7%, respectively.
Large banking stocks have attracted buying interest amid improving sentiment and foreign investment flows. Their strong performance has helped the broader benchmarks advance even as some technology and metal stocks remained under pressure.
Whether banking shares can maintain their momentum will be another factor to watch. Continued participation from financial stocks could support the Nifty’s attempt to cross 26,000. However, profit-booking after the sharp gains may limit the pace of further advances.
Trading Calendar: Important Dates for Investors This Week
The trading calendar will also influence market activity. November futures and options contracts are scheduled to expire on Monday, November 23, having been advanced because of the market holiday later in the week.
- November 23: November futures and options expiry.
- November 24: Indian stock markets closed for Prakash Gurpurb of Sri Guru Nanak Dev Ji.
- November 25: US core PCE inflation, second estimate of US third-quarter GDP and durable goods orders. India’s infrastructure projects flash report is also scheduled.
- November 26: Bank of Korea’s interest-rate decision. US stock markets closed for Thanksgiving Day.
- November 27: Tokyo inflation data and an early close for US markets.
With the November derivatives expiry taking place at the beginning of the week, traders may also watch for changes in positioning and volatility around the 26,000 strike.
Can the Nifty Sustain Its Rally Towards 26,000?
The Indian market enters the week with several supportive factors in place. Strong foreign investment, a firmer rupee, softer crude oil prices and continued strength in banking stocks have helped the Nifty and Sensex outperform several international benchmarks.
However, the rally is approaching an important technical level after four consecutive weeks of gains. Global inflation data, central bank decisions, currency movements and developments in international technology stocks could influence whether investors remain willing to buy at higher valuations.
A sustained move above 26,000 could strengthen expectations of a further advance towards the previous record-high zone. If buying momentum weakens, the market may instead consolidate as investors book profits and reassess valuations.
For now, the five triggers point to a market with positive underlying momentum but meaningful near-term risks. The next direction will depend on whether domestic buying strength and foreign inflows can withstand changing global conditions. Investors should distinguish between a short-term market breakout and a sustained improvement in the broader earnings and economic outlook.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0