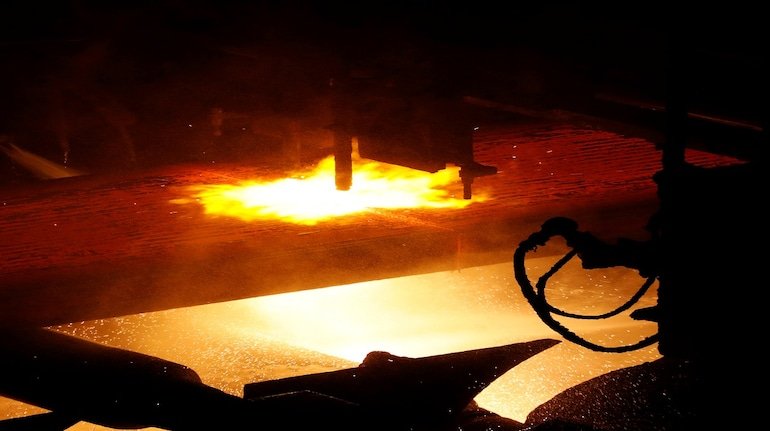
Nomura has maintained its positive outlook on India’s steel sector, retaining its ‘Buy’ recommendations on Tata Steel, JSW Steel and Jindal Steel. The brokerage expects resilient domestic demand, firm steel prices and recent price increases to support industry margins during the second half of FY27.
The assessment comes as Indian steelmakers navigate changing global market conditions, fluctuating raw material costs and rising imports. Although domestic steel prices have eased slightly in recent weeks, they remain close to multi-year highs, providing support to producers.
Nomura believes that price hikes implemented by domestic steel companies should be sufficient to absorb potential increases in raw material costs. This could help protect profitability and maintain earnings momentum through the remainder of FY27.
Nomura Maintains Buy Ratings on Three Steelmakers
Nomura has reiterated its ‘Buy’ recommendations on Tata Steel, JSW Steel and Jindal Steel, identifying the three companies as its preferred picks in the Indian steel sector.
The brokerage’s confidence is based on the industry’s pricing environment and the strength of domestic consumption. Steelmakers have benefited from relatively firm selling prices, while recent increases have improved the ability of companies to manage higher input expenses.
The outlook also reflects the importance of domestic demand at a time when global steel markets remain uneven. India’s consumption growth offers local producers an important source of support, even as international trade flows and export conditions change.
However, the positive sector view does not eliminate company-specific risks. Differences in production capacity, product mix, debt levels, expansion plans and overseas operations can influence the performance of individual steelmakers.
Domestic Steel Prices Remain Near Four-Year Highs
Domestic hot-rolled coil (HRC) prices declined marginally by Rs 50 per tonne week-on-week to Rs 63,800 per tonne during the week ended November 13. Despite the small decline, prices remained close to their highest levels in approximately four years.
Rebar prices recorded a larger weekly decline, falling by Rs 700 per tonne to Rs 63,900 per tonne. Rebar is widely used in construction and infrastructure projects, making its price movement an important indicator for the long-products segment of the steel industry.
The difference in price movements between flat and long steel products has become increasingly significant. Rebar prices have recently gained momentum and outpaced HRC prices, narrowing the domestic flat-long spread.
The spread turned negative at minus Rs 100 per tonne, indicating that rebar was trading slightly above HRC. This shift suggests relatively stronger pricing momentum in long products compared with flat steel during the period.
HRC Margins Improve Ahead of the Second Half of FY27
India’s HRC spot margin stood at approximately Rs 35,640 per tonne in November. This represented an increase of around Rs 2,800 per tonne compared with the second quarter of FY27 and a monthly improvement of Rs 640 per tonne.
Stronger margins are important for steel producers because raw materials such as coking coal and iron ore account for a substantial portion of production expenses. When finished steel prices remain firm while input costs are stable or decline, producers can benefit from improved profitability.
Nomura believes recent domestic price increases provide sufficient protection against potential raw material cost inflation. If selling prices remain resilient, steelmakers could maintain healthier margins during the second half of FY27.
Nevertheless, margins will depend on the relationship between finished steel prices and input costs. A sharp increase in coking coal prices or a sudden correction in domestic steel prices could reduce the benefits of recent improvements.
Global Steel Markets Show Mixed Price Trends
International steel markets presented a mixed picture during the week ended November 13, with prices remaining firm in Europe while Chinese domestic prices recorded a modest decline.
In China, export HRC prices remained unchanged at $505 per tonne week-on-week. Domestic HRC prices declined by $3 per tonne to $477 per tonne.
Chinese export margins increased by $3 per tonne to $210 per tonne, while domestic margins remained stable at approximately $140 per tonne. The difference highlights the importance of export markets for Chinese steel producers, particularly when domestic pricing conditions are weaker.
In Europe, HRC prices increased by 10 euros per tonne to 760 euros per tonne. Margins remained steady at 493 euros per tonne, supported by higher realisations and easing global coking coal costs.
These regional differences matter for Indian producers because international prices influence export competitiveness, import pressure and the pricing decisions of domestic steelmakers. A stronger global market can support local realisations, while cheaper overseas supplies can increase competition within India.
Raw Material Costs Remain an Important Margin Indicator
Imported coking coal prices remained unchanged week-on-week at $261 per tonne. However, prices were still approximately 6% above the average recorded during the second quarter of FY27.
Global iron ore prices remained weak at $86 per tonne, marking their lowest level recorded so far in calendar year 2026. Lower iron ore prices can provide cost relief to steel producers, although the benefit depends on procurement arrangements and the share of imported or domestically sourced material.
In India, NMDC increased lump iron ore prices by Rs 150 per tonne to Rs 5,400 per tonne, effective September 2026. Prices of iron ore fines remained unchanged at Rs 4,500 per tonne.
The difference between coking coal and iron ore trends creates a mixed cost environment for steelmakers. While weaker iron ore prices could support production economics, relatively elevated coking coal prices remain a factor to monitor.
India’s Steel Production and Consumption Continue to Grow
India’s crude steel production increased 1% month-on-month and 0.7% year-on-year to 14.05 million tonnes in October. The increase indicates continued expansion in primary steel output, although the year-on-year growth rate remained relatively modest.
Finished steel production declined 1.3% sequentially to 13.45 million tonnes. However, it remained 2.8% higher than the level recorded in October last year.
Finished steel consumption fell marginally by 0.6% month-on-month to 14.28 million tonnes but increased 6.6% year-on-year. The annual growth in consumption suggests that underlying domestic demand remains resilient despite the small monthly decline.
The difference between monthly and annual trends is important. A sequential decline does not necessarily indicate a sustained slowdown, particularly when consumption remains significantly above the previous year’s level.
Construction, infrastructure development, manufacturing and transportation-related activity are important sources of steel demand. Continued activity in these areas could help domestic producers maintain sales volumes, although the pace of future demand will depend on investment and broader economic conditions.
Rising Steel Imports Create a Competitive Challenge
Despite resilient consumption, India’s steel trade figures revealed a growing challenge for domestic producers. Finished steel imports surged 66% year-on-year and 16.4% month-on-month to 0.76 million tonnes in October.
At the same time, finished steel exports declined 32% year-on-year and 22.6% month-on-month to 0.44 million tonnes. India consequently remained a net importer, with imports exceeding exports by approximately 0.33 million tonnes during the month.
Higher imports can increase competition for domestic steelmakers, particularly when overseas suppliers offer products at competitive prices. This could limit the ability of Indian companies to raise selling prices if imported material becomes more attractive to buyers.
Lower exports also indicate that Indian producers may be facing weaker opportunities in international markets. When export volumes decline, companies may need to rely more heavily on domestic demand to maintain capacity utilisation.
For Nomura’s positive outlook to remain supported, domestic consumption and pricing strength will need to absorb the additional competitive pressure from imported steel.
China’s Steel Trade Activity Remains Uneven
China, the world’s largest steel producer, also recorded changes in finished steel trade during October. Its finished steel exports declined 6.1% month-on-month to 9.85 million tonnes, although they remained 0.7% higher year-on-year.
Finished steel imports fell more sharply, declining 19.7% month-on-month and 21.5% year-on-year to 0.40 million tonnes.
Changes in Chinese exports are important for the wider steel industry because the country’s supply can influence international prices. If Chinese exports remain high, producers in other markets may face greater competition. Conversely, a sustained decline in export volumes could ease some pressure on global steel prices.
For Indian companies, developments in China will remain relevant to export opportunities, domestic pricing and the broader supply-demand balance.
What Nomura’s Outlook Means for Tata Steel, JSW Steel and Jindal Steel
Nomura’s continued preference for Tata Steel, JSW Steel and Jindal Steel reflects its assessment that the Indian steel sector has favourable pricing and demand conditions heading into the second half of FY27.
Tata Steel’s performance will continue to depend on the contribution from its Indian operations as well as conditions in its overseas businesses. European steel prices and operating costs remain important variables for the company.
JSW Steel and Jindal Steel will also be influenced by domestic demand, production volumes, capacity utilisation and raw material expenses. Their ability to manage costs while maintaining competitive selling prices will be important for earnings performance.
Investors should also distinguish between a positive sector outlook and guaranteed share-price gains. Brokerage recommendations represent an assessment based on available information and can change as market conditions, company results and valuation levels evolve.
Key Factors to Watch in the Coming Months
- Domestic steel prices: Whether HRC and rebar prices remain near current levels will influence revenue realisations and margins.
- Raw material expenses: Coking coal and iron ore movements will determine how much cost pressure producers face.
- Import competition: A further increase in finished steel imports could put pressure on domestic pricing and market share.
- Consumption growth: Continued demand from infrastructure, construction and manufacturing will be important for domestic sales volumes.
- Global market conditions: Chinese exports and European steel prices could influence international pricing and India’s trade position.
Indian Steel Sector Outlook: Pricing and Demand Remain Central
Nomura’s decision to retain Buy ratings on Tata Steel, JSW Steel and Jindal Steel reflects confidence in the resilience of India’s steel market. Domestic consumption grew 6.6% year-on-year in October, while HRC prices remained close to their highest levels in four years and spot margins improved compared with the previous quarter.
However, the sector also faces challenges. Rising finished steel imports, weaker exports and elevated coking coal prices could affect profitability if domestic pricing conditions deteriorate.
The next phase of the sector’s performance will depend on whether domestic demand remains strong enough to support steel prices and whether recent price increases continue to offset input-cost pressures.
For investors, the combination of resilient consumption and improving margins offers a constructive outlook, but trade flows, raw material prices and company-specific earnings will remain essential factors when assessing Tata Steel, JSW Steel and Jindal Steel.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0