America faces a growing challenge in how it taxes its wealthiest citizens. A small group of billionaires controls an expanding share of the country’s wealth, while the government struggles to collect sufficient revenue to fund public services and social programmes. The debate extends beyond Tax Policy to questions about economic fairness, political influence and the long-term stability of American democracy.
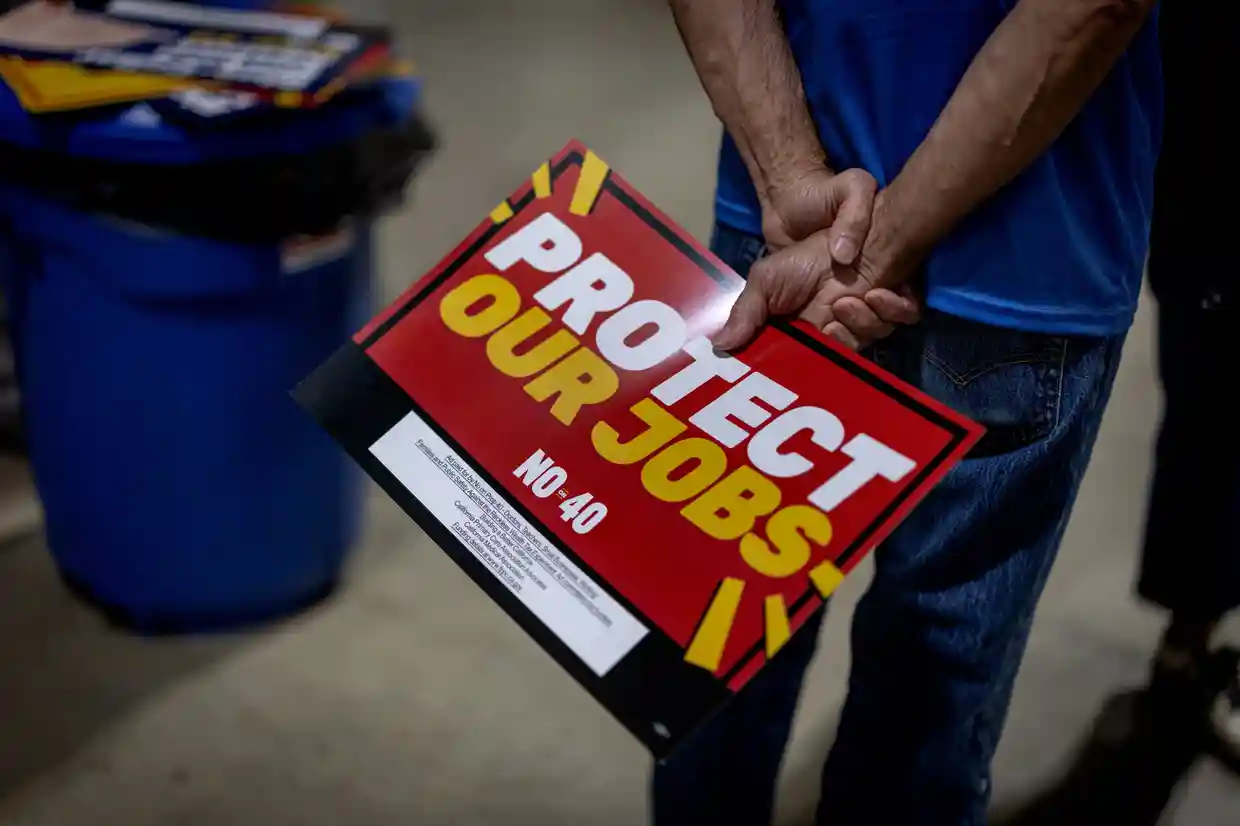
California has become a focal point in this debate with a proposed one-time 5% tax on billionaire wealth. Supporters argue that the measure could generate substantial revenue and encourage other jurisdictions to consider similar policies. Opponents warn that wealthy residents could move elsewhere, reducing tax collections and weakening the state’s finances.
The dispute reflects a wider problem facing governments: how to ensure that the wealthiest individuals contribute adequately to society without creating incentives that undermine the tax system itself. While taxing billionaires presents significant legal, economic and political challenges, the question of who pays for public goods has become increasingly difficult to ignore.
America’s Wealth Concentration Raises Questions About Tax Fairness
The United States has experienced a significant concentration of wealth among its richest households. According to the figures cited in the source material, the wealthiest 1% of Americans hold more than 31% of the country’s total wealth, amounting to approximately $55 trillion in net worth.
This concentration has intensified scrutiny of whether the tax system adequately reflects the financial resources of the richest individuals. Although income taxes apply to earnings, wealthy people can derive much of their economic power from assets that appreciate in value without generating taxable income each year.
High-net-worth individuals may also have access to sophisticated financial advisers and legal structures that help them reduce their tax liabilities. They can hold assets through different entities, manage the timing of income and use differences between tax jurisdictions to limit their exposure.
These options create a gap between the economic resources available to the wealthiest Americans and the income reported for taxation. The result is a debate over whether existing tax rules place a proportionate burden on those who hold the largest fortunes.
The issue is not limited to the amount of revenue the government collects. It also concerns public perceptions of fairness. When ordinary taxpayers believe they contribute a larger share of their income than billionaires, confidence in the tax system and the broader social contract can weaken.
Do Billionaires Pay a Lower Effective Tax Rate?
Research cited in the source material found that 384 of the wealthiest Americans paid approximately 24% of their economic income in taxes in 2025, compared with around 30% for the average taxpayer.
These figures focus on economic income rather than simply the income reported on conventional tax returns. That distinction matters because a substantial portion of billionaire wealth can come from increases in the value of shares, businesses and other assets.
When an asset increases in value but is not sold, the owner may become substantially wealthier without immediately recognising a corresponding taxable capital gain. This can allow fortunes to grow while the tax bill remains disconnected from the increase in net worth.
Reporting by ProPublica has also examined the tax arrangements of some of America’s richest individuals, including Elon Musk, Jeff Bezos, Warren Buffett and Michael Bloomberg. Such reporting has contributed to public debate about the relationship between billionaire wealth, taxable income and the effective rates paid by the ultra-rich.
However, the broader policy challenge is complex. Tax liabilities vary according to the type of income, the timing of asset sales, deductions and applicable laws. The central question for policymakers is whether the rules allow large fortunes to accumulate with too little contribution towards the public services and infrastructure that support economic activity.
California’s Proposed Billionaire Wealth Tax
California is considering an unusual approach to the problem: taxing wealth directly rather than relying exclusively on income and capital gains taxes.
Under the proposal described in the source material, voters are scheduled to consider Proposition 40 in November. The measure would impose a one-time tax of 5% on the wealth of billionaires residing in California on January 1, 2026.
The proposal reflects the argument that if the income of ultra-wealthy individuals is difficult to tax effectively, targeting their accumulated assets could provide an alternative source of public revenue.
According to the figures cited in the article, approximately 260 billionaires lived in California as of early October, with combined wealth approaching $2.5 trillion. A 5% levy on this wealth could theoretically generate about $110 billion, although the amount ultimately collected would depend on the proposal’s implementation, exemptions, legal challenges and taxpayer responses.
Much of the projected revenue would help replace Medicaid funding affected by President Donald Trump’s One Big Beautiful Bill Act, according to the source material. The proposal’s supporters argue that a wealth tax could protect essential services while asking those with the greatest financial resources to make a larger contribution.
Six Nobel Prize-winning economists endorsed the measure in an open letter, describing it as a potential starting point for broader efforts to tax ultra-high-net-worth individuals in other states, at the federal level and internationally.
They argued that the proposal could become an important moment in the wider debate over the relationship between concentrated wealth and democratic government. Nevertheless, the projected revenue and the measure’s long-term effects remain contested.
Why California’s Wealth Tax Faces Opposition
The proposed tax has attracted opposition from prominent California politicians and wealthy residents. Governor Gavin Newsom and Xavier Becerra, a Democrat seeking to succeed him as governor, have expressed concerns about the consequences of imposing a new levy on billionaires.
One major concern is that wealthy residents could move to jurisdictions with lower taxes. If billionaires relocate their residences and business interests, California could lose some of the income tax revenue it currently collects from them.
Technology entrepreneur Sergey Brin has helped coordinate approximately $200 million in opposition to Proposition 40 and in support of two competing ballot measures, Propositions 41 and 42, according to the source material.
The proposed countermeasures would limit the scope of future wealth taxation. One would prohibit retroactive taxes and restrict new taxes on financial assets or other personal property, potentially making it more difficult to impose a levy on accumulated wealth.
Opposition has gained political traction. A September poll cited in the article found that Proposition 40 fell just short of majority support, illustrating the uncertainty surrounding its prospects.
Some wealthy individuals have also taken steps to move business interests or residences outside California. The source material reports that Brin and Google co-founder Larry Page moved various business interests out of the state and purchased homes elsewhere. Former Uber chief executive Travis Kalanick moved to Texas, while investor Peter Thiel moved his residence to Miami.
These developments have strengthened concerns that a wealth tax could prompt a broader exodus of wealthy residents. However, the scale of any resulting revenue losses remains uncertain, and individual relocation decisions do not establish how all affected taxpayers would respond.
Would Billionaires Actually Leave High-Tax States?
The threat of wealthy residents moving to lower-tax jurisdictions is central to the argument against California’s proposal. Yet research cited in the source material suggests that tax changes do not always trigger the large-scale migration predicted by opponents.
After Congress passed the Tax Cuts and Jobs Act in 2017, the limit placed on deductions for state and local taxes was expected to encourage affluent residents to leave high-tax states. A study by a Cornell sociologist and an economist at the US Treasury Department found almost no effect on affluent households’ migration rates during the first year following the change.
The experience of states with high income taxes also complicates the argument that wealthy individuals inevitably leave when taxes rise.
New York City, for example, imposes a top city income tax rate of 3.9%, in addition to a top state rate of 10.9%, according to the source material. Florida, by comparison, has no state individual income tax. Despite the difference, New York remains home to numerous billionaires.
An Oxfam report cited in the article identified 154 billionaires in New York state, with nine of the ten wealthiest residents living in New York City. California, another state with comparatively high taxes, had an even larger billionaire population.
These examples suggest that taxes are only one factor influencing where wealthy people live. Business opportunities, personal relationships, access to skilled workers and the location of major companies can also affect relocation decisions.
However, evidence that some wealthy people remain in high-tax states does not mean a wealth tax would have no effect on migration. A one-time levy on accumulated assets differs from an annual income tax, and its consequences would depend on its design and the choices taxpayers make in response.
Research Warns of Revenue Losses From Wealth Tax Avoidance
Although supporters of Proposition 40 point to the potential for substantial revenue, economists disagree about how much the measure would ultimately raise.
Some estimates assume that tax avoidance and relocation would reduce the taxable pool of wealth by approximately 10%. Other analyses suggest that the financial consequences could be more significant.
A study by economists at Stanford University concluded that California’s proposed tax could raise approximately $30 billion, while lost income tax revenue could cost the state nearly $39 billion in net present value. Under that estimate, the long-term revenue losses could outweigh the money collected through the wealth tax.
The analysis reflects the possibility that wealthy residents could respond by changing their residence, restructuring assets or moving business interests elsewhere. It also draws attention to the difference between the headline amount a tax might theoretically generate and the net fiscal effect after behavioural responses.
Other research has found that the location of very wealthy individuals can be sensitive to estate taxes. Enrico Moretti of the University of California, Berkeley, and Daniel Wilson of the Federal Reserve Bank of San Francisco have examined how changes in estate taxation affect where wealthy individuals choose to live.
Such findings complicate the argument that wealth taxation can provide an easy solution to government funding challenges. Policymakers must consider not only the tax rate but also how the tax interacts with other revenue sources, legal constraints and competition between jurisdictions.
Estate Taxes Reveal the Challenges of Taxing Large Fortunes
The history of state estate taxes provides another example of how tax policy can influence the location of wealthy individuals.
In 2001, President George W. Bush signed the Economic Growth and Tax Relief Reconciliation Act, which included a provision eliminating the federal credit that had offset state estate taxes. The change made estate tax liabilities more dependent on the state in which a wealthy individual lived.
As a result, dying as a resident of a state that imposed an estate tax, such as New York, Pennsylvania or Connecticut, could carry a different tax burden from dying in a state without one, including Texas or Florida.
Research cited in the source material found that by 2010, more than one-fifth of billionaires on the Forbes 400 list who originally lived in states with estate taxes had moved to states without them. Only about 1% had moved in the opposite direction.
Moretti and Wilson estimated that states imposing estate taxes had lost 23 of the 72 Forbes 400 billionaires living there in 2001 by 2017. The wealth of Forbes 400 members subject to state estate taxes fell from approximately $203 billion in 2001 to about $122 billion 16 years later.
The consequences extended beyond potential estate tax collections. When wealthy residents relocate, states may also lose income tax revenue and economic activity associated with their businesses. The prospect of future tax liabilities can also influence where other wealthy people choose to establish residence.
These findings illustrate the difficulties of designing state-level taxes on large fortunes. They also help explain why some economists argue that broader federal reforms may be more effective than individual states acting independently.
Could Consumption Taxes Raise Revenue More Reliably?
Some economists argue that governments could collect revenue more reliably through a less progressive tax structure that relies more heavily on consumption taxes.
Several European countries use value-added taxes (VAT) to finance a substantial share of public spending, including welfare programmes. Consumption taxes can be harder to avoid than some taxes on accumulated wealth because they apply to transactions involving goods and services.
However, VAT and similar consumption taxes can place a heavier burden on lower-income households. People with modest incomes generally spend a larger proportion of their earnings on everyday necessities, leaving them less able to absorb additional taxes on consumption.
That trade-off is central to the debate over how governments should raise revenue. A tax system designed primarily to maximise collections may not distribute the burden in a way that the public considers fair.
Supporters of taxing billionaires argue that allowing the wealthiest individuals to avoid contributing proportionately would undermine confidence in the tax system. Critics counter that poorly designed wealth taxes could drive away taxpayers and ultimately reduce the resources available for public services.
The challenge is therefore to develop policies that raise sufficient revenue while limiting opportunities for avoidance and minimising unintended economic consequences.
Why Federal Tax Reform Could Matter More Than State Measures
California’s proposal has drawn attention partly because it could serve as a model for other states. Yet the difficulties faced by individual states point towards the importance of federal tax reform.
States compete with one another for residents, businesses and investment. A wealthy individual considering relocation can compare tax rates across jurisdictions, potentially moving from a high-tax state to one with lower or no individual income taxes.
California’s top marginal income tax rate is approximately 13.5%, according to the source material, while Florida has no state individual income tax. Such differences create incentives for some taxpayers to consider moving, although taxes are not the only factor influencing those decisions.
Federal tax rules apply across state boundaries and could therefore reduce some of the competitive pressures that complicate state-level reforms.
One option would be to close loopholes in federal estate tax rules that allow large fortunes to pass between generations with limited taxation. Under current rules, unrealised capital gains can sometimes accumulate without being taxed during an owner’s lifetime and may receive a reset in their tax basis when inherited, reducing the capital gains tax that heirs would otherwise face when selling the assets.
Reforming these provisions could make it harder for wealth to accumulate across generations without generating corresponding tax liabilities. Another option would be to increase taxes on capital income to reduce the disparity between the taxation of investment returns and labour income.
Economists Erick Zwick of the University of Chicago and Owen Zidar of Princeton University have proposed restoring the tax schedule to levels associated with the Clinton administration. The estimate cited in the source material suggests that such a change could raise approximately $5 trillion over a decade.
These proposals illustrate that taxing large fortunes does not depend on a single wealth tax. Governments can also examine capital gains, estate taxes, deductions and other provisions that influence how much wealthy households contribute over time.
Tax Revenue and the Future of American Democracy
The debate over billionaire taxation is ultimately about more than government revenue. It concerns the relationship between private wealth, public institutions and the principle that citizens should contribute to the functioning of society.
Governments need revenue to maintain infrastructure, support healthcare programmes, provide public services and carry out other responsibilities. When a large share of economic resources remains outside the effective reach of taxation, the burden can fall more heavily on workers and households whose income is easier to measure and tax.
Persistent perceptions of unequal treatment can weaken trust in public institutions. They can also intensify concerns that economic power is translating into political influence, allowing wealthy individuals to shape policies that protect their financial interests.
The source material argues that taxation has historically served as a way to prevent the emergence of a hereditary aristocracy in which economic and political power passes from one generation to the next. From this perspective, effective taxation of wealth is part of maintaining a society in which opportunity does not depend entirely on inherited resources.
However, the effectiveness of any policy depends on its design and implementation. A tax that produces less revenue than expected or creates significant unintended consequences may fail to achieve its stated goals. Equally, abandoning efforts to tax accumulated wealth because avoidance is possible could leave existing inequalities largely unaddressed.
The policy challenge is to establish rules that are enforceable, economically sustainable and consistent with public expectations of fairness.
The Political Challenge of Reforming the US Tax System
Significant changes to the taxation of billionaires would require overcoming substantial political obstacles. Over recent decades, US tax debates have frequently focused on reducing tax rates, creating a difficult environment for proposals that would increase the burden on wealthy individuals.
The federal government collects a smaller share of gross domestic product in taxes than it did at the beginning of the century, according to the figures cited in the source material. More than two percentage points of the decline of almost three percentage points were attributable to federal revenue.
The article also notes that the average central government in the Organisation for Economic Co-operation and Development collects approximately twice as much in taxes as a share of GDP as the US federal government.
These comparisons point to a broader question about the level of revenue the United States chooses to collect and the public services it expects to finance. Increasing collections would require political agreement on both the distribution of the tax burden and the government’s spending priorities.
Supporters of billionaire taxation argue that the country cannot maintain public services and restore confidence in its institutions without asking the wealthiest citizens to contribute more. Opponents warn that tax increases could encourage relocation, reduce investment or create legal uncertainty.
Finding a workable balance requires policymakers to examine the evidence on revenue, avoidance and migration rather than relying solely on either the projected gains or the most pessimistic forecasts.
Conclusion: Can America Tax Billionaires Without Losing Revenue?
California’s proposed billionaire wealth tax has brought a difficult policy question into sharp focus: how can governments tax accumulated fortunes when wealthy individuals can move assets, change residence and use complex financial arrangements to reduce their liabilities?
The proposal could generate substantial revenue if it passes and is implemented successfully, but estimates of its likely fiscal impact vary considerably. Concerns about relocation, legal challenges and lost income tax collections mean that the final outcome cannot be determined from the headline tax rate alone.
Evidence from estate taxes and other tax changes suggests that wealthy individuals sometimes respond to differences between jurisdictions. Yet research on migration also indicates that higher taxes do not automatically trigger a mass departure of affluent residents.
These competing findings reinforce the case for careful tax design. Closing loopholes, reforming estate and capital gains taxation, and considering broader federal measures could offer alternatives or complements to a one-time state wealth tax.
Ultimately, the debate concerns how the United States balances economic incentives with the need to finance public goods and maintain confidence in its institutions. Taxing billionaires is not a guaranteed solution to every fiscal challenge, but the question of how the wealthiest Americans contribute to society remains central to the country’s debate over fairness, opportunity and democratic accountability.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest World on thefoxdaily.com.

COMMENTS 0