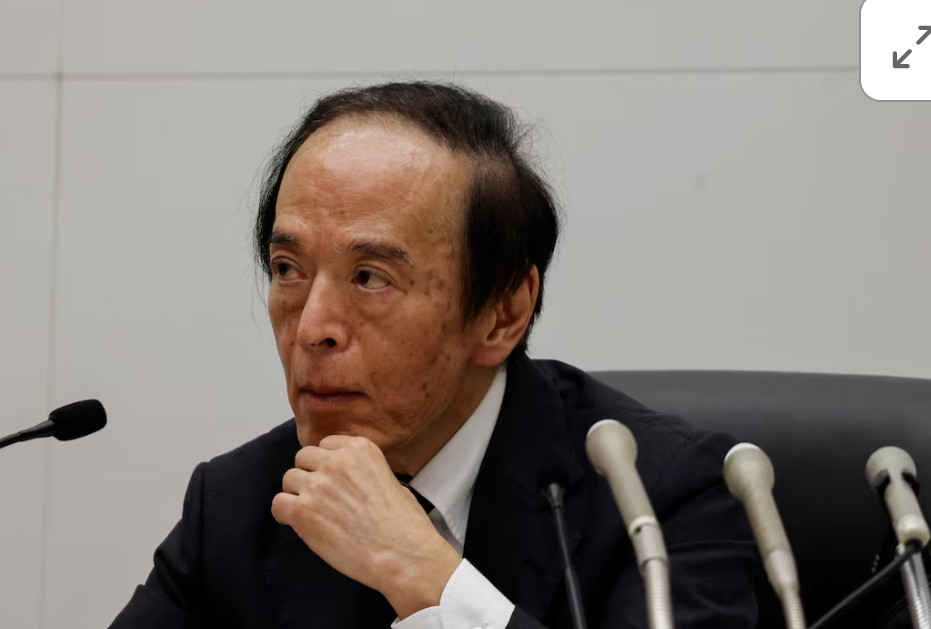
The Bank of Japan raised its policy rate to 1.25% on September 18, 2026, taking borrowing costs to their highest level in 31 years. The decision was widely expected, but the yen weakened after two board members opposed the increase and the central bank avoided giving a clear signal about the timing of its next rate hike.
The BOJ’s latest move marks another step away from Japan’s decades-long era of ultra-low interest rates. At the same time, persistent inflation, elevated oil prices and rising import costs are forcing policymakers to balance price stability against the risk of tightening financial conditions too quickly.
BOJ Raises Rate to 1.25% in 7-2 Vote
At its two-day policy meeting ending Friday, the Bank of Japan increased its policy rate from 1% to 1.25%. The decision passed by a 7-2 vote.
Board members Toichiro Asada and Ayano Sato voted against the increase. Their dissent was important for financial markets because investors had largely expected the rate hike itself but were less certain about how strongly the entire board would support further monetary tightening.
| BOJ Policy Detail | September 2026 Decision |
|---|---|
| Previous policy rate | 1.00% |
| New policy rate | 1.25% |
| Increase | 25 basis points |
| Voting result | 7-2 |
| Dissenting members | Toichiro Asada and Ayano Sato |
| BOJ Governor | Kazuo Ueda |
Why Did the Yen Fall After a Rate Hike?
Normally, a higher interest rate can support a country’s currency because it can make assets denominated in that currency more attractive. However, the Japanese yen moved in the opposite direction after the BOJ announcement.
The yen fell to around 156.91 per dollar as investors focused on the two dissenting votes and the absence of stronger guidance about another increase.
The market had already largely priced in the 25-basis-point hike. Therefore, the key question was not simply whether the BOJ would raise rates, but what the decision said about the future pace of tightening.
Hirofumi Suzuki, chief FX strategist at SMBC, said the dissenting votes were somewhat unexpected and had tempered expectations for additional hikes. The result therefore created a more cautious interpretation of the BOJ’s policy direction.
Two Dovish Dissenters Change the Market Interpretation
The 7-2 vote matters because monetary policy decisions communicate more than the headline rate. The distribution of votes can provide investors with information about how policymakers view inflation, growth and the appropriate pace of future tightening.
Asada and Sato’s opposition indicates that there was still meaningful disagreement within the policy board about raising borrowing costs at this meeting.
That does not necessarily mean that future rate increases are off the table. Instead, it highlights the uncertainty surrounding the pace at which the BOJ can move toward a more neutral monetary-policy setting.
Investors are therefore watching Governor Kazuo Ueda’s press conference for additional information about the bank’s reaction function and how it will evaluate inflation and economic conditions before its next decision.
Japan’s Inflation Pressure Is Broadening
The BOJ’s decision comes as price pressures are becoming more widespread across the Japanese economy.
The central bank said wholesale inflation remains elevated and that higher costs in business-to-business transactions are increasingly feeding through to consumer prices. It also said underlying inflation has been approaching the BOJ’s 2% target.
Companies have continued passing higher wage and input costs on to consumers, while inflation expectations have also increased.
Core consumer inflation remained near the BOJ’s target in August, with businesses continuing to raise prices for food and other grocery products.
This creates a difficult policy environment. The BOJ wants inflation to remain consistent with its 2% objective, but it also needs to consider whether higher borrowing costs could unnecessarily weaken domestic demand.
Oil Prices Have Made the BOJ’s Job More Difficult
Energy prices have become an important part of the inflation debate in Japan. The sharp rise in oil prices linked to the Iran conflict has increased concerns about imported inflation.
Japan imports a large proportion of the energy it consumes, meaning higher global oil prices can quickly increase costs for businesses, transportation and households.
A weaker yen can amplify that effect because imported commodities become more expensive in local-currency terms. This creates an unusual policy challenge: the BOJ may face pressure to tighten policy partly because of external energy costs rather than purely domestic demand.
Policymakers therefore need to distinguish between temporary energy-driven inflation and more persistent price increases caused by wages, expectations and domestic economic conditions.
BOJ Rate Is Moving Toward the Neutral Range
The latest increase takes the BOJ’s policy rate closer to the central bank’s estimated range for Japan’s nominal neutral interest rate.
The BOJ estimates that range at approximately 1.1% to 2.5%. A neutral rate is broadly understood as a level that neither significantly stimulates nor restricts economic activity, although the exact level cannot be observed directly and must be estimated.
At 1.25%, the BOJ is therefore no longer operating at extremely low rates. However, the rate remains below those of several major central banks.
| Central Bank | Policy Rate Around September 2026 | Key Context |
|---|---|---|
| Bank of Japan | 1.25% | Continuing gradual normalisation |
| European Central Bank | 2.50% | Responding to persistent inflation pressures |
| U.S. Federal Reserve | 3.75%-4.00% | Higher policy rate than Japan |
The difference in interest rates remains relevant for currency markets because investors compare expected returns across economies.
Japan Is Still Moving Away From Ultra-Low Rates
The September decision is part of a longer transition in Japanese monetary policy.
The BOJ ended its decade-long stimulus framework in 2024 and has subsequently raised interest rates several times. The central bank has generally moved more slowly than its U.S. and European counterparts because Japanese policymakers have wanted stronger evidence that inflation can remain sustainable around the 2% target.
For decades, extremely low Japanese interest rates contributed to the yen’s role as a funding currency in global financial markets. Investors could borrow cheaply in yen and deploy funds into assets offering higher returns elsewhere.
As Japanese rates rise, that environment gradually changes. The cost of yen-based funding increases, potentially influencing global currency and asset-market flows.
What Could Happen to the Yen Next?
The direction of the yen will depend on the difference between Japanese and overseas interest rates as well as expectations about future BOJ policy.
If investors conclude that the BOJ will continue raising rates at a relatively steady pace, the interest-rate gap with other major economies could narrow. That could provide support to the yen.
Conversely, if the BOJ communicates that further hikes will be slow or dependent on additional inflation evidence, the yen could remain under pressure if U.S. and European rates stay substantially higher.
The September decision demonstrates why currency markets respond not only to actual interest-rate changes but also to expectations about the next several policy meetings.
What the BOJ Said About Future Inflation
The central bank warned that there is a risk underlying inflation could deviate from its 2% target. It also pointed to rising inflation expectations and continued price pass-through by companies.
These comments indicate that inflation remains central to the BOJ’s decision-making framework.
However, the bank has not committed itself to a predetermined series of rate increases. Officials have repeatedly indicated that future moves will depend on economic developments, the inflation outlook and the effects of previous rate hikes on financial conditions.
This approach leaves investors with considerable uncertainty about the timing of the next increase.
Markets Await Governor Ueda’s Press Conference
Governor Kazuo Ueda’s press conference is likely to receive significant attention because the policy statement itself did not provide an unambiguous signal of an imminent additional hike.
Investors will be looking for clues about several questions:
- How concerned is the BOJ about the recent rise in energy prices?
- Does the central bank view underlying inflation as sustainably close to 2%?
- How does the BOJ assess the current policy rate relative to neutral?
- How much weight will policymakers place on wage growth?
- Could another rate increase come soon if inflation remains elevated?
- How does the BOJ assess the impact of yen weakness on imported inflation?
The answers could influence the yen, Japanese government bonds and domestic equities.
Japan’s Rate Path Is Still Expected to Rise
Analysts surveyed by Reuters expect the BOJ’s policy rate to reach 1.5% by the end of March 2027 and approximately 1.75% in the second quarter of 2027. Most respondents viewed at least 1.75% as a possible eventual terminal rate.
These are market and analyst expectations rather than commitments from the BOJ. Actual policy decisions will depend on inflation, wages, economic growth, financial conditions and developments in global energy markets.
The difference between expected and actual policy moves could remain an important source of volatility for the yen.
How Higher Japanese Rates Could Affect Households
Higher interest rates can affect Japanese households through borrowing and savings channels.
For borrowers, increased rates can gradually raise financing costs, depending on the type of loan and its interest-rate structure. For savers, higher rates can improve returns on deposits and other interest-bearing assets.
The broader economic effect depends on the balance between these two forces. If inflation remains elevated while wage growth improves, the BOJ may have more room to normalise rates. If higher borrowing costs begin to weaken consumption or investment significantly, policymakers could move more cautiously.
Impact on Global Markets
The BOJ’s policy direction matters beyond Japan because the yen has long played an important role in global funding markets.
A sustained increase in Japanese interest rates could change the relative attractiveness of overseas investments for Japanese investors. It could also influence currency hedging costs and global bond-market flows.
At the same time, Japan’s policy divergence with the United States and Europe remains substantial. The Fed’s policy rate is still considerably higher than Japan’s, while the ECB’s rate is also above the BOJ’s level.
This means the global market impact of BOJ tightening will depend heavily on what other central banks do at the same time.
Key Factors to Watch After the September BOJ Decision
| Factor | Potential Market Importance |
|---|---|
| Governor Ueda’s guidance | Could reshape expectations for the next rate increase. |
| Japanese inflation | Persistent inflation near or above target could support further normalisation. |
| Oil prices | Higher energy costs could increase imported inflation. |
| Yen exchange rate | Yen weakness can raise import costs and influence inflation. |
| Wage growth | Stronger wages could make inflation more durable. |
| Global central-bank policy | U.S. and European rate decisions will affect Japan’s interest-rate differential. |
| Economic growth | Weakening domestic activity could encourage a slower tightening pace. |
Conclusion
The Bank of Japan’s decision to raise its policy rate to 1.25% represents another important step in Japan’s monetary-policy normalisation and takes rates to their highest level in 31 years.
Yet the immediate market reaction shows that the headline rate increase was only part of the story. The 7-2 vote, including two dovish dissenters, reduced expectations for an aggressive sequence of future hikes and contributed to a weaker yen.
The BOJ is now navigating a complicated combination of domestic inflation, higher energy costs, yen weakness and global monetary-policy shifts. Its future decisions will depend on whether price pressures become sufficiently persistent to justify additional tightening without causing excessive economic strain.
For financial markets, Governor Ueda’s guidance, Japanese inflation and wage data, oil prices and the interest-rate gap with the United States and Europe will remain the most important signals for understanding the yen and the next phase of BOJ policy.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0