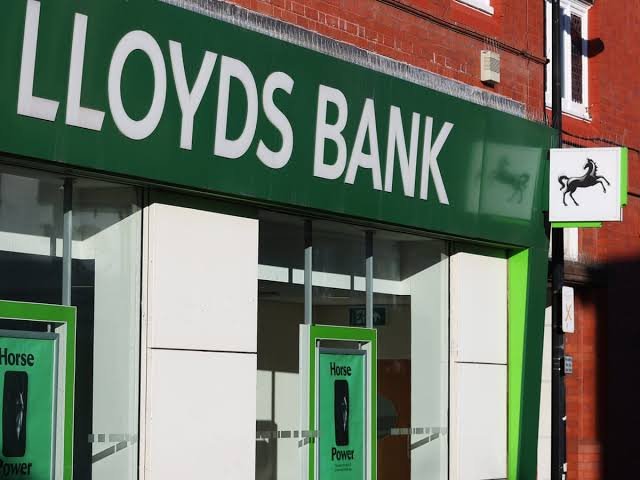
A senior executive at Lloyds Banking Group has criticised the UK government’s decision to link higher bank taxes to household energy bill support, warning that extending the levy could undermine the banking sector’s ability to support economic growth and remain internationally competitive.
William Chalmers, Lloyds’ chief financial officer, said he hoped the proposed increase in the bank surcharge would remain temporary. His comments came after Chancellor John Healey announced plans to double the surcharge from 3% to 6% for 15 months from January, with the additional revenue intended to fund immediate support for household Energy Bills.
The debate highlights the challenge facing the government as it seeks to ease pressure on households while maintaining a tax environment that encourages investment, lending and economic expansion.
Lloyds Warns Against Extending the Bank Tax Increase
Chalmers acknowledged that the UK Economy was facing a challenging environment but argued that the banking sector’s contribution to economic growth should remain a priority when policymakers consider tax changes.
He said banks provide essential financial services to businesses, households and communities, while lending can help companies invest, expand operations and create economic opportunities. According to Chalmers, the sector must also remain internationally competitive to continue supporting the UK economy effectively.
“Ultimately, it is important that the UK banking sector is able to deliver banking services to businesses and households and communities in a cost-effective way, in order to promote UK growth,” he said during an earnings call on Thursday.
He added that Lloyds hoped the tax increase would be temporary and would not create uncertainty for businesses planning long-term investments.
Chalmers’ remarks reflect concerns across the banking industry that temporary tax measures introduced during periods of economic pressure can become permanent. Banks typically make lending and investment decisions over extended periods, meaning uncertainty about future taxation can complicate financial planning.
Why the Government Is Raising the Bank Surcharge
Chancellor John Healey announced the proposed increase less than 24 hours before Chalmers made his comments. The bank surcharge, an additional tax paid by banks on top of corporation tax, is set to rise from 3% to 6% for a 15-month period beginning in January.
Healey described the measure as time-limited and said it would help pay for immediate support on energy bills. The Treasury has promised to legislate for the 15-month restriction through the financial bill.
The policy is intended to provide the government with additional revenue to address the pressure that energy costs place on UK households. Higher household energy bills can reduce disposable income, leaving consumers with less money for other goods and services.
However, Chalmers questioned whether bank taxes should be directly linked to energy prices, arguing that the relationship between the two was not clear.
“We hope this tax rate is limited,” he said, adding that he did not see an obvious connection between energy prices and bank taxation.
He argued that higher energy costs made it even more important for banks to continue lending to the wider economy and supporting growth. In his view, a stronger economy would be better positioned to withstand the effects of energy price increases.
Banking Industry Fears a Temporary Levy Could Become Permanent
Although the Treasury has pledged to establish a 15-month limit for the surcharge increase, some senior bankers and industry lobbyists have questioned whether the restriction would remain effective if another energy crisis emerged.
The concern is that the government could face renewed pressure to extend the tax if energy prices remain elevated or households require further financial assistance after the initial period expires.
Chalmers warned against allowing an emergency measure to become a lasting feature of the UK’s tax system. For Lloyds, a stable and predictable tax regime is important for determining how much capital it can allocate to lending, investment and other activities.
Uncertainty over future taxation can affect how financial institutions assess the returns on long-term investments. Banks may also need to consider whether additional costs could influence the pricing of financial products or their appetite for particular types of lending.
However, the eventual effect of the surcharge will depend on how banks respond to the higher tax and how broader economic conditions develop. The proposed increase does not automatically mean that lending will decline or that customers will face higher borrowing costs.
Spain Provides an Example of an Extended Bank Levy
Some banking industry representatives have pointed to Spain as a warning about the potential longevity of temporary taxes introduced during a cost-of-living crisis.
Spain introduced a windfall tax on banks in 2022 to help alleviate cost-of-living pressures. The measure was initially designed to last two years but was subsequently extended for another three years. The levy on the country’s largest banks also increased from 4.8% to 7%.
The experience has fuelled concerns among UK banking executives that the surcharge increase could be extended if energy prices remain high or the government faces further pressure to support households.
However, Spain’s policy decisions do not establish that the UK government will follow the same approach. The Treasury has said the proposed UK increase will be temporary, and its duration will depend on the legislation and any subsequent policy decisions.
The comparison nevertheless illustrates why financial institutions are seeking clear limits on emergency tax measures. Banks want to understand whether the additional levy will expire as planned or become a longer-term cost that must be incorporated into future business decisions.
Lloyds Highlights Its Contribution to Government Revenue
Chalmers also emphasised Lloyds’ contribution to public finances, arguing that the bank already pays substantial amounts in tax.
“We are a major taxpayer,” he said, adding that Lloyds had paid around £1.8bn in corporate taxes year to date.
His comments underline the tension between the government’s need to raise revenue and the banking sector’s preference for a predictable tax framework.
For policymakers, the additional surcharge could help fund immediate household support during a period of elevated energy costs. For banks, however, the main concern is whether the measure could create uncertainty over the longer-term costs of operating in the UK.
The debate also raises broader questions about how governments should distribute the financial burden of economic crises. Additional taxes can generate revenue for public programmes, but policymakers must also consider their potential effects on investment, competition and the availability of financial services.
Lloyds Reports Third-Quarter Pre-Tax Profits of £2.3bn
Chalmers’ comments came as Lloyds Banking Group reported that its third-quarter pre-tax profits had almost doubled compared with the same period a year earlier.
The bank recorded pre-tax profits of £2.3bn, up from £1.2bn a year earlier. However, the comparison was significantly affected by costs recorded in the previous year, when Lloyds set aside an additional £800m for compensation related to the motor finance scandal.
The impact of those earlier provisions means the increase in reported profits should be viewed in context. While the latest figures show a substantial improvement in year-on-year earnings, part of the rise reflects the absence of a similar exceptional charge in the comparison period.
Lloyds also reported a 10% increase in net interest income, a key measure of banking profitability that captures the difference between interest earned on lending and other assets and interest paid to depositors and funding providers.
The increase suggests that the bank continued to benefit from the interest-rate environment. Net interest income is particularly important for traditional lenders because changes in borrowing rates and deposit costs can significantly affect earnings.
Higher Energy Prices Add to the Banking Sector’s Challenges
Inflation expectations have been influenced by higher fuel prices linked to the conflict in the Middle East, adding uncertainty to the outlook for interest rates and the wider UK economy.
When energy prices rise, households can face higher living costs while businesses encounter increased expenses for transport, production and operations. These pressures can influence inflation, consumer spending and companies’ willingness to invest.
For banks, the effects can be mixed. Higher interest rates may support net interest income in some circumstances, depending on how quickly lending rates and deposit costs adjust. However, expensive borrowing can also put pressure on customers, weaken demand for loans and increase the risk of missed repayments.
Energy-related inflation could therefore affect banks through several channels, including interest-rate movements, loan demand and the financial health of borrowers.
This economic uncertainty helps explain Lloyds’ emphasis on a predictable tax regime. The bank argues that lenders need the capacity to continue supporting households and businesses during periods of financial pressure rather than facing additional uncertainty over their future tax liabilities.
What the Bank Surcharge Means for Businesses and Households
The proposed surcharge increase brings two policy priorities into focus: providing immediate assistance to households struggling with energy costs and preserving the banking sector’s ability to finance economic activity.
For households, the government intends to use the additional revenue to help fund energy bill support. For banks, the central question is whether the higher tax will remain limited to the announced 15-month period.
Businesses could also be affected indirectly because banks are an important source of finance for working capital, expansion and investment. Any change in lending conditions could influence companies’ ability to manage costs and pursue growth, although the actual impact of the surcharge will depend on banks’ responses.
The government must therefore weigh the immediate benefits of additional revenue against potential longer-term effects on investment and competitiveness. Meanwhile, banks will be watching whether the proposed time limit is maintained and how future energy prices influence economic policy.
Chalmers’ intervention makes clear that Lloyds wants the surcharge increase to remain temporary. As the proposal moves through the legislative process, the duration of the measure and its implications for the UK’s banking environment will remain important issues for lenders, businesses and policymakers.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.

COMMENTS 0