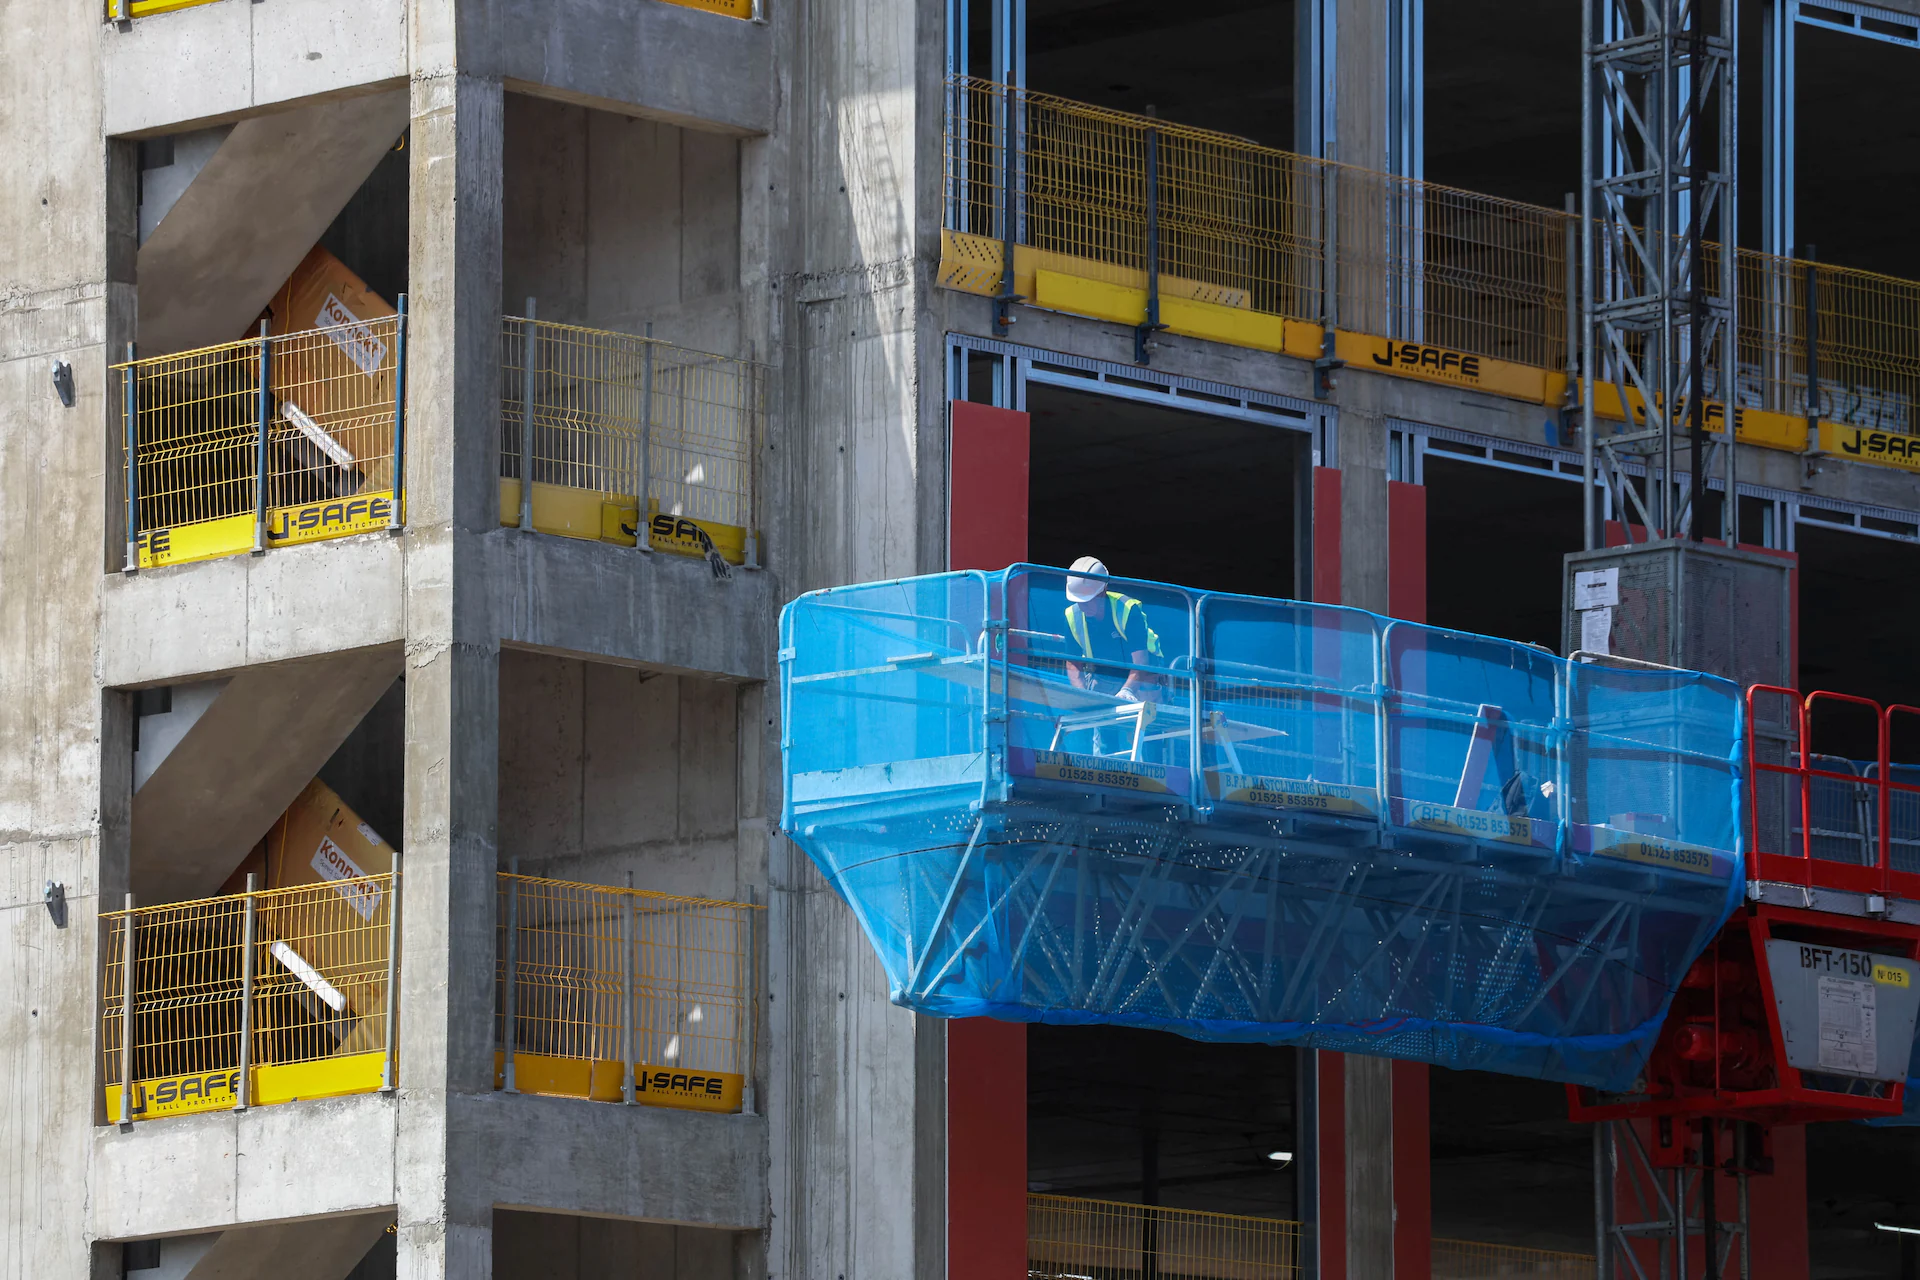
The UK’s jobs market has shown tentative signs of recovery, with wage growth picking up and payroll employment figures improving, according to data released on October 20, 2026. The latest figures could strengthen the case for the Bank of England (BoE) to raise interest rates at its next policy meeting as it assesses whether rising energy costs are feeding into broader Inflation.
Average weekly earnings, excluding bonuses, increased by 3.7% in the three months to August compared with the same period a year earlier, the Office for National Statistics (ONS) reported. The increase exceeded the 3.6% growth forecast by economists in a Reuters poll and extended the gradual recovery in pay growth from its low earlier this year.
Separate figures showed that the number of employees on company payrolls increased by 13,000 in September, according to a preliminary measure from Britain’s tax authority. The unemployment rate also declined to 4.7% in the three months to August, its lowest level since mid-2025.
These developments suggest that conditions in the British labour market may be stabilising after a period of weakness. However, the picture remains mixed. Job vacancies continued to decline, falling below 700,000 for the first time since the three months to April 2021.
For the Bank of England, the central question is whether stronger wages and employment reflect a sustainable improvement in economic conditions or could contribute to persistent inflation. The answer may influence its decision on interest rates next month, particularly as policymakers monitor the effects of the energy price shock linked to the Iran war.
UK Wage Growth Rises to 3.7%
Average weekly earnings excluding bonuses grew by 3.7% year on year in the three months to August, according to the ONS. This marked a further increase from the recent low of 3.4% recorded earlier in the year.
The result was slightly stronger than expected. Economists surveyed by Reuters had forecast wage growth of 3.6%, while the figure for the three months to July was revised upward to 3.6%.
The gradual increase in pay growth is important because wages are a major factor in the Bank of England’s assessment of domestic inflation. When employees receive higher pay, household incomes can improve, potentially supporting spending on goods and services.
However, wage growth can also influence inflation through business costs. If companies face rising payroll expenses and respond by increasing the prices of their products or services, stronger pay growth can contribute to persistent inflationary pressure.
The relationship is not automatic. Businesses may absorb some additional labour costs, improve productivity or adjust other expenses rather than raise prices. The impact on inflation depends on wider economic conditions, including consumer demand and companies’ ability to pass costs on to customers.
The latest figures therefore provide a useful but incomplete signal for policymakers. Stronger wage growth could indicate that labour-market conditions are becoming more resilient, but it also means the BoE must continue assessing whether pay increases are consistent with bringing inflation under control.
Payroll Employment Increases in September
Another encouraging signal came from the preliminary payroll employment figures. The number of people on company payrolls rose by 13,000 in September, according to data from Britain’s tax authority.
The figure for August was also revised. Instead of the previously estimated decline of 26,000, the updated data showed an increase of 1,000 employees.
The revisions change the recent picture of employment, suggesting that payroll numbers were more resilient than the initial estimates indicated. The September increase adds to evidence that the labour market may be stabilising, although a single month’s improvement does not establish a sustained recovery.
Payroll employment measures provide a useful indicator of changes in the number of employees receiving pay through the tax system. However, they do not capture every aspect of the labour market, including the full range of self-employment and changes in hours worked.
The figures also need to be considered alongside other indicators, particularly vacancies and unemployment. A rise in payroll employment can coexist with a weaker hiring environment if businesses are recruiting more cautiously or reducing the number of new positions they advertise.
For the Bank of England, the latest increase could indicate that employment is holding up better than previously thought. If that resilience is accompanied by persistent wage pressures, it could influence the central bank’s assessment of the appropriate level of interest rates.
Unemployment Rate Falls to 4.7%
The UK’s unemployment rate declined to 4.7% in the three months to August, reaching its lowest level since mid-2025, according to the ONS.
The decline adds to the positive signals from wage growth and payroll employment. Together, the figures suggest that the deterioration in labour-market conditions may be easing, even though businesses are advertising fewer vacancies.
However, the unemployment figure comes with an important qualification. The ONS is overhauling the survey used to calculate the unemployment rate, a factor that matters when interpreting the latest estimates and comparing them with previous periods.
Labour-market indicators can also move in different directions. Unemployment may fall even as vacancies decline, depending on changes in hiring, redundancies, labour-force participation and the number of people actively seeking work.
For that reason, the latest unemployment figure should not be interpreted in isolation as proof that the UK labour market has returned to strong conditions. Instead, it forms part of a broader picture in which some indicators are improving while others continue to signal weakness.
Job Vacancies Fall Below 700,000
Despite the improvement in some employment measures, job vacancies continued to decline. The number of vacancies fell to 691,000 in the three months to September, down from 704,000 in the three months to August.
This was the first time vacancies had dropped below 700,000 since the three months to April 2021, highlighting the extent of the slowdown in advertised hiring opportunities.
Vacancy numbers are important because they provide an indication of how actively employers are seeking workers. When vacancies decline, businesses may be becoming more cautious about expansion, delaying recruitment or trying to manage costs with their existing staff.
A reduction in vacancies can also ease competition among employers for workers, potentially limiting the pace of future wage increases. If fewer businesses are competing to recruit employees, workers may have less leverage to secure substantial pay rises when changing jobs.
That could eventually reduce some of the wage pressures that concern the Bank of England. However, the relationship between vacancies and wages is not immediate, and pay growth can remain elevated even as recruitment demand weakens.
The latest figures therefore complicate the outlook for monetary policy. Stronger pay growth and payroll employment could point to a more resilient labour market, while falling vacancies suggest that employers remain cautious.
Why the Bank of England Is Watching Wage Growth
The Bank of England is assessing whether the energy price shock linked to the Iran war is spreading into wider inflation across the UK Economy. Policymakers are particularly interested in whether higher living costs are prompting workers to demand stronger pay increases and whether those demands could lead businesses to raise prices.
Energy shocks can affect inflation through several channels. Higher energy costs may directly increase household bills and transport expenses, while businesses can face higher production, distribution and operating costs.
If those increases persist, workers may seek higher wages to protect their purchasing power. Companies may then pass some of their higher labour costs on to consumers, potentially extending the effects of the original energy shock beyond fuel and energy prices.
This process is one reason central banks monitor wage growth when assessing the outlook for inflation. Policymakers need to distinguish between a temporary increase in prices caused by external factors and a more persistent pattern in which wages, demand and business pricing decisions reinforce one another.
The latest UK data provides mixed evidence. Wage growth has strengthened, which may concern policymakers if it signals that domestic inflation pressures are becoming more persistent. Yet the decline in vacancies suggests that employers are not competing as aggressively for workers as they were during stronger labour-market conditions.
The Bank of England will need to consider these indicators alongside inflation data, economic growth and other measures of demand before deciding whether a rate increase is necessary.
Could the Bank of England Raise Interest Rates Next Month?
The latest labour-market figures could bolster the case for a Bank of England interest rate increase next month, but they do not guarantee that policymakers will raise borrowing costs.
Stronger wage growth may suggest that domestic price pressures remain significant, particularly if companies continue passing labour and energy costs on to consumers. The increase in payroll employment and the lower unemployment rate could also indicate that the economy is holding up better than some previous estimates suggested.
However, falling job vacancies provide a counterpoint. The decline suggests that employers are advertising fewer positions, which could indicate caution about future demand or operating costs.
The BoE must weigh the risk of persistent inflation against the possibility that tighter monetary policy could weaken economic activity. Raising interest rates generally increases borrowing costs for households and businesses, although the effects depend on the type of loan, financial arrangements and how quickly changes in market rates feed through.
Higher borrowing costs can help contain inflation by reducing demand across the economy. But if businesses and consumers are already under pressure, additional tightening could make it harder for companies to invest and households to spend.
The decision will therefore depend on the full set of economic evidence available to policymakers. The latest figures strengthen the case for taking wage pressures seriously, but the weakness in vacancies means the labour-market outlook remains uncertain.
Sterling Rises After the Labour-Market Data
The British pound rose against the US dollar after the latest data was published, according to the supplied Reuters report.
Currency markets often react to economic releases that may influence expectations for interest rates. If investors believe stronger wage growth makes a rate increase more likely, they may reassess the expected return on assets denominated in that currency.
However, a rise in sterling immediately after a data release does not establish that the Bank of England will raise rates. Exchange rates respond to a range of factors, including expectations for monetary policy, economic growth, global market conditions and developments affecting other major currencies.
The currency’s reaction indicates that the figures were relevant to market expectations, but the longer-term direction of sterling will depend on how incoming economic data shapes the outlook for UK interest rates and growth.
Investors will continue to assess whether wage growth remains elevated, whether employment conditions improve further and whether the energy shock creates broader inflationary pressure. Those factors will help determine how markets interpret the Bank of England’s next policy decision.
What the Latest Figures Mean for Workers and Businesses
For workers, stronger average pay growth may provide some support for household incomes as the cost of living remains an important economic concern. The extent to which employees benefit depends on how their individual pay rises compare with changes in consumer prices.
Average earnings figures do not show how every worker’s pay has changed. Some employees may receive larger increases, while others may experience little growth or see their working hours reduced. The figures also exclude bonuses, meaning they do not capture every component of compensation.
For employers, the data presents a mixed picture. Higher wage costs may place pressure on businesses already facing increased energy and operating expenses, while declining vacancies suggest some firms are becoming more cautious about hiring.
Companies may respond to these pressures in different ways. Some may raise prices, while others may absorb additional costs, improve efficiency or delay recruitment. The choices businesses make will influence how wage and energy pressures spread through the economy.
For households and borrowers, the prospect of a rate increase is also important. Higher interest rates can affect mortgage costs for people with variable-rate arrangements or those refinancing, as well as the cost of some other forms of credit. Savers may benefit from improved returns on certain deposits, depending on how financial institutions respond to policy changes.
The actual impact will vary from household to household. The latest employment figures provide information about broad economic trends, but they cannot predict precisely how an individual worker, business or borrower will be affected.
Conclusion
The UK’s labour market is showing tentative signs of recovery, with average weekly earnings excluding bonuses rising by 3.7% in the three months to August, payroll employment increasing by 13,000 in September and unemployment falling to 4.7%.
However, the decline in job vacancies to 691,000 shows that hiring conditions remain weak in important respects. The combination of improving wage and employment figures with falling vacancies leaves the Bank of England facing a mixed economic picture as it considers whether to raise interest rates next month.
The central bank’s key concern is whether the energy price shock linked to the Iran war is feeding into persistent domestic inflation, particularly through wage demands and business pricing decisions. The latest data adds to that debate but does not settle it.
Future decisions will depend on whether wage growth remains firm, how employment and vacancies develop, and whether inflation pressures spread more broadly across the economy. Until those signals become clearer, the possibility of a rate increase remains open, while the labour-market recovery appears gradual rather than firmly established.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest World on thefoxdaily.com.

COMMENTS 0