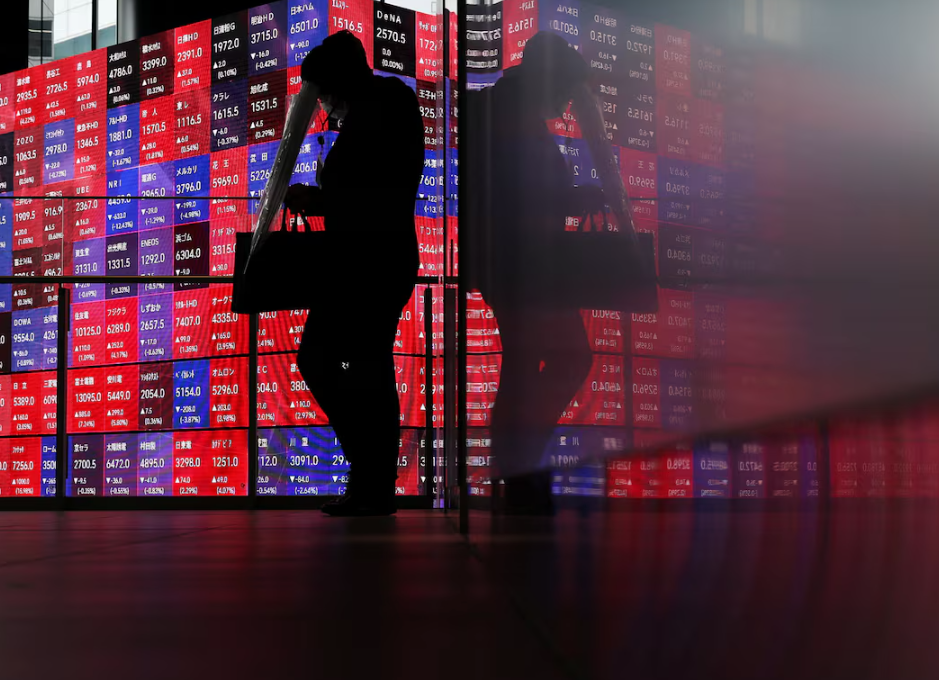
Global stocks started the week on a stronger footing on Monday as investors reduced expectations for another Federal Reserve interest-rate increase in October following weaker-than-expected US employment data. The dollar slipped from recent highs while government bonds steadied, although yields remained elevated by historical standards.
Markets were responding to data showing that US job growth slowed more than expected in September, while employment figures for the previous two months were revised significantly lower. The softer labor-market picture reduced expectations that the Federal Reserve would continue tightening monetary policy immediately.
Markets Reduce Expectations for October Fed Hike
Investors have sharply lowered their expectations for an October rate increase after the latest US employment figures. Markets were pricing in a 22% probability of a Federal Reserve rate hike this month, down from 64% a week earlier, according to the CME FedWatch tool.
The change in expectations provided support for risk assets because a pause in rate increases could reduce pressure on borrowing costs and financial conditions.
Jose Torres, senior economist at Interactive Brokers, said the downward revisions to employment data indicated that the US labor market had lost momentum. He argued that the weaker employment picture reduced the likelihood of another major tightening move by the Federal Reserve.
Asian Stocks Start the Week Higher
Japanese stocks led gains in early Asian trading. The Nikkei rose about 2% at one point, while Australia’s benchmark stock index gained 0.5%.
MSCI’s broadest index of Asia-Pacific shares outside Japan also edged higher. US equity futures pointed to a positive opening, with Nasdaq futures up 0.3% and S&P 500 futures gaining 0.1%.
European markets were also positioned for a stronger start. EUROSTOXX 50 futures rose 0.3%, while FTSE futures gained 0.4%.
Trading volumes in Asia were relatively thin because markets in China, South Korea and Australia’s New South Wales were closed for holidays. This left regional investors taking much of their direction from Wall Street’s performance on Friday and the latest US economic data.
US Jobs Data Changes the Fed Outlook
The latest employment figures have become one of the most important inputs into expectations for US monetary policy. A weaker labor market can reduce pressure on the Federal Reserve to raise interest rates, particularly if inflation is also showing signs of moderation.
The September data showed slower-than-expected job growth, while revisions to the previous two months reduced the number of jobs previously reported. The revisions added to concerns that labor-market conditions could be losing strength.
For investors, the key question is whether the weaker employment trend continues. If job growth remains subdued, the Federal Reserve could have more reason to pause and assess the impact of its previous policy decisions.
However, the latest figures do not automatically rule out future rate increases. Inflation, wages, economic growth and additional employment reports will continue to influence the central bank’s decisions.
Bond Yields Remain Near Multi-Year Highs
Government bond markets stabilized on Monday after a recent selloff. The benchmark 10-year US Treasury yield slipped slightly to 5.2643%, while the two-year yield stood at 4.8143%.
Yields initially moved lower following the weaker employment data, but the decline was limited. Investors continue to deal with several factors putting upward pressure on bond yields, including government borrowing needs, large volumes of new debt issuance and elevated energy costs.
Higher bond yields remain an important issue for global financial markets because they can increase borrowing costs and influence valuations across stocks, bonds and other assets.
Why Bond Markets Remain Under Pressure
Government finances have become an important consideration for bond investors. Large fiscal deficits can require governments to issue substantial amounts of debt, increasing the supply of bonds that investors need to absorb.
At the same time, elevated energy prices can add to inflation concerns. If investors believe inflation will remain high, they may demand higher yields to compensate for the risk of holding longer-term government debt.
Despite the recent rise in yields, some strategists believe the bond selloff may not continue indefinitely.
Cedric Lam, senior investment strategist at Standard Chartered, said recent US data had begun showing softer-than-expected inflation. He also pointed to temporary market pressures, including forced selling by hedge funds and real estate investment trusts, as factors affecting bond yields.
Lam said his firm had taken an opportunistic bullish view on US 10-year government bonds, suggesting expectations that yields could eventually move lower.
Dollar Loses Momentum as Fed Bets Shift
The US dollar weakened as traders reduced expectations for an October Federal Reserve rate increase. Lower expectations for US interest rates can reduce the yield advantage of dollar-denominated assets, potentially weighing on the currency.
The euro recovered from a 17-month low to trade around $1.1243, while sterling edged higher to approximately $1.3241.
The dollar also slipped slightly against the Japanese yen, trading around 157.81 yen.
The currency outlook remains mixed. Expectations for a Federal Reserve pause could put pressure on the dollar, but stronger US economic performance and continued international demand for US securities could provide support.
US Growth Could Still Support the Dollar
Despite the latest weakness, the dollar continues to benefit from the relative strength of the US economy and the depth of US financial markets.
Elias Haddad, global head of markets strategy at BBH, said tighter monetary policy in other economies and growing expectations of an October Fed pause could weigh on the dollar. However, stronger US growth and foreign demand for US securities could continue to support the currency.
This creates a complicated outlook for the dollar. Interest-rate expectations are moving against the currency in the short term, but economic growth and capital flows could limit its decline.
Oil Prices Stay Above $100 as Middle East Risks Persist
Oil prices remained elevated as investors monitored fresh geopolitical developments in the Middle East.
Brent crude futures were little changed at around $102.20 per barrel, while US crude traded near $90.75 per barrel.
The latest price moves came after Yemen’s Iran-backed Houthis said they had launched ballistic missiles and drones at Saudi Aramco facilities in Riyadh and the Khurais area.
Energy markets remain highly sensitive to developments in the Middle East because the region is responsible for a significant share of global oil production and exports. Any disruption to production or transportation infrastructure could further tighten supply conditions.
Higher oil prices also complicate the Federal Reserve’s policy outlook because sustained energy inflation can feed into broader price pressures.
Gold Moves Higher
Gold prices also moved higher on Monday. Spot gold gained 0.3% to around $4,154.32 an ounce.
Gold can attract demand when investors are seeking protection against economic or geopolitical uncertainty. Its performance can also be influenced by interest-rate expectations and movements in the US dollar.
The combination of geopolitical risks, changing expectations for Federal Reserve policy and elevated government bond yields therefore remains important for precious-metals markets.
Brazil Election Adds Another Market Focus
Brazilian financial markets are also expected to attract attention after Senator Flavio Bolsonaro advanced to a presidential runoff against President Luiz Inacio Lula da Silva.
The first-round result was stronger than expected for Bolsonaro, according to the market report, setting up a closely watched runoff.
Brazilian markets could respond to expectations about economic policy, fiscal management and the potential direction of the country’s next government. Investors will also assess how the election affects the Brazilian real, government bonds and equities.
Global Markets Enter a Crucial Week
The shift in Federal Reserve expectations has provided a near-term boost to stocks, but investors still face several competing forces.
Weaker US employment data has reduced the probability of an October rate increase, supporting equities and weighing on the dollar. However, Treasury yields remain near multi-year highs, while elevated oil prices could add to inflationary pressure.
That combination means markets may remain sensitive to every major economic indicator and central-bank signal in the coming weeks.
What Investors Are Watching Now
- US employment and inflation data for clues about future Federal Reserve policy.
- The probability of an October Fed rate hike after expectations fell sharply.
- The direction of 10-year US Treasury yields, which remain above 5%.
- US dollar movements against the euro, yen and pound.
- Oil prices and developments affecting Middle Eastern supply.
- Gold prices as investors assess geopolitical and economic risks.
- Brazil’s presidential runoff and its potential market implications.
Markets Balance Fed Relief Against Inflation Risks
Monday’s trading showed how quickly financial markets can respond when expectations for monetary policy change. The weaker US employment report reduced expectations for an immediate rate increase, helping stocks rise and taking some pressure off bonds.
But the market environment remains complicated. Treasury yields are still high, energy prices remain elevated and geopolitical risks continue to affect commodities.
For equities, the immediate benefit from lower Fed hike expectations could be offset if higher oil prices contribute to renewed inflation concerns. For the dollar, reduced US rate expectations may create downward pressure, although strong economic growth and demand for US assets remain supportive factors.
What Comes Next for Stocks and the Dollar?
The direction of global markets will depend heavily on whether the latest employment weakness develops into a broader slowdown or proves temporary.
A sustained cooling in the US labor market could strengthen expectations that the Federal Reserve will pause its rate increases, potentially supporting stocks and bonds while reducing the dollar’s interest-rate advantage.
On the other hand, if economic activity remains resilient while energy prices push inflation higher, the Federal Reserve could face a more difficult policy choice.
For now, investors have moved away from expectations of an immediate October rate hike, giving global stocks a stronger start to the week. But with bond yields elevated and geopolitical risks still affecting energy markets, financial conditions remain highly sensitive to incoming economic and policy signals.
Frequently Asked Questions
Why are stocks rising on October 5, 2026?
Stocks rose as investors reduced expectations for an October Federal Reserve rate hike following weaker-than-expected US employment data and downward revisions to earlier job figures.
What are markets pricing for an October Fed rate hike?
Markets were pricing in a 22% probability of an October rate increase, down from 64% a week earlier, according to the CME FedWatch tool cited in the report.
How did the US jobs data affect the dollar?
The weaker employment data reduced expectations for another near-term Federal Reserve rate increase, putting some pressure on the dollar. The euro and sterling both strengthened slightly against the US currency.
What is happening to US Treasury yields?
The 10-year US Treasury yield edged lower to about 5.2643%, while the two-year yield stood at around 4.8143%. Despite the small decline, yields remain near multi-year highs.
Why are oil prices still elevated?
Oil prices remain supported by geopolitical risks in the Middle East and concerns about potential disruptions to crude production and exports.
What was the Brent crude price?
Brent crude futures were trading around $102.20 per barrel in the latest market update, while US crude was around $90.75 per barrel.
Why is gold rising?
Spot gold gained 0.3% to around $4,154.32 an ounce as investors continued to assess monetary-policy expectations and geopolitical risks.
What will determine the next move in global markets?
Investors will closely monitor US economic data, Federal Reserve policy expectations, Treasury yields, inflation, oil prices, geopolitical developments and currency movements.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0