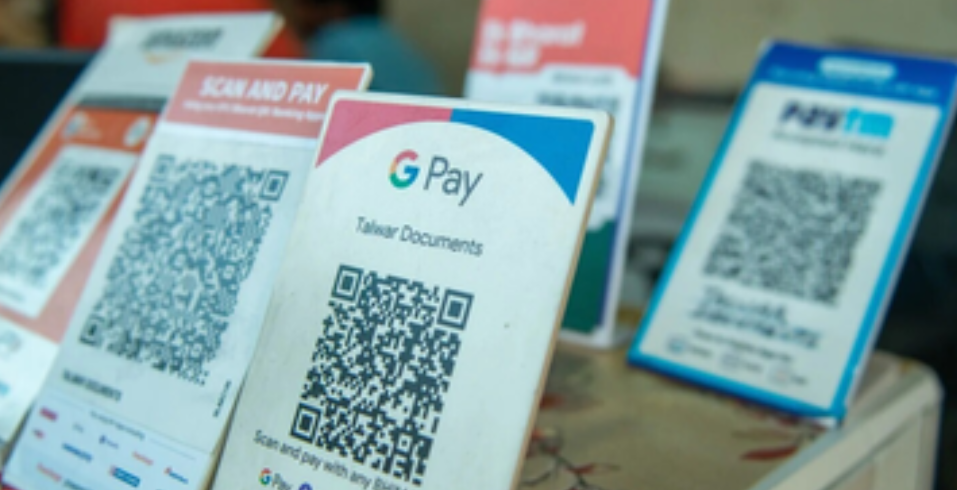
The Supreme Court has sought the Centre’s response on the proposed Merchant Discount Rate (MDR) for certain UPI person-to-merchant transactions above ₹2,000, while declining to stay the notification before it takes effect.
Supreme Court Seeks Centre’s Response on UPI Charges
The Supreme Court has questioned the legal basis for the Centre’s proposed Merchant Discount Rate on selected Unified Payments Interface (UPI) transactions above ₹2,000. The court has asked the government to explain the legal source and framework under which the charge is being introduced.
A bench headed by Chief Justice of India Surya Kant, along with Justices Joymalya Bagchi and V Mohana, heard a public interest litigation challenging the proposed UPI MDR framework. The court described the matter as involving both technical and legal questions and asked the Centre to provide the relevant facts through a short affidavit.
The court also sought responses from the National Payments Corporation of India (NPCI) and the Reserve Bank of India (RBI). The Supreme Court’s focus at this stage is on the legal basis for the charge rather than deciding the wider merits of the government’s economic policy.
The development comes shortly before the proposed framework is scheduled to take effect on October 15.
What Is the Proposed UPI MDR?
Under the proposed framework, a 0.4% Merchant Discount Rate would apply to specified UPI person-to-merchant transactions above ₹2,000.
The charge would be subject to a maximum of ₹300 for transactions above ₹75,000. The framework also contains different treatment for certain sectors and financial-market transactions.
Importantly, the proposed change does not apply to person-to-person UPI transfers. Such transfers are intended to remain free regardless of the amount involved.
This distinction means that a UPI payment made from one individual to another would remain outside the proposed MDR framework, while certain payments made to merchants could attract the charge when they cross the specified threshold.
Supreme Court Questions the Source of the Charge
The central issue raised during the hearing concerns how the Centre derives its authority to introduce the new charge.
The Supreme Court questioned whether the MDR should legally be treated as a fee and, if so, whether it can be imposed through an executive notification. The judges also asked how the charge should be characterized if it is not a government fee.
The court indicated that it wants the Centre to clarify the legal mechanism before examining the issue further. It also raised questions about who would ultimately receive the amount collected and whether it could be regarded as income under applicable tax provisions.
This makes the case significant beyond the immediate question of UPI charges because it involves the relationship between legislation, executive notifications and the payment system’s existing legal framework.
Supreme Court Does Not Stay the Notification
The petitioner sought a stay on the notification introducing the proposed MDR. However, the Supreme Court did not grant a stay at this stage.
The court noted that the matter involves economic policy and that the proposed charge had not yet taken effect. Instead, it chose to seek responses from the Centre, RBI and NPCI before examining the legal questions in greater detail.
The decision means the proposed October 15 implementation remains the relevant date while the legal challenge continues, subject to any further orders from the court.
What the Centre Told the Supreme Court
Additional Solicitor General N Venkataraman appeared for the Centre and told the court that the proposed decision would affect only a limited portion of UPI users.
According to the Centre’s submission reported during the hearing, 96% of people using the UPI payment gateway would be exempt from the proposed change. The government also said that essential services covered by the framework would have specific caps.
The Centre further argued that the money collected would not go to the government. Instead, it described the MDR as a settlement fee involving the relevant bank and service provider, with NPCI facilitating the payment system.
The distinction is important because the Supreme Court is examining, among other issues, the legal nature of the charge and the question of in whose hands it could constitute income.
Special Rules for Essential Services
The proposed framework does not apply the same MDR structure to every category of transaction.
For payments above ₹2,000 in sectors including railways, telecom, insurance, fuel and agricultural inputs, the notification provides for a flat MDR of ₹5 per transaction.
This means that qualifying transactions in these sectors would not necessarily face the standard 0.4% rate that applies to the broader category of specified merchant payments.
The separate treatment reflects the government’s decision to establish different rules for particular types of transactions while maintaining the overall threshold-based framework.
Different MDR for Capital-Market Transactions
The proposed rules also provide a separate MDR structure for certain capital-market transactions.
Transactions involving mutual funds, securities, stockbrokers and dealers would attract an MDR of 0.02%, subject to a cap of ₹300 per transaction, according to the notification described during the court proceedings.
This is substantially different from the proposed 0.4% rate for the broader category of specified merchant UPI transactions above ₹2,000.
The differentiated structure means the effect of the proposed policy will depend on the type of transaction and the sector in which the payment occurs.
Why Person-to-Person UPI Payments Are Different
The proposed MDR framework distinguishes between person-to-person and person-to-merchant payments.
Person-to-person transfers are payments made directly between individuals. Under the government’s proposed framework, these transfers will continue to remain free, even when the transaction value is above ₹2,000.
Person-to-merchant payments, on the other hand, involve a customer paying a business or service provider. Certain transactions in this category above ₹2,000 would fall within the proposed MDR framework.
The distinction is important for understanding the proposed policy because the ₹2,000 threshold does not mean that every UPI payment above ₹2,000 will automatically attract the charge.
Background to the Legal Challenge
The petition was filed by advocate Anjan Datta and challenged the Finance Ministry’s September 14 notification. The petition also questioned the constitutional validity of the legislative amendment that preceded the notification.
According to the petition, the legal framework governing UPI charges had previously provided protection against direct or indirect charges on specified digital payment modes.
The petitioner referred to a 2019 government notification that removed MDR on person-to-merchant UPI transactions from January 1, 2020. The petition also relied on provisions of the Payment and Settlement Systems Act, 2007 and the Income-tax Act.
The legal challenge argues that subsequent changes to the statutory framework altered the government’s authority to determine which electronic payment modes would continue to receive no-charge protection.
What Changed in the 2026 Law?
The petition states that Parliament passed the Taxation and Other Laws (Amendment) Act, 2026 in August, after which it received Presidential assent.
According to the petition’s account, the legislation amended Section 10A of the Payment and Settlement Systems Act, 2007. The amendment gave the Centre the power to specify, through notification, which prescribed electronic modes would receive protection from charges.
The September 14 notification was subsequently issued under that amended framework.
It specified two categories of electronic payments as exempt from the no-charge protection: RuPay debit-card transactions without a monetary ceiling and UPI transactions up to ₹2,000.
This change forms an important part of the legal dispute because the petition challenges whether the amended law and subsequent notification provide a valid basis for introducing the new MDR framework.
Why the Legal Basis Matters
The Supreme Court’s questions indicate that the case is not limited to whether UPI charges are economically desirable. The court is examining the legal route through which the charge has been introduced.
When a government imposes a payment-related charge, questions can arise over whether the charge requires specific statutory authority, how the money should be classified and which institution has the authority to collect or facilitate it.
The Supreme Court has therefore asked the Centre to provide facts and explain the legal source of the proposed charge. Responses from RBI and NPCI are also expected to help the court understand the structure of the payment system and the proposed MDR.
What UPI Users Need to Know
For consumers, one of the most important points is that the proposed framework does not introduce a blanket fee on all UPI transactions above ₹2,000.
Person-to-person transfers remain outside the proposed charge. The MDR applies to specified person-to-merchant transactions and contains separate provisions for certain sectors and capital-market transactions.
The exact effect on a payment will therefore depend on whether it is a merchant transaction, its value and the category of merchant or service involved.
As the Supreme Court reviews the legal challenge, the proposed framework could also be subject to further judicial consideration or subsequent government action.
What Happens Next in the Supreme Court Case?
The Centre, RBI and NPCI are expected to provide their responses to the court’s questions. The Supreme Court will then be in a better position to examine the legal foundation of the proposed MDR framework.
The court has not, at this stage, ruled on the constitutional validity of the notification or the amended statutory provisions. It has also not stopped the proposed framework from taking effect.
The next stages of the proceedings could therefore provide greater clarity on whether the Centre has the necessary legal authority to impose or facilitate the proposed charges and how the MDR should be legally characterized.
Why the UPI MDR Case Matters
UPI has become a central part of India’s Digital Payments system, making any change to its cost structure significant for banks, payment providers, merchants and consumers.
The proposed MDR framework introduces a new distinction between different types and values of UPI transactions. At the same time, the Supreme Court’s intervention places the legal foundation of the policy under judicial examination.
The case could ultimately provide clarity on how Parliament’s amended payment-system framework interacts with executive notifications and the existing rules governing digital payment charges.
For now, the key developments are the Centre’s forthcoming affidavit, responses from RBI and NPCI, and any subsequent orders from the Supreme Court.
Frequently Asked Questions
What is UPI MDR?
UPI MDR, or Merchant Discount Rate, is a transaction-related charge proposed for specified UPI person-to-merchant payments. Under the proposed framework, a 0.4% rate would apply to certain merchant transactions above ₹2,000.
Will all UPI payments above ₹2,000 be charged?
No. The proposed framework distinguishes between different types of UPI payments. Person-to-person transfers are intended to remain free, while specified person-to-merchant transactions above ₹2,000 could attract MDR.
When is the proposed UPI MDR scheduled to start?
The notification challenged before the Supreme Court is scheduled to take effect from October 15, 2026, subject to any further government action or court orders.
What is the proposed MDR rate for qualifying merchant payments?
The proposed standard MDR is 0.4% for specified UPI person-to-merchant transactions above ₹2,000, with a maximum of ₹300 for transactions above ₹75,000.
Will person-to-person UPI transfers remain free?
Yes. The Centre has clarified that person-to-person UPI transfers will continue to remain free regardless of the transaction amount.
What MDR is proposed for essential services?
For qualifying payments above ₹2,000 in sectors such as railways, telecom, insurance, fuel and agricultural inputs, the proposed MDR is ₹5 per transaction.
What did the Supreme Court ask the Centre?
The Supreme Court asked the Centre to explain the legal source and basis for implementing the proposed charge and sought a short affidavit containing the relevant facts.
Did the Supreme Court stay the proposed UPI MDR?
No. The court declined to grant a stay at this stage. It sought responses from the Centre, RBI and NPCI while examining the legal basis of the proposed framework.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0