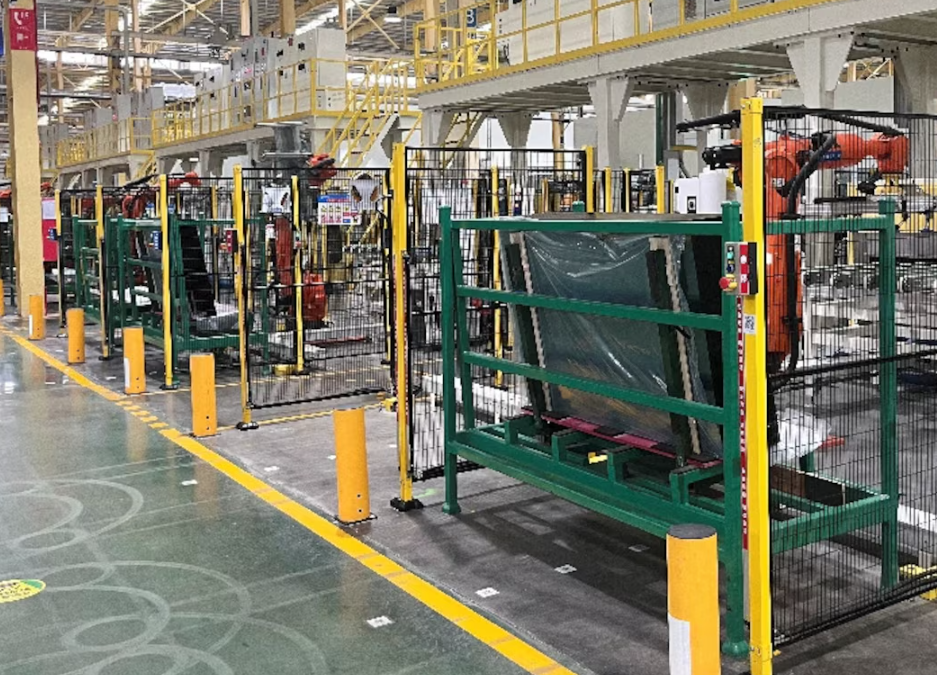
China’s economy is showing fresh signs of weakness as fixed-asset investment, property activity, credit growth and employment indicators point to continued pressure on domestic demand. Fixed-asset investment declined 7.2% in the first eight months of the year, marking its steepest fall since April 2020.
The slowdown is particularly visible in the property sector. Property investment fell 19.9% from a year earlier during the first eight months, highlighting the continued weakness in China’s real estate market. At the same time, investment in high-tech industries increased 5.2%, supported by strong global interest in artificial intelligence and technology-related sectors.
The latest data suggest that while some parts of China’s economy are benefiting from technology investment and improving factory activity, domestic demand remains a major challenge for policymakers.
China’s Fixed-Asset Investment Falls 7.2%
Fixed-asset investment, which includes spending on infrastructure, property and other long-term assets, declined 7.2% in the first eight months.
The fall represents the steepest decline since April 2020, when China’s economy was dealing with the severe disruption caused by the COVID-19 pandemic.
A sustained decline in investment matters because fixed-asset spending is an important source of economic activity. Infrastructure construction, property development and industrial investment support demand for materials, equipment, labour and related services.
The latest weakness therefore suggests that China’s domestic investment engine remains under significant pressure.
Property Investment Drops Nearly 20%
The property sector remains one of the biggest weaknesses in China’s economy. Property investment plunged 19.9% during the first eight months compared with the same period a year earlier.
The prolonged property downturn has broader consequences because real estate affects construction companies, building-material suppliers, financial institutions, local government revenues and household confidence.
Weak property investment can also reduce demand for related products and services. When developers slow construction and buyers remain cautious, the impact can spread beyond the housing market itself.
The latest decline indicates that China’s property sector has yet to become a strong contributor to economic growth.
High-Tech Investment Provides a Bright Spot
Not every part of China’s investment landscape is contracting. Investment in high-tech industries increased 5.2% during the period.
The increase comes as companies and governments around the world accelerate spending related to artificial intelligence and other advanced technologies.
High-tech investment provides China with an important source of potential growth because it can support industrial upgrading, automation, advanced manufacturing and technology development.
However, stronger high-tech investment has not yet been sufficient to offset the much larger weakness in property and overall fixed-asset investment.
| Economic Indicator | Latest Trend | What It Signals |
|---|---|---|
| Fixed-asset investment | Down 7.2% in first eight months | Broad investment weakness |
| Property investment | Down 19.9% | Continued real estate-sector pressure |
| High-tech investment | Up 5.2% | Technology remains a growth area |
| Urban surveyed unemployment | 5.3% in August | Slight deterioration in labour-market conditions |
| Factory activity | Improved but remained in contraction | Manufacturing recovery remains incomplete |
| Services activity | Sluggish | Weakness in domestic demand continues |
Factory Activity Improves but Remains in Contraction
China’s factory activity improved in August, but the improvement was not enough to move the sector out of contraction.
This distinction is important. A month-to-month improvement can indicate that economic conditions are stabilising, but remaining in contraction suggests that industrial demand is still not strong enough to support a broad manufacturing expansion.
For policymakers, the objective will be to turn temporary improvements into a sustained recovery in production, orders and domestic demand.
Services Sector Also Remains Sluggish
China’s services activity remained sluggish, adding to concerns about the strength of domestic consumption.
Services are an important part of modern economies because they include a wide range of activities linked to household spending, business demand and employment. Weak services activity can therefore be another indication that consumers and companies remain cautious.
The combination of weak property investment, subdued services activity and soft credit demand suggests that China’s domestic economy is still struggling to generate strong momentum without additional policy support.
Weak Domestic Demand Hurts Credit Growth
Credit growth has also reflected the weakness in domestic demand. New bank loans returned to positive territory after a record contraction in July, but the recovery was much weaker than analysts had expected.
This matters because stronger borrowing can support investment and consumption. When companies and consumers are reluctant to borrow, lower credit demand can become another constraint on economic growth.
The latest figures therefore point to a broader problem: even when financial institutions have the capacity to provide credit, businesses and households may not be sufficiently confident about future economic conditions to increase borrowing aggressively.
China’s Unemployment Rate Edges Higher
The nationwide urban surveyed unemployment rate reached 5.3% in August, compared with 5.2% in the previous month.
The increase was relatively small, but it adds to the broader picture of an economy facing uneven growth.
Employment is particularly important for domestic demand because household confidence and spending are closely connected to income stability and expectations about future job opportunities.
If labour-market conditions remain under pressure, consumers may remain cautious, limiting the strength of the consumption recovery that policymakers want to encourage.
Extreme Weather Adds Another Economic Challenge
Extreme weather also appears to have weighed on economic activity during August. Four typhoons made landfall in China during the month, disrupting operations in the country’s eastern coastal manufacturing and logistics belt.
The eastern coast is particularly important to China’s industrial and trade networks. Disruptions to factories, transportation and logistics can temporarily affect production schedules and supply chains.
Weather-related disruptions are generally temporary, but they can amplify existing economic weakness when companies are already dealing with subdued demand.
Beijing Steps Up Policy Support
Chinese authorities have responded to the slowdown with additional policy measures rather than immediately announcing broad reductions in key policy rates or banks’ reserve-requirement ratios.
The government has accelerated the issuance of government bonds and expanded loan-interest subsidies for small private companies and consumers.
These measures are intended to provide targeted support to areas of the economy where financing conditions and demand remain weak.
The central bank has also pledged additional policy support, although it has not signalled explicit cuts to policy rates or banks’ reserve-requirement ratios.
Why Fiscal Policy Is Becoming More Important
The latest economic data increase pressure on Beijing to make fiscal policy more supportive.
Zhiwei Zhang, president and chief economist of Pinpoint Asset Management, said the market is waiting for fiscal policy to become more supportive in the third quarter after the economy slowed in the second quarter.
This highlights an important policy question: whether authorities will rely primarily on targeted measures or introduce stronger fiscal support to boost demand.
Faster government bond issuance can help finance public investment and other government programmes. Interest subsidies can also reduce borrowing costs for selected businesses and consumers.
However, the effectiveness of these measures will depend on whether they translate into stronger spending, investment and confidence across the wider economy.
China’s Economic Picture: Weak Property, Stronger Technology
The latest data show an increasingly uneven Chinese economy.
On one side, property investment is contracting sharply and overall fixed-asset investment is falling. Manufacturing and services remain weak, while credit demand is below expectations.
On the other side, high-tech investment continues to expand, reflecting China’s focus on advanced industries and the global AI investment cycle.
This creates a two-speed economic picture in which technology-related industries can expand even as traditional growth engines remain under pressure.
| Area | Current Direction | Economic Significance |
|---|---|---|
| Real estate | Sharp contraction | Remains a major drag on investment |
| Infrastructure and fixed assets | Declining | Shows broad investment weakness |
| High-tech industries | Growing | Supports industrial upgrading and AI-related investment |
| Manufacturing | Improved but still contracting | Recovery remains incomplete |
| Services | Sluggish | Reflects weak domestic demand |
| Credit | Recovered from July contraction but below expectations | Indicates cautious borrowing demand |
| Employment | Unemployment edged higher | Could weigh on consumer confidence |
What the Data Mean for China’s Growth Outlook
The latest figures suggest that China’s growth outlook remains dependent on how effectively policymakers can revive domestic demand.
A recovery led mainly by exports and high-tech investment may not fully compensate for weakness in property, consumption and traditional investment. A broader recovery would require stronger demand from households and businesses.
The property downturn is especially important because restoring confidence in the housing market could influence construction activity, household wealth perceptions and related spending.
At the same time, the expansion of high-tech industries could help reshape the economy over the longer term by directing investment toward newer sectors rather than relying as heavily on property and traditional infrastructure.
Can Government Support Reverse the Slowdown?
Beijing has several policy tools available, including fiscal spending, government bond issuance, targeted lending support and monetary policy measures.
The current approach appears focused on targeted support rather than immediately announcing broad interest-rate or reserve-requirement cuts.
The effectiveness of this strategy will depend on whether businesses and consumers respond by increasing borrowing and spending.
If weak confidence remains the main problem, simply making credit cheaper may not be enough. Stronger fiscal measures that directly support demand could become increasingly important.
Key Risks Facing China’s Economy
Property Market Weakness
The 19.9% decline in property investment remains one of the clearest signs of economic weakness. A prolonged real estate downturn could continue to weigh on investment and confidence.
Weak Domestic Demand
Sluggish services activity and weaker-than-expected credit growth indicate that consumers and businesses remain cautious.
Employment Pressure
The rise in the urban surveyed unemployment rate to 5.3% adds another challenge for policymakers seeking stronger household spending.
Extreme Weather
Typhoons and other weather disruptions can interfere with manufacturing and logistics, adding short-term volatility to economic activity.
Uneven Recovery
Strong growth in high-tech investment is encouraging, but it may take time for newer industries to offset weakness in property and traditional investment.
What to Watch Next
Investors and economists will closely monitor whether Beijing increases fiscal support in the third quarter and whether the measures begin to improve domestic demand.
- Future government bond issuance and fiscal spending.
- Additional central-bank support measures.
- Property investment and housing-market conditions.
- Consumer and business credit growth.
- Manufacturing and services activity.
- Employment trends.
- Continued investment in high-tech and AI-related industries.
Conclusion
China’s latest economic indicators point to a recovery that remains uneven and fragile. Fixed-asset investment fell 7.2% in the first eight months, while property investment plunged 19.9%, highlighting the continuing drag from the real estate sector.
At the same time, high-tech investment grew 5.2%, providing an important area of strength as China participates in the global AI and technology investment boom.
The bigger challenge remains domestic demand. Factory activity has improved but remains in contraction, services are sluggish, credit growth is weaker than expected and urban unemployment has edged higher.
Beijing has already accelerated government bond issuance and expanded targeted interest subsidies while signalling additional central-bank support. The next test will be whether these measures can translate into stronger consumer and business confidence.
For China’s economy, the key question is no longer simply whether some sectors can grow. It is whether policymakers can turn pockets of strength, particularly in high technology, into a broader recovery while stabilising property, investment, employment and domestic demand.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0