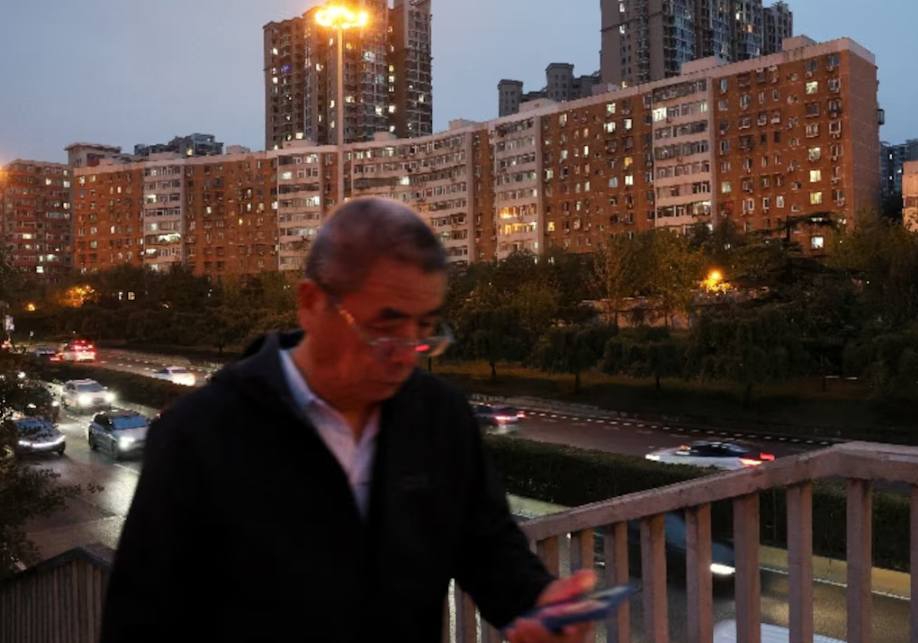
China home prices remained under pressure in August 2026, highlighting the continuing weakness in the country’s property market and raising concerns about the strength of domestic demand. New home prices fell 0.1% from July, marking another monthly decline and extending the difficult period for China’s housing sector.
On an annual basis, new home prices declined 3.0% in August, although the pace of decline narrowed from 3.2% in July. The improvement in the year-on-year figure suggests that the prolonged downward trend may be losing some intensity, but it does not yet indicate a broad-based recovery.
The biggest cities showed early signs of stabilisation, while tier-two and tier-three cities continued to record price declines. At the same time, falling property sales, investment and new construction starts, along with shrinking household borrowing, indicate that China’s real estate downturn remains a major drag on the wider economy.
China New Home Prices Fall Again in August
New home prices declined 0.1% in August from July, according to calculations based on data from China’s National Bureau of Statistics. The same monthly decline was recorded in both June and July.
The annual picture was somewhat more encouraging. New home prices were down 3.0% from a year earlier, compared with a 3.2% annual decline in July. It was the slowest annual rate of decline recorded this year.
This suggests that the pace of deterioration is moderating, even though prices have not yet returned to sustained growth.
| Housing Indicator | August 2026 Trend | What It Indicates |
|---|---|---|
| New home prices, monthly | Down 0.1% | Prices remain under pressure |
| New home prices, annual | Down 3.0% | Annual decline is moderating |
| Tier-one new homes | Up 0.1% month-on-month | Signs of stabilisation in major cities |
| Tier-two cities | Declined | Recovery remains uneven |
| Tier-three cities | Declined | Smaller markets remain weaker |
| Household loans in August | Down 202.9 billion yuan | Households remain cautious about borrowing |
Tier-One Cities Show Signs of Stabilisation
The housing market is not behaving uniformly across China. The country’s largest cities have begun showing signs of relative resilience compared with smaller markets.
New home prices in tier-one cities rose 0.1% in August from July, reversing the previous monthly decline. Resale home prices in tier-one cities also improved during August.
By contrast, tier-two and tier-three cities continued to record declines. This divergence is important because China’s property market is highly regional, and stronger conditions in major cities do not necessarily translate into a nationwide recovery.
Major urban centres can benefit from stronger employment opportunities, deeper economic activity and comparatively stronger housing demand. Smaller markets can face greater challenges when population growth, employment prospects and buyer confidence are weaker.
Why China’s Property Market Matters to the Economy
The property sector is much more than a housing market in China. It has significant links with construction, household wealth, local government finances, financial institutions and consumer behaviour.
When property prices and transactions remain weak, households may become more cautious about spending. Developers may reduce construction and investment, while local governments can face pressure on revenue.
This creates a feedback loop in which weak property demand contributes to weaker economic activity, while slower economic growth can further reduce confidence among potential homebuyers.
That is why policymakers are under pressure to stabilise the housing market while also encouraging household consumption.
Property Sales, Investment and Construction Remain Weak
The latest housing-price data are not an isolated indicator of weakness. Separate economic figures show that property sales, investment and new construction starts all fell during the first eight months of the year.
This broader weakness suggests that the problem is not simply that homes are becoming cheaper. The underlying level of activity in the property sector also remains subdued.
For developers, weaker sales can limit the cash available for new projects. Lower construction starts can then reduce demand for building materials, construction services and related industries.
The result is a wider economic impact that extends beyond developers and homebuyers.
Household Borrowing Shows Weak Homebuyer Confidence
Another important signal comes from household lending. Household loans, including mortgages, declined by 202.9 billion yuan in August, following a much larger 460.3 billion yuan contraction in July.
The continued contraction suggests that households remain reluctant to increase borrowing.
For the property market, mortgage demand is particularly important. Even when property prices become more affordable, potential buyers may delay purchases if they are uncertain about employment, income, future house prices or the wider economy.
This means that lowering financing costs alone may not be sufficient to generate a strong housing recovery if confidence remains weak.
Government Tries to Reform Property Financing
Chinese authorities introduced several measures in August aimed at improving the long-term structure of property development financing.
One major focus has been moving developers away from a presale model that created problems for homebuyers when construction on purchased homes stalled during the property downturn.
The government has also extended the maximum term for mortgage loans to 40 years from 30 years.
These measures are intended to improve homebuyer confidence and establish a less risky funding model for property development.
However, analysts have cautioned that structural reforms may not generate a major increase in housing demand immediately.
Why Presale Reform Matters
China’s presale system became an important source of funding for developers, but the property downturn exposed risks when developers faced financial difficulties and construction on presold homes was delayed.
Homebuyers who had already committed to properties were therefore exposed to concerns about project completion.
Moving towards a less risky financing model could improve confidence over time, but rebuilding trust requires more than changing financing rules. Buyers also need confidence that projects will be completed and that property values and household finances will remain reasonably stable.
China’s Housing Recovery Is Becoming a Confidence Problem
The latest data underline the importance of homebuyer confidence to China’s property recovery.
Zhang Dawei, chief analyst at Centaline Property, said the narrowing year-on-year decline indicates that the previous sustained downward trend has been contained. However, he also said a broad nationwide recovery was unlikely in the near term, partly because of the seasonal slowdown typically seen at this time of year.
He identified the recovery of homebuyer confidence, the release of reasonable housing demand and the effectiveness of local stabilisation policies as important factors for future market repair.
This means the next stage of China’s housing recovery may depend less on simply stopping price declines and more on convincing households to return to the market.
China’s Property Market Has a Two-Speed Recovery
The August data reveal an increasingly important divide between China’s largest cities and smaller housing markets.
Tier-one cities recorded a 0.1% monthly increase in new home prices and also showed improvement in resale prices. Meanwhile, tier-two and tier-three cities continued to decline.
This creates a two-speed housing market. Stabilisation in major metropolitan areas could be an early indication that the worst phase of the downturn is passing in selected locations, but weaker smaller cities show that the national property market remains far from a uniform recovery.
| Market Segment | August Trend | Recovery Assessment |
|---|---|---|
| Tier-one cities | New home prices rose 0.1% | Early signs of stabilisation |
| Tier-two cities | Prices declined | Demand remains under pressure |
| Tier-three cities | Prices declined | Recovery remains difficult |
| Nationwide market | New home prices down 0.1% monthly | No broad-based recovery yet |
Property Weakness Is Holding Back Domestic Consumption
One of the biggest economic concerns is the connection between housing weakness and household spending.
When households are uncertain about property values or their future financial position, they may become more conservative with discretionary spending. This can make it harder for policymakers to shift China’s growth model towards stronger domestic consumption.
China’s economy slowed to 4.3% growth in the second quarter, and recent data suggest that external demand may continue to play an important role in offsetting soft domestic consumption and weak investment.
That creates a difficult policy challenge. A more balanced growth model requires stronger domestic demand, but the property downturn continues to weigh on household confidence and investment.
Why Local Government Finances Are Also Under Pressure
The property downturn can affect local government finances because land-related activity has historically been an important part of local economic and fiscal structures.
When property developers reduce land purchases and construction, local governments can face weaker income associated with the property sector.
That can make it harder for local authorities to provide strong economic support at a time when policymakers are already trying to boost investment and stabilise growth.
This is one reason the property market is closely linked to China’s broader fiscal and economic policy debate.
Oxford Economics Sees a Prolonged Housing Downturn
Sheana Yue, senior economist at Oxford Economics, expects China’s housing downturn to persist through the current Five-Year Plan, with residential investment not recovering until 2031.
She also said a more proactive policy response is increasingly needed to revive domestic demand and lowered the firm’s 2027 growth forecast to 4.3%.
The forecast reflects the possibility that a prolonged property downturn could keep economic growth subdued even as public investment becomes stronger.
Such forecasts highlight the possibility that China’s housing adjustment may be a multi-year process rather than a short-term correction.
Can China’s Property Stimulus Create a Sustainable Recovery?
Policymakers face a difficult balancing act. They need to prevent further deterioration in the property market without simply recreating the conditions that contributed to excessive developer borrowing and speculative activity.
Measures that improve mortgage affordability and developer financing can help, but they need to be accompanied by stronger confidence among households and greater certainty around project completion.
A sustainable recovery would ideally involve healthier property demand rather than simply a temporary increase in transactions caused by short-term incentives.
Three Factors That Could Determine the Recovery
- Homebuyer confidence: Households need greater confidence in employment, income and housing-market stability.
- Project completion: Buyers need confidence that homes purchased through development projects will be completed.
- Local policy execution: Stabilisation measures need to be implemented effectively across different cities and regions.
What China’s Property Market Means for Economic Growth
The August housing data suggest that the property sector will probably remain an important factor in China’s economic outlook.
If housing prices stabilise in major cities and buyer confidence gradually improves, property activity could eventually become less of a drag on growth. But if smaller markets continue to weaken and households remain reluctant to borrow, the recovery could remain uneven for an extended period.
The distinction between stabilisation and recovery is particularly important. A slower decline in prices is positive compared with a rapidly worsening market, but it does not necessarily mean that construction, sales and investment have returned to healthy levels.
Key Risks for China’s Economy
Prolonged Property Weakness
A multi-year property downturn could continue to weigh on investment, construction and household confidence.
Weak Consumer Demand
If households remain cautious because of housing and employment concerns, domestic consumption may struggle to become a stronger growth engine.
Declining Household Borrowing
Continued contraction in household loans suggests that lower financing costs alone may not be enough to encourage stronger housing demand.
Uneven Regional Recovery
Improvement in tier-one cities may not be sufficient to offset continued weakness across tier-two and tier-three markets.
Pressure on Local Governments
Weak property activity can reduce the financial strength of local governments and complicate broader fiscal support efforts.
What to Watch Next
Investors and economists will closely monitor whether the stabilisation seen in major cities spreads to smaller markets and whether property sales and construction activity begin to improve.
- Monthly movement in new and resale home prices.
- Property sales and new construction starts.
- Residential investment.
- Household mortgage and other loan demand.
- Government measures supporting homebuyers and developers.
- Consumer confidence and domestic spending.
- Implementation of local housing-market stabilisation policies.
Conclusion
China home prices remain weak, although August data provide some evidence that the pace of decline is moderating. New home prices fell 0.1% month-on-month, while the annual decline narrowed to 3.0% from 3.2% in July.
The improvement is most visible in China’s largest cities, where tier-one new home prices rose 0.1% in August. However, tier-two and tier-three cities continued to decline, showing that the housing recovery remains uneven.
More concerning for the wider economy is the weakness in property sales, investment and construction, combined with shrinking household borrowing. These trends can weigh on consumer confidence, local government finances and domestic demand.
Beijing has introduced measures to improve developer financing, strengthen homebuyer confidence and extend mortgage-loan terms, but analysts do not expect these measures alone to deliver an immediate nationwide recovery.
The central question for China’s economy is therefore whether policymakers can turn signs of stabilisation in major cities into a broader recovery in housing demand and domestic consumption. Until that happens, the property sector is likely to remain one of the most important constraints on China’s economic growth outlook.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0