Some of the world’s largest bond fund managers are taking a cautious approach to a volatile fixed-income market, favoring shorter-duration and higher-quality securities while remaining selective about corporate debt. The strategy reflects a year in which rising Treasury yields, inflation concerns, fiscal uncertainty, geopolitical risks and the rapid growth of artificial intelligence spending have created a difficult environment for bond investors.
Reuters spoke with eight senior investment professionals overseeing nearly $700 billion collectively. While their individual strategies differ, a common theme emerged: rather than making large bets on the direction of interest rates or the economy, many managers are focusing on security selection, income and risk management.
Higher Bond Yields Provide a Cushion
One of the more important changes in the bond market is the higher level of starting yields. The Bloomberg Aggregate Index, a widely followed measure of the US investment-grade bond market, was down about 1% for the year, according to the Reuters report.
That performance represents a difficult year for fixed income, although many active managers have performed better than the benchmark while still recording negative returns year to date.
Higher yields, however, provide investors with more income than they received when yields were much lower. Bond prices generally move in the opposite direction to yields, so rising yields can create price losses. But the income generated by higher coupons and yields can help offset those losses over time.
Several managers interviewed by Reuters therefore see today’s starting yields as an important source of potential return, even amid significant market volatility.
Why Bond Managers Are Avoiding Big Macro Bets
The current market presents multiple sources of uncertainty. Treasury yields have risen partly because of concerns about inflation and government deficits. Meanwhile, geopolitical developments can quickly change expectations for economic growth, inflation and monetary policy.
Corporate bonds also present valuation concerns. Some managers believe investors are not always receiving enough additional yield to compensate for the risks associated with lower-quality or highly leveraged borrowers.
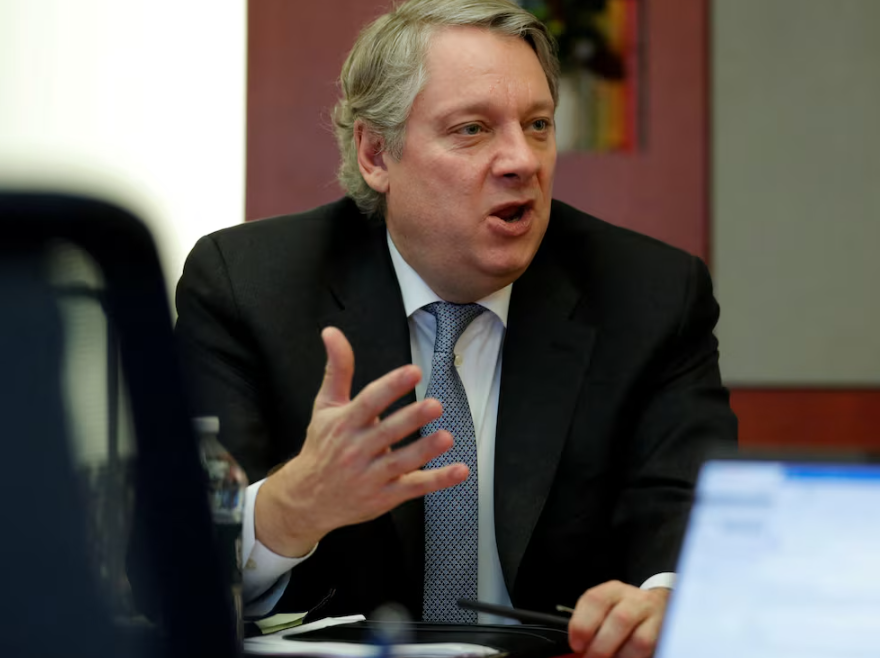
Arvind Narayan, co-head of investment-grade credit at Vanguard, summarized the cautious approach by saying that investors should be selective and careful about where they take risk.
Rather than trying to predict every major economic or political development, the managers interviewed by Reuters are generally concentrating on individual securities and segments where they believe the compensation for risk is more attractive.
Short-Term Bonds Attract Attention
Short-duration bonds are among the most common preferences among the managers Reuters interviewed. Shorter-term securities generally have less sensitivity to changes in interest rates than longer-duration bonds.
That characteristic can be valuable when the future path of monetary policy is uncertain. If yields rise, shorter-duration securities generally experience smaller price declines than comparable longer-duration bonds, although they also need to be reinvested sooner.
Narayan said short-dated bonds currently offer attractive all-in yields. His strategy emphasizes diversified exposure to high-quality shorter-term assets, including investment-grade corporate bonds, asset-backed securities and agency mortgage-backed securities.
Julian Potenza of Fidelity Investments is also favoring short-term, high-quality spread assets while keeping credit risk near the lower end of his team’s historical range.
High-Quality Credit Is a Central Theme
Investment-grade credit is another area receiving attention from several major bond managers. The objective is to generate income while limiting exposure to borrowers whose financial condition could deteriorate if economic conditions worsen.
Warren Pierson of Baird Asset Management said his team is pursuing a conservative fixed-income strategy focused on bottom-up security selection. His portfolio favors shorter-dated corporate securities, selected non-agency mortgages and highly rated securitized assets.
Ed Fitzpatrick of JPMorgan Asset Management has also increased allocations to investment-grade and securitized credit while remaining cautious about some of the newer corporate debt being issued to finance artificial intelligence investment.
Why AI-Related Debt Is Under Scrutiny
The rapid expansion of artificial intelligence infrastructure has created enormous financing needs. Technology companies and other businesses involved in the AI ecosystem have turned to debt markets to fund data centers, computing capacity and related infrastructure.
That increase in issuance has created a new source of risk for bond investors. Large amounts of debt can enter the market within a relatively short period, forcing investors to examine whether the additional yield adequately compensates them for the underlying credit risk.
Narayan described AI spending as a major issue for bond investors and said Vanguard works directly with issuers to negotiate deal terms.
Several other managers interviewed by Reuters expressed similar caution. Potenza said his team has been selective about AI-related debt, while Fitzpatrick is waiting for potentially more attractive yields. Greg Peters of PGIM Credit also said higher yields on AI-related debt do not automatically make those securities appealing.
PIMCO Sees Opportunities in Mortgages and Treasuries
Dan Ivascyn, chief investment officer at PIMCO, manages the $231.8 billion PIMCO Income Fund, the largest actively managed bond fund mentioned in the Reuters report.
Ivascyn said the market is being shaped by several risks, including geopolitical developments and the economic consequences of the AI spending boom. Instead of relying on one large market call, his approach has involved identifying individual opportunities.
He currently sees opportunities in asset-backed securities and residential mortgage-backed securities, while considering corporate bonds relatively expensive.
Ivascyn also sees opportunities in longer-dated US Treasury bonds. He pointed to the Federal Reserve’s efforts to control inflation as a positive signal for the bond market.
Longer-Term Treasuries Attract Some Managers
Although several managers favor shorter-term bonds, not all are avoiding longer-duration US government debt.
Pramod Atluri of Capital Group has found longer-dated Treasuries more attractive after rates moved higher. His approach is described as gradually contrarian, meaning he is willing to increase exposure when market prices create what he considers more attractive opportunities.
The appeal of longer-term Treasuries is closely connected to their higher yields. If inflation and interest-rate expectations stabilize or decline, longer-duration bonds can benefit from falling yields and rising prices. Conversely, they can experience larger price declines if yields rise further.
This creates a key difference between the strategies of the managers interviewed by Reuters: some prefer to minimize duration risk, while others are willing to take longer-term interest-rate exposure when yields appear sufficiently attractive.
BlackRock Focuses on Income and Credit Quality
Russell Brownback, deputy chief investment officer of global fixed income at BlackRock, emphasized the resilience provided by higher yields.
Brownback described the relationship between market volatility and bond income as a contrast between short-term price movements and the longer-term benefit of earning interest. The idea is that higher carry can help investors withstand periods of daily price volatility.
His team sees opportunities in carefully selected mortgages and securitized credit but is paying close attention to lower-quality high-yield bonds and subprime asset-backed securities for signs of financial stress.
This approach reflects a broader theme among the managers: the objective is not simply to find the highest yield available, but to assess whether the yield adequately compensates for the risk of losses.
PGIM Warns Against Broadly Buying Corporate Credit
Greg Peters, co-chief investment officer at PGIM Credit, favors careful security selection and disciplined risk management.
His approach reflects concerns that broad exposure to corporate credit may not provide sufficient compensation for the risks currently present in the market.
Peters is increasing exposure to residential mortgage-backed securities but remains cautious about AI-related corporate debt despite the higher yields attached to some new issues.
The distinction is important because two bonds with similar yields can have very different risk profiles depending on the issuer, collateral, maturity, structure and economic conditions.
Fidelity Favors “Boring” Credit
Julian Potenza of Fidelity Investments is keeping credit risk near the low end of his team’s historical range and favoring shorter-term, higher-quality spread assets.
His comments reflect the idea that relatively unexciting securities can become attractive when investors are being adequately compensated for taking limited risk.
Potenza has been selective about large AI-related debt issues. The rapid increase in financing by companies connected to the AI investment cycle has created substantial issuance, but additional yield alone is not enough to persuade his team to take on greater credit risk.
JPMorgan Waits for Better Opportunities
Ed Fitzpatrick, portfolio manager and head of US rates strategy at JPMorgan Asset Management, said opportunities are less abundant than they have been in the past.
His fund has increased exposure to investment-grade and securitized credit, but he remains less interested in some AI-linked corporate debt issues.
One factor is the enormous size of some new transactions. Large AI-related debt deals can reach a scale that makes them comparable with major Treasury issues, creating questions about supply, concentration and pricing.
Fitzpatrick is waiting for higher yields that could potentially provide better compensation for the risks associated with those securities.
Baird Takes a Conservative Fixed-Income Approach
Warren Pierson of Baird Asset Management is using a bottom-up strategy focused on generating returns through many individual positions rather than relying on a single large market prediction.
His team is underweight longer-term Treasuries and prefers shorter-dated corporate securities, selected non-agency mortgages and highly rated securitized assets.
This approach is consistent with the broader preference among several managers for securities where the credit quality is easier to assess and interest-rate sensitivity is more limited.
Eight Bond Managers, One Common Theme
The strategies described by the eight managers differ, but several common themes emerge from their comments.
- Higher starting yields: Rising yields provide more income and can cushion bond-price declines.
- Shorter duration: Several managers favor shorter-term securities to limit interest-rate sensitivity.
- High-quality credit: Investment-grade and highly rated securitized assets remain central to many strategies.
- Selective mortgage exposure: Residential and other mortgage-related securities are attracting interest from several managers.
- Caution on AI debt: Rapid issuance related to artificial intelligence infrastructure is receiving close scrutiny.
- Limited macro bets: Managers are generally emphasizing security selection rather than relying on a single major market prediction.
- Risk management: Several managers are maintaining relatively conservative credit exposure amid uncertain economic conditions.
Why Starting Yields Matter for Bond Investors
Starting yield is an important component of expected bond returns because investors receive income over the life of a security. When yields begin at higher levels, the income component can provide a larger cushion against price volatility.
This is particularly relevant in the current environment because Treasury yields have risen significantly compared with the extremely low-yield environment that followed the global financial crisis.
However, higher yields do not eliminate risk. If inflation remains persistent, interest rates rise further or credit conditions deteriorate, bond prices can fall. Credit-sensitive securities can also suffer losses if investors become concerned about an issuer’s ability to repay its debt.
Bond Market Risks Remain Broad
The managers interviewed by Reuters identified risks ranging from fiscal policy and inflation to geopolitical developments and the economic effects of AI investment.
Changes in government borrowing can affect Treasury supply and yields. Geopolitical events can influence energy prices and inflation expectations. Meanwhile, a sharp change in expectations surrounding AI investment could affect the companies and debt instruments connected to the technology boom.
These factors make it difficult for bond investors to rely on a single economic forecast. The strategies described by the managers instead emphasize diversification, security selection and careful control of interest-rate and credit exposure.
What the Bond Market Strategy Means for Investors
The comments from the major bond managers illustrate how professional fixed-income investors are navigating a market with both attractive yields and significant uncertainty.
Higher yields have improved the income available from bonds, but the same rise in yields has created price volatility. Investors therefore face a trade-off between earning more income and managing the potential impact of further changes in interest rates and credit conditions.
For many of the managers interviewed by Reuters, the response is to focus on securities with stronger credit quality, shorter maturities or structures that provide attractive income without requiring large directional bets.
Frequently Asked Questions
Why have bond markets been volatile in 2026?
Bond markets have faced uncertainty over inflation, government deficits, interest rates, geopolitical developments and the economic consequences of the rapid growth in artificial intelligence investment.
What is the Bloomberg Aggregate Index?
The Bloomberg Aggregate Index is a widely followed benchmark for the US investment-grade bond market. The Reuters report said it was down about 1% for the year.
Why do higher bond yields matter?
Higher yields can provide investors with more interest income, which may help offset some of the price declines that occur when yields rise.
Why are many bond managers favoring short-term securities?
Shorter-term bonds generally have lower interest-rate sensitivity than longer-term bonds, making them less exposed to price declines caused by further increases in yields.
Why are bond managers cautious about AI-related debt?
The rapid expansion of AI infrastructure has resulted in significant corporate debt issuance. Several managers interviewed by Reuters believe investors need to assess whether the additional yield sufficiently compensates for the risks.
Which types of securities are attracting interest?
Several managers cited investment-grade corporate bonds, asset-backed securities, residential mortgage-backed securities, agency mortgage-backed securities and selected securitized assets.
Are all major bond managers avoiding long-term Treasuries?
No. While several managers prefer shorter-duration assets, Dan Ivascyn of PIMCO and Pramod Atluri of Capital Group see opportunities in longer-dated Treasury bonds at current yield levels.
What is the main strategy described by the bond managers?
The managers generally emphasize selective security selection, higher-quality assets, income generation and disciplined risk management rather than relying on large directional bets about the economy or interest rates.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0