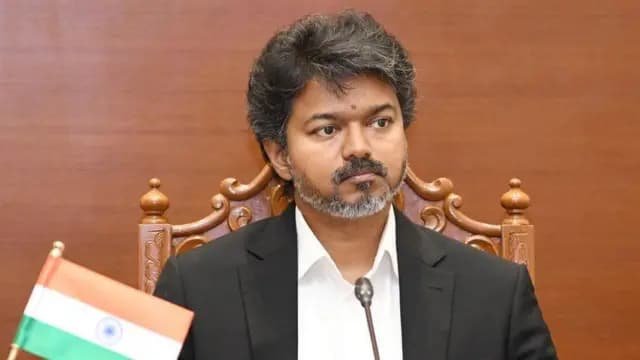
DMK leader and former Tamil Nadu Finance Minister Thangam Thennarasu has questioned the TVK government’s claim of reduced borrowing, arguing that lower debt issuance alone does not establish better financial management. He has called on Chief Minister C. Joseph Vijay’s administration to disclose its capital expenditure, progress on infrastructure projects and pending payments to contractors.
The dispute follows reports that Tamil Nadu’s borrowing through government bonds fell by 21% during the first half of the current financial year compared with the corresponding period a year earlier. Thennarasu has argued that the reduction needs to be examined alongside actual government spending and the status of development works.
Why Thangam Thennarasu Is Questioning the Debt Figures
Thennarasu’s central argument is that a decline in borrowing cannot be evaluated in isolation. According to the DMK leader, the government should explain whether the lower borrowing reflects improved fiscal management or a slowdown in expenditure on infrastructure and other development projects.
In a post on X, he questioned the administration’s decision to present the reduction in borrowing as a major achievement without releasing detailed information about capital expenditure and the work undertaken during the first six months of the financial year.
“The TVK government is trying to present lower borrowing as a massive achievement,” Thennarasu said, according to the supplied report.
He also asked the government to publish complete details of capital expenditure and development activities during the April–September period. His demand places the focus on how much the state has actually spent, rather than only on how much it has borrowed.
The distinction matters because borrowing and expenditure measure different aspects of a government’s finances. Borrowing indicates how much money the government raises through debt, while capital expenditure tracks spending on assets and infrastructure. A decline in borrowing may have several explanations, and expenditure figures are needed to understand the broader fiscal picture.
DMK Cites Capital Expenditure Under Its Government
To support his criticism, Thennarasu referred to the capital expenditure allocation and spending recorded during the previous DMK government’s tenure.
He said the DMK government had allocated ₹57,231 crore for capital expenditure in the 2025–26 Budget. He also cited provisional monthly accounts of the Comptroller and Auditor General of India (CAG), claiming that ₹13,002.22 crore was spent between April and September 2025 on infrastructure projects, including the Metro Rail.
These figures form the basis of his demand for comparable information from the current administration. He has asked the TVK government to disclose the amount it has spent on capital projects during the first half of the current financial year and explain how that spending compares with its budgetary allocation.
However, the figures cited by Thennarasu relate to different financial periods: the ₹57,231 crore allocation refers to the 2025–26 Budget, while the ₹13,002.22 crore figure concerns spending between April and September 2025. A direct comparison with the current government’s performance requires corresponding expenditure data for the same period and a clear account of the budget provisions being compared.
Questions Over Pending Contractor Payments and Development Projects
Another major part of Thennarasu’s criticism concerns payments allegedly withheld for projects initiated during the previous DMK administration. He has asked the TVK government to disclose the total amount outstanding for ongoing projects and explain whether contractors have received payments for work already completed.
According to the former finance minister, lower borrowing should not be treated as a financial saving if it results from postponing development activity or delaying payments. He argued that the government needs to distinguish between genuine fiscal savings and a reduction in borrowing caused by spending less than planned.
Thennarasu raised the issue in particularly direct terms, asking whether the government could claim credit for financial management while delaying development works, withholding payments for completed projects and maintaining higher cash reserves.
His questions concern several related areas of public finance: whether infrastructure projects are progressing on schedule, whether bills submitted by contractors are being cleared, and whether the government is meeting its expenditure commitments. The answers would help establish whether lower borrowing reflects a change in the timing of spending or a broader improvement in the state’s financial position.
However, the allegations about delayed projects and unpaid contractor bills are claims made by Thennarasu. The supplied report does not include a detailed response from the TVK government or a project-by-project account of outstanding payments.
Why Tamil Nadu’s Capital Expenditure Matters
Capital expenditure is an important measure of how governments invest in infrastructure and long-term public assets. It can include spending on transport networks, public buildings and other infrastructure intended to support economic activity and public services.
Unlike routine administrative expenditure, capital investment can create assets that provide benefits over many years. Projects such as metro rail systems, roads and other public infrastructure can improve connectivity and expand the capacity of essential services when they are completed and put to use.
Capital expenditure also has a practical connection with government borrowing. States may use a combination of revenue, transfers and borrowed funds to finance their budgets. If planned infrastructure spending is delayed, the immediate need to raise money may fall, even if the underlying projects and financial commitments remain.
That is why the 21% reduction in Tamil Nadu’s bond-market borrowing needs to be considered alongside actual expenditure. The borrowing figure alone does not establish whether projects have been completed, whether investment has slowed or whether the state has improved its overall fiscal position.
At the same time, lower borrowing is not automatically evidence of reduced development spending. Governments can also borrow less because of stronger receipts, changes in cash management, adjustments to the timing of debt issuance or other financial factors. A fuller assessment requires data on both revenue and expenditure.
For this reason, the capital expenditure figures sought by Thennarasu would provide one important part of the picture, but they would need to be considered alongside revenue collections, the fiscal deficit, outstanding liabilities and the progress of major projects.
₹48,000 Crore Borrowing Plan for October–December
Thennarasu also pointed to the TVK government’s planned borrowing for the October–December quarter. According to the figures cited in his statement, the administration intends to raise ₹48,000 crore during the three-month period, compared with ₹23,500 crore raised in the preceding quarter.
The proposed amount is more than double the earlier quarter’s borrowing. Thennarasu questioned how the government could present lower borrowing in the first half of the financial year as a major achievement while planning a substantially larger borrowing programme for the following quarter.
The figures highlight the importance of looking at borrowing over more than one reporting period. A lower amount raised between April and September does not necessarily mean that the state’s total financing requirement has fallen for the full financial year. Debt issuance can vary from quarter to quarter according to funding requirements and the timing of expenditure.
The planned ₹48,000 crore borrowing is a forward-looking figure, however, and should not be confused with money already raised. The supplied report does not establish how much of that amount has subsequently been borrowed or whether the plan has changed.
To assess the government’s borrowing strategy, it would be necessary to compare the planned issuance with actual borrowing, the state’s cash position, expected revenue receipts and the expenditure scheduled for the remaining months of the financial year.
What Information the TVK Government Is Being Asked to Release
Thennarasu’s questions point to several specific disclosures that could help clarify the state’s financial position. Rather than relying on the borrowing figure alone, the government could provide comparable information covering the first half of the current financial year.
- Actual capital expenditure: The total amount spent between April and September 2026, compared with the allocation in the 2026–27 Budget.
- Spending on new infrastructure: The amount directed towards new projects and the progress made on those initiatives.
- Outstanding contractor payments: The value of bills pending for completed work and the payments due for ongoing projects.
- Project implementation: Details of delayed, suspended or completed infrastructure projects, including those started under the previous administration.
- Borrowing and cash management: Actual bond-market borrowing during the first half, the planned borrowing for the next quarter and the reasons for any changes.
- Revenue performance: Actual receipts compared with budget estimates, helping explain how available funds relate to the government’s spending commitments.
Such information would allow comparisons between budgeted expenditure and actual spending. It would also help distinguish between money allocated on paper, expenditure recorded in government accounts and payments still due to contractors.
What the Dispute Means for Tamil Nadu’s Finances
The exchange between the DMK and the TVK government centres on a broader question of fiscal accountability: how should a government demonstrate that it is managing public money effectively?
Borrowing is one part of that assessment, but it cannot provide a complete answer on its own. A meaningful evaluation also considers how much revenue the state collects, how funds are spent, whether infrastructure projects deliver their intended benefits and whether financial obligations are being met on time.
For the government, a lower borrowing requirement could be presented as a positive development if it reflects stronger revenues, effective cash management or sustainable adjustments to expenditure. Establishing that explanation requires supporting financial data.
For the opposition, the key concern is whether lower borrowing has come at the cost of delayed development projects or unpaid bills. Those allegations would need to be tested against official expenditure records, payment data and project-level information rather than accepted solely on the basis of a political statement.
The timing of the planned borrowing also makes the issue relevant beyond the first half of the financial year. If the government raises substantially more money in the October–December quarter, the reasons for that increase will be important in understanding its financing needs and expenditure schedule.
Conclusion
DMK leader and former Finance Minister Thangam Thennarasu has challenged the TVK government’s presentation of a 21% decline in Tamil Nadu’s first-half bond borrowing as a financial achievement. He has demanded details of capital expenditure, new infrastructure spending and outstanding contractor payments to establish how the reduction came about.
His criticism also draws attention to the government’s reported plan to borrow ₹48,000 crore in the October–December quarter, compared with ₹23,500 crore in the preceding quarter. The planned increase raises questions about how the state’s borrowing needs may change during the rest of the financial year.
The central issue remains unresolved in the supplied report. A clearer assessment will depend on the TVK government’s expenditure figures, revenue performance, borrowing records and disclosures about pending project payments. Until those details are examined together, the decline in borrowing alone cannot determine whether Tamil Nadu’s fiscal management has improved or whether development spending has been delayed.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest India on thefoxdaily.com.

COMMENTS 0