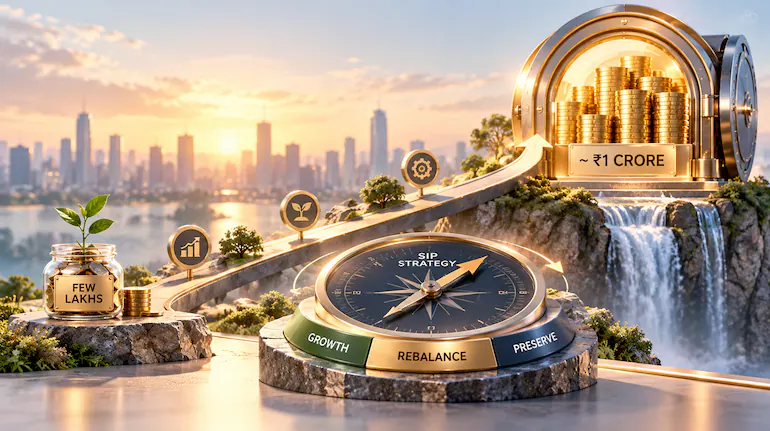
Systematic Investment Plans (SIPs) help investors build wealth gradually by investing a fixed amount in Mutual Funds at regular intervals. But as a portfolio grows from a few lakh rupees to Rs 50 lakh or even Rs 1 crore, the investment risks and financial priorities can change significantly.
A strategy that worked well when an investor was starting out may not remain suitable after years of wealth creation, particularly when financial responsibilities increase or major goals approach. Investors may therefore need to reassess their mutual fund holdings, asset allocation and exposure to market volatility as their SIP corpus grows.
The key is not to change investments simply because the portfolio has become larger. Instead, the focus should shift towards ensuring that the accumulated wealth remains aligned with financial goals, investment timelines and the amount of risk an investor can afford.
Why a Growing SIP Corpus Requires a Different Approach
The impact of market fluctuations becomes more significant as the investment corpus increases. For example, a 20% decline in a mutual fund portfolio worth Rs 3 lakh results in a loss of Rs 60,000. The same percentage decline in a Rs 1 crore portfolio would reduce its value by Rs 20 lakh.
Although the percentage fall is identical, the financial impact is considerably different. A larger portfolio means investors have more accumulated wealth exposed to market movements.
According to Aditya Agarwala, Chief Investment Officer and Co-Founder at Investvalue Capital, investors should gradually move their attention from monthly contributions and fund selection towards asset allocation and concentration risk.
In the early years of investing, regular SIP contributions play a major role in building the portfolio. During market corrections, investors can also accumulate more mutual fund units at lower prices. However, as the corpus grows, market performance increasingly influences the overall value of investments.
This makes portfolio management more important than simply continuing the same investment pattern without reviewing it.
Shift Focus from Fund Selection to Asset Allocation
Investors often concentrate on selecting mutual funds with strong historical returns when their portfolios are relatively small. However, as wealth accumulates, the balance between different asset classes becomes increasingly important.
For instance, a portfolio heavily invested in small-cap or thematic funds may have delivered attractive returns during a favourable market cycle. But maintaining the same exposure as the corpus grows could expose a substantial amount of accumulated wealth to sharp market fluctuations.
Investors should therefore examine whether their portfolio is sufficiently diversified across equity, debt and other suitable asset classes. They should also review overlapping holdings, expense ratios and the potential losses their investments could experience during market corrections.
Holding several mutual funds does not automatically mean a portfolio is diversified. Different schemes may own many of the same stocks, creating concentration risk even when an investor believes their money is spread across multiple funds.
When Should Investors Reassess Their SIP Strategy?
There is no universal corpus level at which every investor should change their investment strategy. A portfolio worth Rs 50 lakh could represent a major portion of one person’s savings, while it may be relatively small compared with another investor’s overall wealth.
Agarwala suggests reviewing the portfolio when its value reaches approximately five times the investor’s annual SIP contributions. At this stage, market movements can begin to influence the corpus more significantly than fresh investments.
However, the size of the portfolio should not be the only consideration. Major life events can also change an investor’s ability to take financial risks.
Marriage, having children, taking a home loan, supporting ageing parents or approaching retirement can all affect investment priorities. Someone who previously had few financial responsibilities may need a more balanced portfolio after taking on additional commitments.
The important question is whether the existing asset allocation still matches the investor’s financial goals and the time available to achieve them.
Should Equity Exposure Reduce as Financial Goals Approach?
Equity investments can offer long-term growth potential, but they are also exposed to market volatility. Investors with distant financial goals generally have more time to manage market fluctuations than those who need their money within a few years.
For example, someone saving for retirement that is 20 years away may be able to tolerate greater equity exposure. In contrast, an investor who needs Rs 30 lakh for a child’s education in three years may have less flexibility to wait for markets to recover after a downturn.
Agarwala recommends gradually reducing investment risk as financial goals approach. The suggested allocation can vary according to the time remaining before the money is required.
- More than seven years: An equity-heavy allocation may be appropriate for long-term goals, depending on the investor’s risk tolerance.
- Five to seven years: Investors can begin increasing their debt allocation to reduce dependence on equity market performance.
- Three to five years: An equity allocation of around 50–60% in the goal-specific portfolio may be considered, with the remaining amount allocated to debt investments.
- One to three years: Investors can gradually move most of the amount required for the goal into relatively lower-risk options, such as suitable short-duration debt or liquid funds.
These are illustrative guidelines rather than fixed rules. The appropriate allocation depends on individual circumstances, risk tolerance and whether the financial goal can be postponed or adjusted.
How a Successful SIP Portfolio Can Become Risky
A portfolio that was suitable when an investor started investing may become too aggressive as financial responsibilities increase.
Consider an investor who began SIPs at the age of 30 with a monthly contribution of Rs 25,000 and an equity allocation of 85%. Over the next 12 years, the portfolio grows to approximately Rs 1.3 crore.
During this period, the investor takes on a home loan, begins supporting dependent parents and plans to fund a child’s education, which is expected to cost Rs 40 lakh in five years. Despite these changes, nearly 90% of the portfolio remains invested in equities, with substantial exposure to mid-cap and small-cap funds.
A 30% decline in the equity portion could reduce the portfolio’s value by approximately Rs 35 lakh. Such a fall could create difficulties if the investor needs to withdraw money for the child’s education during the market downturn.
The original investment strategy may have been appropriate when the investor had a longer time horizon and fewer financial commitments. But the circumstances have changed, making a portfolio review necessary.
One approach would be to separate the money required for education from the investments intended for long-term retirement goals. This allows the investor to reduce risk in the goal-specific portfolio without unnecessarily changing the allocation of the entire corpus.
Review Your Portfolio Even If You Continue the Same SIPs
Continuing existing SIPs does not guarantee that a portfolio will maintain its intended asset allocation. Market movements can gradually change the proportion of equity and debt investments.
For example, if equity funds perform strongly over several years, their share of the overall portfolio may increase beyond the investor’s original target. This can leave the portfolio carrying more risk than intended, even if the investor has not changed any investments.
Agarwala recommends reviewing the portfolio annually or whenever its asset allocation moves more than 10 percentage points away from the intended target.
Investors can consider using fresh SIP contributions to restore the desired balance. This may help reduce the need for unnecessary redemptions or switches between funds. However, any decision to sell or switch mutual fund units should account for applicable capital gains taxes.
Why Investors Should Not Stop SIPs Simply Because Their Corpus Has Grown
A larger investment corpus does not automatically mean that investors should stop SIPs or move their entire portfolio away from equities. The right decision depends on the purpose of the investments and the time remaining before the money is needed.
Investors with long-term goals may still benefit from continuing equity SIPs, provided their allocation remains consistent with their risk tolerance. Those approaching important financial milestones may need to direct new contributions towards debt or other relatively lower-risk investments.
The objective is to protect money needed for near-term expenses while allowing long-term investments to continue growing. Separating investments according to financial goals can help investors avoid making broad changes to their portfolios based only on short-term market movements.
An SIP Is a Habit, but Your Investment Strategy Must Evolve
Regular investing is an important part of long-term wealth creation, but a successful SIP journey also requires periodic portfolio reviews. As the corpus increases, investors need to pay greater attention to asset allocation, concentration risk, financial responsibilities and withdrawal timelines.
Aditya Agarwala summarises the principle by saying, “An SIP is a habit, not a strategy. The strategy has to evolve as your wealth and responsibilities grow.”
For investors whose portfolios have grown substantially, the next step should not necessarily be finding new mutual funds or increasing returns at any cost. It should be checking whether the existing investments are still suitable for their financial goals.
Ultimately, a well-managed SIP portfolio is not just about accumulating a large corpus. It is about ensuring that the money remains available when needed, while keeping investment risks at a level the investor can reasonably manage.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0