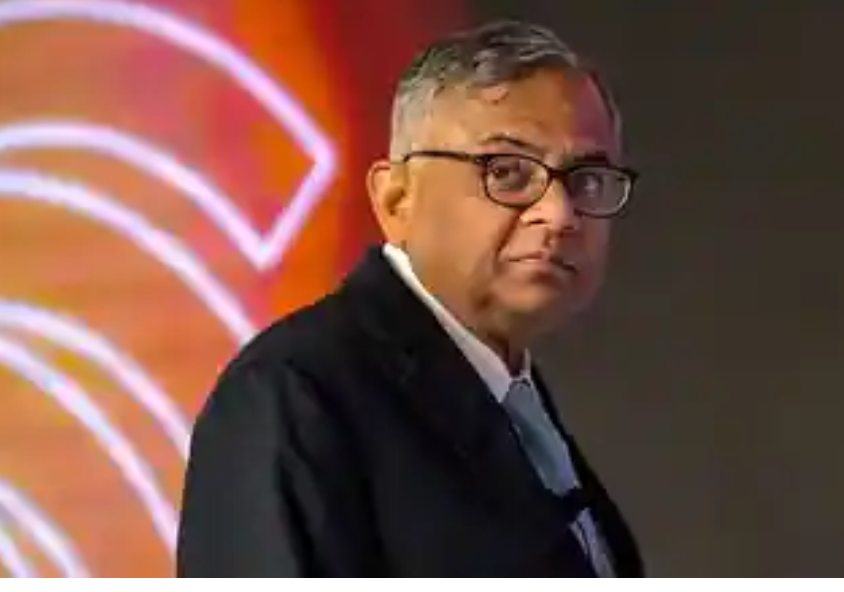
Tata Trusts has challenged the validity of the September 17, 2026, board resolution to reappoint N Chandrasekaran as chairman of Tata Sons, arguing that the decision did not receive the mandatory support required under the company’s Articles of Association (AoA). The Trusts said one of its two nominee directors voted against the resolution, meaning the specific approval condition was not satisfied.
The dispute raises questions about the interpretation of Tata Sons’ internal governance rules, the voting rights of Tata Trusts’ nominees and the role of the board chairman’s casting vote. It also brings renewed attention to the relationship between Tata Sons’ governance framework and the wider debate over whether the holding company should be listed.
In a statement reported by ANI, Tata Trusts said the resolution was not validly passed. The position is the Trusts’ interpretation of the company’s governing documents; the supplied report does not establish that a court or regulatory authority has issued a final ruling on the latest dispute.
What Happened at the Tata Sons Board Meeting?
Tata Sons’ board considered a resolution on September 17, 2026, to reappoint N Chandrasekaran as chairman. Tata Trusts subsequently said the resolution did not meet a specific requirement in the company’s Articles of Association.
According to the Trusts, the AoA require the affirmative support of a majority of directors nominated by Tata Trusts. The Trusts hold approximately 66% of Tata Sons, and two Tata Trusts nominee directors sit on the board.
With two nominees, the Trusts argue that both directors would need to support the resolution for the separate approval condition to be met. One nominee voted against the resolution, the Trusts said, meaning the required affirmative support was absent.
The disagreement is therefore not simply about whether more directors voted for or against the resolution overall. Tata Trusts says the company’s governing documents impose an additional condition specifically involving its nominee directors.
Why Tata Trusts Says the Resolution Was Invalid
Tata Trusts’ position rests on its interpretation of the relevant provisions of Tata Sons’ Articles of Association. The Trusts says that the reappointment resolution needed affirmative support from a majority of its nominee directors, independently of the overall board vote.
Because there are two Tata Trusts nominees, the Trusts argues that both directors had to vote in favour. One director’s vote against the resolution meant that the required condition was not fulfilled.
This distinction is central to the dispute. A board resolution can receive sufficient support under a general voting process yet still face a question about whether an additional requirement in the company’s governing documents has been met.
The Trusts maintains that the special requirement cannot be treated as optional or overridden by a different voting mechanism. Its statement frames the issue as one of applying the AoA as written.
What does “affirmative support” mean?
In this context, affirmative support means a director must actively vote in favour of the resolution. It is different from merely avoiding a vote against it.
Where a company’s governing documents establish a special approval condition, the meaning and application of that condition can become important when a resolution is contested.
However, the supplied report does not reproduce the complete text of the relevant Articles of Association. It therefore does not provide enough detail to independently assess every possible interpretation of the voting requirement.
The Dispute Over the Chairman’s Casting Vote
Tata Trusts also rejected the argument that the chairman’s casting vote could resolve the problem. According to the Trusts, a casting vote is available only when there is an equality of votes at the overall board level.
The Trusts argues that this mechanism cannot be used to overcome the failure to satisfy the separate requirement concerning its nominee directors.
This creates two distinct questions:
- Was there an equality of votes at the overall board level that could trigger a casting vote?
- Even if a casting vote were available under the general board procedure, could it satisfy the separate approval condition for Tata Trusts’ nominees?
Tata Trusts’ position is that the second requirement cannot be replaced by the chairman’s casting vote. The company’s precise procedural position and the full voting record are not detailed in the supplied report.
Why the distinction matters
A casting vote is generally a mechanism used to resolve a tied decision, subject to the rules that govern the relevant board or organisation. A separate approval condition, by contrast, may require support from a particular category of directors.
If both provisions apply to the same resolution, the question becomes how they interact. Does the casting vote resolve only an overall tie, or can it also affect a special consent requirement?
Tata Trusts says the casting vote cannot override the latter. The issue ultimately depends on the wording and legal interpretation of the company’s Articles of Association and any applicable legal requirements.
“There Was No Paralysis and No Deadlock,” Says Tata Trusts
Tata Trusts rejected the suggestion that the board was paralysed or deadlocked. In its statement, the Trusts said the board had put a question to a vote and that the Articles of Association answered it in the negative.
The statement reflects the Trusts’ view that the outcome should be understood as the application of a defined governance condition rather than an inability of the board to function.
This distinction matters because a deadlock generally suggests that a decision-making body cannot reach a required decision. Tata Trusts, by contrast, argues that the relevant condition was not met and that the consequence follows from the governing rules.
The supplied report does not provide the complete board minutes or all arguments advanced by other parties. Accordingly, the Trusts’ description should be understood as its stated position in the dispute.
How the Cyrus Mistry Case Enters the Debate
Tata Trusts also referred to Supreme Court proceedings arising from the removal of former Tata Sons chairman Cyrus Mistry. The Trusts said Tata Sons had previously defended the affirmative voting rights of its nominee directors under Articles 104B and 121.
According to the Trusts’ account, the National Company Law Appellate Tribunal had held those rights to be oppressive. The Supreme Court subsequently accepted Tata Sons’ position and set aside that finding.
The Trusts argues that Tata Sons should not now disregard protections that it previously defended before the Supreme Court.
This reference is significant because it places the current disagreement within a longer-running discussion about the rights of Tata Trusts’ nominees and the structure of decision-making at Tata Sons.
Why earlier legal proceedings are relevant
When a company’s governance provisions have been examined in earlier litigation, those proceedings may become relevant to later disputes involving the same or related provisions.
However, the legal effect of an earlier judgment depends on what the court actually decided, the provisions it considered and how those findings apply to the later circumstances.
The supplied ANI report presents Tata Trusts’ interpretation of the earlier proceedings. It does not reproduce the Supreme Court judgment or provide a full legal analysis of whether the earlier decision directly determines the validity of the September 17 resolution.
That distinction is important: referring to a previous judgment is not, by itself, the same as establishing that the current dispute has already been legally resolved.
What Are Tata Sons’ Articles of Association?
Articles of Association are a company’s internal governing rules. They set out important aspects of how the company is organised and how decisions are made, subject to applicable law.
Depending on the company and its governing documents, the articles may address board composition, director appointments, voting procedures, committee structures and special approval requirements.
In the Tata Sons dispute, the relevant question concerns the provisions Tata Trusts says protect the affirmative voting rights of its nominee directors.
Such provisions can be particularly consequential when a company has shareholders with significant ownership interests and specific governance arrangements. They may define how particular decisions are approved and whether certain directors have additional rights or responsibilities.
Why the exact wording matters
corporate governance disputes often turn on the relationship between a document’s general rules and its specific provisions. A broad rule about board voting may operate alongside a separate condition for certain decisions.
To assess the current disagreement, the relevant questions include:
- What exactly do the applicable articles require?
- Which resolutions are covered by the special approval condition?
- How is a “majority” of nominee directors defined when there are two nominees?
- Does the casting-vote provision apply to the same decision or only to an overall board tie?
- What formal steps are available if the validity of a resolution is disputed?
The supplied report does not reproduce the complete provisions or establish how any formal challenge will proceed. These questions therefore remain central to understanding the disagreement.
Tata Trusts’ Position on Tata Sons’ Listing
The statement also addressed the debate over whether Tata Sons should be listed. Tata Trusts rejected the argument that listing would be necessary to strengthen corporate governance.
The Trusts pointed to existing governance provisions at Tata Sons, including independent directors, audit and nomination committees, related-party transaction rules, retirement of directors by rotation and insider-trading safeguards.
According to the Trusts, these standards were adopted voluntarily before the current dispute arose.
The argument is that governance standards can exist within an unlisted company and that listing is not the only possible route to formal oversight and internal controls.
This is the Trusts’ stated position. The supplied report does not provide a detailed comparison of Tata Sons’ governance arrangements with those of listed companies, nor does it independently assess the effectiveness of the safeguards cited.
Why the Listing Question Matters
The listing debate concerns the ownership and governance structure of Tata Sons, the holding company at the centre of the Tata Group. Whether a company is listed can affect its disclosure obligations, shareholder base, market scrutiny and access to public capital, depending on the applicable rules.
Listing and corporate governance are related, but they are not identical concepts. A company may have internal governance policies and board committees without being publicly listed. Conversely, listing brings its own regulatory obligations and market-facing requirements.
The Tata Trusts statement argues that Tata Sons already has governance mechanisms and that these were voluntarily adopted. The broader question is how those mechanisms operate in practice and whether the existing framework meets the relevant legal and regulatory expectations.
The supplied report mentions a separate debate over listing and refers to the Reserve Bank of India in an accompanying related-news headline. It does not provide the full regulatory arguments or establish the current status of any listing-related process.
Governance Provisions Cited by Tata Trusts
Tata Trusts identified several mechanisms that it says form part of Tata Sons’ governance framework. Each addresses a different aspect of oversight and decision-making.
- Independent directors: Directors designated as independent can contribute perspectives distinct from those of company executives or controlling shareholders, subject to the applicable rules and their actual role.
- Audit committee: Audit committees typically oversee areas such as financial reporting and audit-related matters, according to their mandate.
- Nomination committee: Such committees commonly deal with matters involving board appointments, nominations and related governance processes.
- Related-party transaction rules: These provisions address transactions involving parties connected to the company and may establish approval or disclosure requirements.
- Retirement by rotation: Rotation provisions can provide a formal process for directors to periodically face retirement and possible reappointment.
- Insider-trading safeguards: These are intended to regulate trading and the handling of information covered by applicable insider-trading rules.
The existence of a governance mechanism does not, by itself, establish how effectively it operates. Its practical significance depends on the precise rules, implementation, oversight and compliance.
The Trusts’ statement uses these mechanisms to support its argument that listing is not essential to strengthening Tata Sons’ governance. The report does not provide an independent audit or evaluation of the arrangements.
What the Dispute Could Mean for Tata Sons
The immediate issue is the validity of the September 17 board resolution. Beyond that, the disagreement highlights the importance of clarity around director voting rights and special approval conditions.
For a company’s board, uncertainty over whether a resolution has been validly passed can create questions about the status of the decision and the process required to resolve the disagreement.
For shareholders and other stakeholders, the dispute may draw attention to how the company’s governing documents allocate decision-making authority.
However, the supplied report does not establish that the dispute has affected Tata Sons’ day-to-day operations, the functioning of its businesses or any specific commercial decision. Those consequences should not be assumed without further information.
Key Questions That Remain Unanswered
Several details would help clarify the dispute as it develops:
- Full voting record: What were the complete voting results at the September 17 meeting?
- Exact AoA wording: What do the relevant provisions say about nominee-director support and casting votes?
- Company response: How does Tata Sons respond to Tata Trusts’ interpretation?
- Formal next steps: Will the parties seek a legal or other formal determination?
- Reappointment status: How will the company treat the resolution while its validity is disputed?
- Listing debate: What are the current regulatory and company positions on whether Tata Sons should be listed?
The supplied report does not answer all of these questions. Further statements, board documents or legal proceedings may be needed to establish the full position.
Conclusion: A Dispute Over Governance Rules and Board Approval
Tata Trusts has challenged the validity of N Chandrasekaran’s reappointment as Tata Sons chairman, arguing that the September 17, 2026, resolution did not receive the affirmative support required from its nominee directors under the company’s Articles of Association.
The Trusts says one of its two nominees voted against the resolution, that the chairman’s casting vote cannot override the separate approval condition and that the board was not paralysed or deadlocked. It has also invoked the earlier Cyrus Mistry litigation to support its position on nominee-director voting rights.
The statement further rejects the claim that listing Tata Sons is necessary to strengthen corporate governance, pointing to existing provisions and safeguards that the Trusts says were voluntarily adopted.
The central issue remains the interpretation and application of Tata Sons’ governing documents. Tata Trusts has clearly stated its position, but the supplied report does not establish a final independent legal determination of the September 17 resolution’s validity.
Further clarity will depend on the complete Articles of Association, the board’s voting record, Tata Sons’ response and any formal steps taken to resolve the disagreement.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.
COMMENTS 0