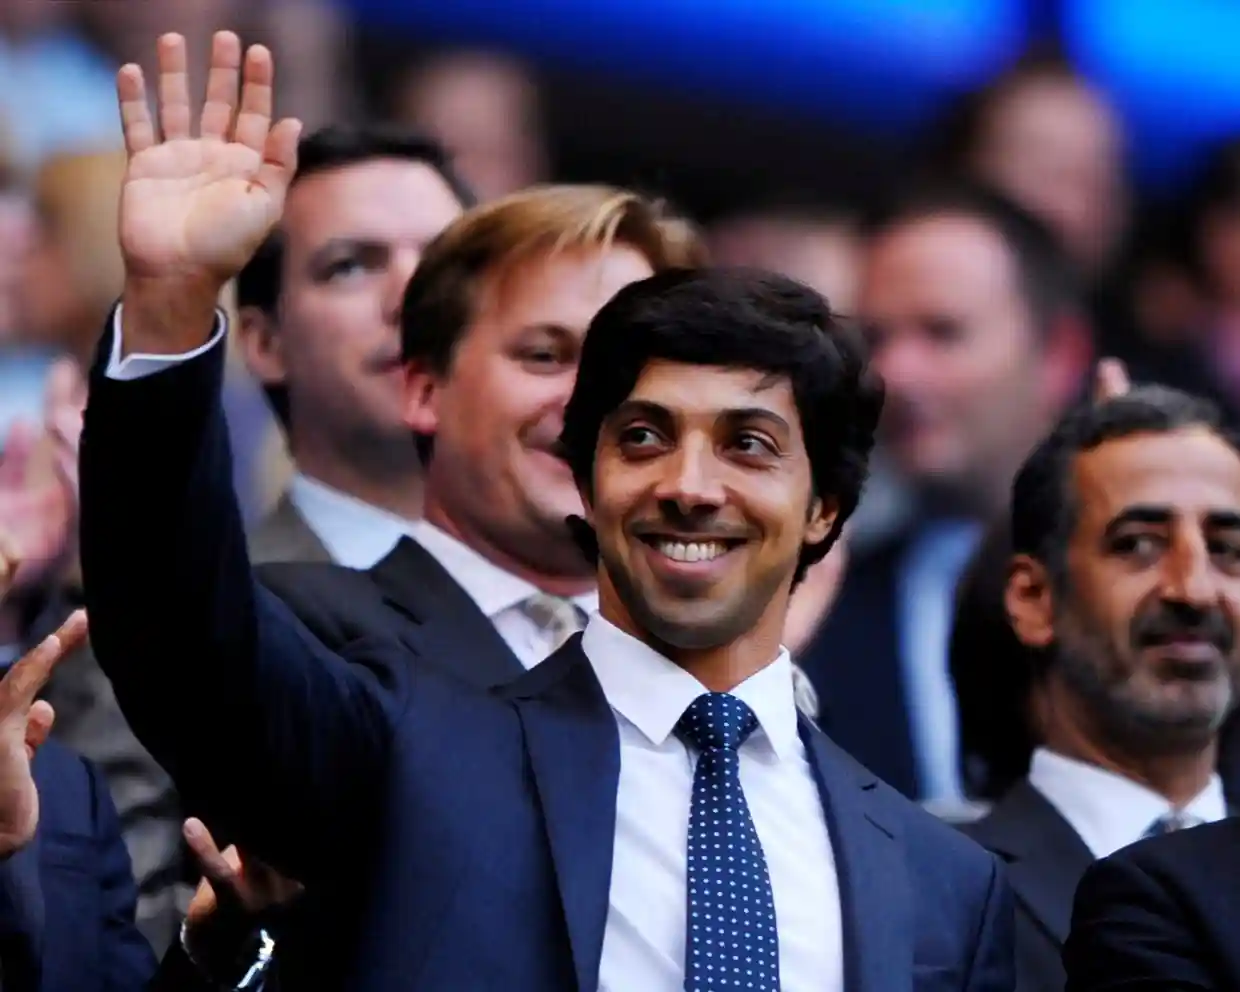
A £55 million loan provided to companies controlled by Manchester City owner Sheikh Mansour bin Zayed al-Nahyan is set to face scrutiny as councillors in Greater Manchester investigate a public-backed Housing fund established while Andy Burnham was mayor.
The loan was issued in 2017 to three companies ultimately controlled by Sheikh Mansour, the vice-president and deputy prime minister of the United Arab Emirates. The money helped finance Manchester Life, a major property development project that promised to deliver 6,000 homes in the city.
The investigation will examine the fund’s lending arrangements and decision-making process, including questions about why the companies qualified for public-backed financing. The Greater Manchester Combined Authority (GMCA) has confirmed that the loans were repaid in full, but it has not disclosed the interest rate or provided a detailed explanation of the eligibility decision in the information reported.
The scrutiny comes amid renewed attention on Burnham’s relationship with Manchester City’s Abu Dhabi owners and questions about a meeting with the club’s representatives before the loans were approved. Prime Minister Keir Starmer has called for full transparency over the relevant records.
Greater Manchester Committee to Investigate Housing Fund Loans
John Leech, a Liberal Democrat councillor in Manchester and chair of the GMCA’s overview and scrutiny committee, said the committee would investigate the fund that provided the £55 million loan.
The fund has distributed approximately £1 billion to around 50 developers since 2015, making the review broader than the financing provided to companies linked to Sheikh Mansour. The committee’s scrutiny is expected to focus on how lending decisions were made and whether the process followed the fund’s original objectives.
Leech told the BBC that the approval process had previously been criticised for being insufficiently clear. He questioned whether the criteria used to approve loans were consistently understood and whether applicants were treated according to a transparent process.
He also raised questions about why apparently successful businesses would need to borrow public money through the scheme, particularly when companies connected to wealthy investors might have access to alternative sources of finance.
Referring to the Abu Dhabi-linked companies, Leech said it was reasonable to ask why they required funding through the scheme when they might have been able to secure money elsewhere. He argued that the process needed to be examined against the fund’s original stated aims.
Leech said the committee wanted to establish that the lending system operated transparently rather than through an opaque decision-making process.
What Was the £55m Loan for Manchester Life?
The financing was provided in 2017 to three companies ultimately controlled by Sheikh Mansour. The money supported Manchester Life, a large housing development initiative that aimed to create 6,000 homes.
The project was presented as a significant opportunity to expand housing provision and support urban development in Manchester. Its financing has now become a focus of scrutiny because the public-backed fund provided substantial lending to companies associated with one of the world’s wealthiest families.
According to the GMCA, the loans have been repaid in full. However, repayment alone does not answer every question surrounding the original decision, including the terms on which the money was lent, the interest rate charged and how the companies met the scheme’s eligibility requirements.
The reported information does not establish that the loan was improper or that the recipients received preferential treatment. Those are questions that would require evidence about the lending criteria, the assessment of the applications and the decision-making process.
The central issue for the scrutiny committee is whether the funding was approved in accordance with the scheme’s rules and whether those rules were applied consistently to different developers.
Questions Over Burnham’s Meeting With Manchester City Owners
The loan investigation follows reports that Andy Burnham met Manchester City’s owners while receiving hospitality from the club at the Etihad Stadium several weeks before the financing was approved.
The meeting subsequently disappeared from public records before resurfacing in reporting last week, raising questions about the completeness of the records documenting Burnham’s engagements.
In response to the renewed scrutiny, Prime Minister Keir Starmer asked the Greater Manchester Combined Authority to carry out a manual review of Burnham’s meetings to ensure full transparency.
The request places the accuracy and completeness of official records at the centre of the controversy. Establishing what meetings took place, when they occurred and what was discussed could help clarify the timeline surrounding the loan approval.
However, the reported meeting and the subsequent disappearance of its record do not, by themselves, establish that the meeting influenced the financing decision. The available information does not demonstrate that Burnham personally approved the loan or that any improper arrangement took place.
The scrutiny committee’s examination of the fund and the review of meeting records are related through questions about transparency, but they concern distinct issues: how the loan was approved and whether public records adequately documented relevant engagements.
Burnham’s Earlier Comments About Manchester City’s Owners
Burnham, the former Greater Manchester mayor, has also faced criticism over comments defending Manchester City’s contribution to the city following a reported breach of the club’s financial rules.
He described the Abu Dhabi owners as having been a major partner in building modern Manchester and said he would be concerned about losing them from the sport.
Those remarks attracted renewed attention amid wider scrutiny of the club’s relationship with its owners. Critics questioned whether the city’s economic relationship with Manchester City had influenced the way its leadership discussed the club and its ownership.
The reported £55 million loan has intensified those questions because it involved public-backed financing for companies connected to the club’s owner. Nevertheless, the club-related comments and the housing fund’s lending decision should not be treated as proof of wrongdoing. The relevant financial arrangements and official decisions need to be examined on their own evidence.
Manchester City’s Financial Rules Controversy Adds to Scrutiny
The latest questions surrounding the loan have emerged against the backdrop of a separate controversy involving Manchester City’s financial reporting.
The source report refers to a finding that the club had breached financial rules over a nine-year period and had boosted its income by £900 million. The dispute has intensified public discussion about the club’s finances and the role of its wealthy ownership.
The financial rules controversy is separate from the GMCA housing fund investigation. The latter concerns public-backed loans to property companies connected to Sheikh Mansour, rather than the club’s own financial reporting.
The overlap in ownership has nevertheless brought the two issues into the same public debate. Manchester City’s economic significance to the region, Burnham’s public comments and the loan to companies linked to the club’s owner have prompted questions about transparency and public accountability.
Any conclusions about the housing loan must depend on the evidence concerning the fund’s rules and the circumstances of the individual application, rather than assumptions drawn from the football club’s separate financial dispute.
GMCA Defends the Fund and Its Lending Criteria
The Greater Manchester Combined Authority has defended the housing fund, arguing that it has supported development without imposing costs on taxpayers.
A GMCA spokesperson said the authority was supporting Leech’s overview and scrutiny committee as it conducted its inquiries. The spokesperson also said the fund had helped build 11,000 new homes and was contributing to development worth billions of pounds.
The authority said decisions to grant loans were taken publicly and that no viable scheme had been turned down. It added that funding had been provided to approximately 50 different developers.
According to the GMCA, the fund was open to all developers, with lending criteria based on parameters established by the government and developed with external financial experts to reflect due diligence standards used in the private sector.
These statements set out the authority’s defence of the scheme. The scrutiny committee’s review will provide an opportunity to examine how those principles operated in practice, including how applicants were assessed and how the criteria applied to the Manchester Life financing.
The authority’s claim that the fund operated openly will be particularly relevant to questions about the loan’s approval, terms and documentation. The extent to which the available records explain the decision will be important in assessing whether the process was sufficiently transparent.
Why the Housing Fund’s Lending Process Matters
Public-backed development funds are often intended to help unlock projects that might otherwise struggle to secure financing on suitable terms. Such schemes can support housing construction and encourage investment, but they also require clear eligibility standards and a defensible process for selecting recipients.
When public institutions lend money to private developers, transparency helps establish whether funds are being used for their intended purpose. It also allows scrutiny of whether applicants are assessed consistently and whether the financial terms adequately protect the public interest.
The questions raised over Manchester Life concern several aspects of that process: why the companies qualified, what interest rate they were charged, how their applications were assessed and whether the decision aligned with the fund’s stated objectives.
The fact that the loan was repaid is relevant to the fund’s financial outcome, but it does not independently establish whether the original approval process was sufficiently transparent or whether the lending terms were appropriate.
Conversely, the wealth of the companies’ ultimate owner does not automatically prove that they were ineligible. The decisive issue is whether the applicants met the published criteria and whether the fund’s rules were properly applied.
What Happens Next in the Investigation?
The GMCA’s overview and scrutiny committee is expected to examine the housing fund’s lending arrangements, with the £55 million Manchester Life loan among the issues under scrutiny. The authority has said it is supporting the committee’s inquiries.
The review could help clarify how loans were approved, what standards were used to assess developers and whether the process was adequately documented. Further information about the loan’s interest rate and eligibility assessment would also help explain the terms under which the financing was provided.
Separately, the requested manual review of Burnham’s meetings is intended to improve transparency around official records. The outcome could establish whether the relevant meeting information was complete and how the omission occurred, although no explanation for the disappearance of the record is established in the supplied report.
Downing Street declined to comment on the investigation, according to the report.
For now, the £55 million loan remains the focus of questions about public-backed financing, eligibility standards and the transparency of decision-making. The GMCA maintains that the fund supported housing delivery and operated under established lending criteria, while councillors want greater clarity about how individual decisions were reached.
The committee’s findings will be important in determining what the available evidence shows about the loan and the wider operation of the fund. Until those findings are available, questions about the approval process should remain distinct from allegations or assumptions of misconduct.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest World on thefoxdaily.com.

COMMENTS 0