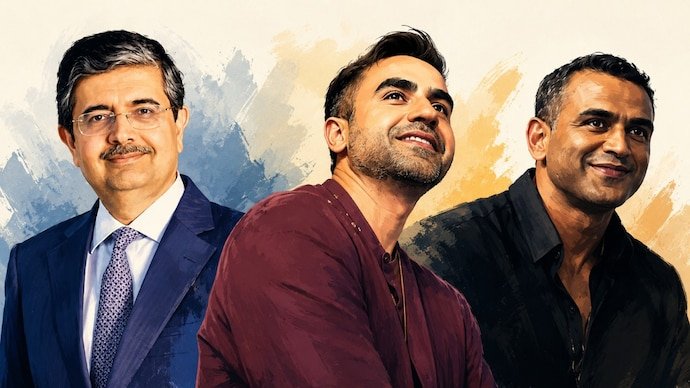
India’s financial sector has evolved far beyond traditional banks and insurance companies. Over the past several decades, fortunes have been created through gold loans, stock broking, consumer credit, Wealth Management and Technology-driven financial services.
That transformation is captured in Bloomberg’s first India Finance Rich List, which identifies 15 individuals and families whose wealth was built primarily through financial services. Together, they have amassed more than $65 billion, according to Bloomberg’s calculations based on the Bloomberg Billionaires Index.
The ranking includes some of the country’s best-known financial entrepreneurs, from veteran bankers and capital-market pioneers to younger billionaires whose fortunes emerged from the post-pandemic expansion of retail investing and digital finance.
The figures used for the ranking are based on net worth as of August 14. Bloomberg says seven of the 15 fortunes were driven by the post-pandemic boom in retail credit and equity investing, while the remaining eight belong to established players from India’s lending and capital-markets industries.
The result is more than a list of wealthy individuals. It offers a snapshot of how the Indian financial system has changed and where new wealth is being created.
India’s top 10 finance billionaires
The top 10 on Bloomberg’s list range from Uday Kotak, who built a financial institution from a small lending operation, to Zerodha founders Nithin and Nikhil Kamath, whose technology-led brokerage helped reshape retail participation in Indian markets.
Here is how the fortunes of the top 10 were built.
1. Uday Kotak $16.4 billion
Uday Kotak leads Bloomberg’s India Finance Rich List with an estimated net worth of $16.4 billion.
His financial-services journey began in 1985, when he raised an $80,000 loan from friends and family to establish a bill-discounting and lending company. What began as a relatively small financial operation eventually developed into Kotak Mahindra Bank after the Reserve Bank of India granted the group a banking licence in 2003.
The expansion did not stop with commercial banking. The Kotak group developed businesses across capital markets, investment banking and mutual funds, giving the enterprise exposure to several major parts of India’s financial system.
Kotak’s position at the top of the ranking illustrates one of the defining features of India’s financial-wealth story: some of the largest fortunes were built by creating institutions that expanded alongside the country’s broader economic and financial markets.
2. George Alexander Muthoot and family $9.9 billion
The Muthoot family has one of the oldest Business histories among the fortunes on the list.
The family’s origins date to 1887, when Muthoot Ninan Mathai established a provision store in Kerala. The business later began lending to estate workers and farmers and entered the gold-loan industry in 1939.
That business eventually developed into Muthoot Finance, founded by Mathai George Muthoot after the family business was divided among the founder’s three sons.
Gold loans became the foundation of the family’s financial-services empire. Bloomberg says Muthoot Finance’s gold-loan business has quadrupled since 2020 and that the company has also expanded beyond its traditional lending business.
The family’s interests now include mortgages, information technology, energy, real estate, education, Healthcare and hospitality.
With an estimated $9.9 billion fortune, the Muthoot family demonstrates how an old-style lending business built around physical assets has adapted to a much larger modern financial market.
3. Nithin and Nikhil Kamath $9.9 billion
Nithin and Nikhil Kamath represent a very different route to financial wealth.
The brothers began trading in their teenage years in the late 1990s and subsequently worked as sub-brokers. In 2010, they founded Zerodha, a brokerage built around technology and a low-cost model.
The company emerged as retail participation in India’s stock market expanded, particularly among a younger generation of investors who increasingly used digital platforms rather than traditional brokerage channels.
Bloomberg says Zerodha’s client base grew from about 30,000 in 2013 to more than 17.5 million.
Nithin Kamath continues to lead Zerodha, while Nikhil Kamath has expanded his activities into venture capital, asset management and other investments.
The brothers’ $9.9 billion combined fortune reflects the growing role of technology in Indian financial services. Unlike traditional banks, digital brokerages can reach millions of customers through software platforms, changing the economics and accessibility of investing.
4. Ajay Piramal $4.4 billion
Ajay Piramal took a more diversified route into financial services.
He inherited a family textile business but subsequently expanded into glass manufacturing and pharmaceuticals. A major turning point came in 2010, when the family sold its domestic drug manufacturing business to Abbott Laboratories for $3.72 billion.
The transaction provided capital for expansion into new sectors, including financial services and real estate.
Piramal Finance initially focused heavily on commercial lending to property developers. The business later changed direction following the shadow-banking crisis of 2018-19.
The acquisition of Dewan Housing Finance Corporation helped Piramal build a larger retail-lending operation, shifting its financial-services strategy toward a broader consumer base.
Bloomberg puts Piramal’s net worth at $4.4 billion and says Piramal Finance now has a loan book exceeding $11 billion.
His story highlights another path to financial wealth: using capital generated from established industries to build a presence in a rapidly expanding financial sector.
5. Motilal Oswal and Raamdeo Agrawal $3.9 billion
Motilal Oswal and Raamdeo Agrawal built their fortune from India’s expanding capital markets.
The two started as sub-brokers at the Bombay Stock Exchange after moving to Mumbai to pursue chartered accountancy. Their major opportunity emerged with the development of the National Stock Exchange in the 1990s and the rapid expansion of India’s equity markets.
Over the following decades, their business benefited from rising participation in equities and the growing number of companies accessing public markets.
Motilal Oswal Financial Services subsequently expanded beyond conventional brokerage into asset management, alternative investments, lending and private wealth.
Bloomberg says the group now manages nearly $70 billion in assets under advice.
The $3.9 billion combined fortune of Oswal and Agrawal reflects the long-term value created by the expansion of India’s capital-market ecosystem, rather than a single financial product or business line.
6. Sanjay and Alpana Dangi $3.9 billion
Sanjay and Alpana Dangi built their wealth through India’s capital markets and financial-services industry, with Sanjay Dangi developing a particular focus on small and mid-sized companies.
The Dangi family acquired listed non-banking financial company Authum Investment and Infrastructure in 2019. The business operates across public and private markets as well as lending.
A significant expansion followed the acquisition of two non-bank lenders from Anil Ambani’s Reliance Group in 2022-23. The transactions expanded Authum’s lending activities and its access to retail borrowers.
Bloomberg says Authum now manages approximately $1.4 billion in public and private investment assets and has a loan portfolio of about $430 million.
The Dangi fortune illustrates how India’s financial landscape has created opportunities not only through founding new companies but also through acquiring and restructuring existing financial businesses.
7. Sachin Bansal $3 billion
Sachin Bansal first became wealthy by helping build one of India’s most important internet companies.
Bansal and Binny Bansal met at IIT Delhi and later worked at Amazon. They founded Flipkart as an online bookstore with an initial investment of only $4,800.
The company grew into India’s largest online retailer before Walmart acquired a controlling stake in Flipkart for $16 billion in 2018.
Bansal subsequently shifted his focus to financial services and founded Navi. What began as a digital lending platform expanded into payments, lending, general insurance and asset management.
Bloomberg says Navi had more than $1.3 billion in loan assets and approximately $1 billion in mutual-fund assets during 2025-26.
Bansal’s inclusion is significant because his path shows how India’s technology entrepreneurs are increasingly moving into financial services, where digital distribution can be combined with lending and investment products.
8. Sanjay Agarwal $1.9 billion
Sanjay Agarwal built his business by serving borrowers who were historically less prominent in India’s formal financial system.
He began by lending to small transport operators, entrepreneurs and borrowers in rural and semi-urban parts of Rajasthan. The business expanded into vehicle finance and eventually developed into one of India’s major non-bank vehicle financiers.
In 2015, the company received an RBI licence to operate as a small finance bank and became AU Small Finance Bank.
The bank continued expanding its customer base and financial offerings. A decade after receiving its small finance bank licence, the RBI gave AU Small Finance Bank in-principle approval to convert into a universal bank.
Bloomberg describes AU as India’s largest small finance bank, with a market value of $8.5 billion and more than 12 million customers.
Agarwal’s $1.9 billion fortune demonstrates how serving smaller borrowers can become a major financial business when combined with formal banking infrastructure and a large customer base.
9. Rajesh Sharma $1.8 billion
Rajesh Sharma began his career in investment banking at HBL Stock Broking before starting his own debt investment banking practice in 1994.
His business later expanded into stock broking, lending and investment advisory through Money Matters Financial Services, which was subsequently renamed Capri Global Capital.
Sharma eventually shifted the business away from a primary focus on capital markets and toward retail lending.
That strategy helped Capri Global develop into a significant lending business. Bloomberg values the company’s lending operations at about $4.2 billion and says it serves more than one million customers.
Gold loans account for nearly half of its lending book, adding another connection between the modern financial sector and one of India’s oldest forms of secured borrowing.
10. Anand Rathi and family $1.7 billion
Anand Rathi rounds out Bloomberg’s top 10 with an estimated family fortune of $1.7 billion.
A chartered accountant, Rathi worked at DCM and the Aditya Birla Group before co-founding the Anand Rathi Group with Pradeep Gupta in 1994.
The company initially focused on investment banking and institutional research before branching into lending and wealth management.
Anand Rathi Wealth has since become one of India’s major wealth-management businesses. Bloomberg says it manages more than $11 billion in assets for approximately 14,000 clients.
The group’s broking arm has around 90,000 customers, with $12 billion in assets under custody and nearly $10 billion under management.
What the list says about India’s financial economy
The most striking feature of Bloomberg’s ranking is the variety of businesses behind the fortunes.
There is no single formula for becoming a financial billionaire in India. The list includes commercial banking, gold loans, retail lending, brokerage, investment banking, wealth management, asset management and fintech.
That diversity reflects the expansion of India’s financial system itself.
Older fortunes were often built by providing capital to businesses or individuals who had limited access to formal finance. Newer fortunes have increasingly come from technology platforms that make investing, borrowing and financial products easier to access at scale.
The rise of retail investors has been particularly important. Digital brokerages have lowered the barriers to participating in equity markets, while mobile-based financial services have expanded access to credit and payments.
At the same time, established financial institutions have benefited from the growth of India’s middle class, increasing formalisation of financial activity and deeper capital markets.
Why retail investing has changed the wealth landscape
The fortunes of the Kamath brothers and the expansion of established financial companies show how important retail participation has become.
Investing was once more closely associated with traditional brokers, financial advisers and a relatively smaller pool of market participants. Technology has dramatically changed that distribution model.
A brokerage can now serve millions of customers through a digital platform, while investors can access market information and execute transactions from their phones.
This has created enormous opportunities for companies operating at the intersection of finance and technology.
But increased access to markets also carries risks. Bloomberg’s broader assessment of the financial boom notes that retail investors have suffered losses from speculative trading. The growth of financial participation does not automatically mean that every participant benefits.
The other side of India’s finance boom: debt and speculation
The wealth created by India’s financial expansion comes with a more complicated backdrop.
Bloomberg points to rising household debt alongside the growth of digital lending. Easier access to credit can help households and businesses manage expenses, invest or expand, but excessive borrowing can create financial pressure when income does not keep pace with repayment obligations.
Retail market participation also brings another challenge. More people entering equities can deepen markets and broaden ownership, but speculative trading can result in significant losses for inexperienced investors.
That tension is important when interpreting the fortunes on the rich list. The expansion of financial services creates valuable businesses, but the growth of those businesses does not necessarily mean that all customers using them are becoming wealthier.
Traditional finance and fintech are converging
Another important trend visible in the ranking is that the boundaries between traditional finance and technology are becoming less distinct.
Uday Kotak’s journey represents the development of a full-scale banking and financial-services institution from a lending operation. The Kamath brothers represent a digital-first brokerage model. Sachin Bansal entered finance after building a major technology company. Other names on the list expanded from capital markets into lending, wealth management and alternative investments.
These different paths increasingly lead toward the same destination: large, diversified financial ecosystems serving millions of customers.
For entrepreneurs, that means India’s expanding financial economy offers opportunities well beyond conventional banking.
What the top 10 fortunes have in common
Despite their different backgrounds, the people on Bloomberg’s top 10 list share several characteristics.
- They built scalable financial businesses: Their companies expanded beyond individual transactions to serve large customer or investor bases.
- They benefited from structural change: The growth of India’s capital markets, formal lending and digital finance created new opportunities.
- They diversified: Many of the businesses moved beyond their original focus into lending, wealth management, investment products or other financial services.
- They adapted to new technology: Digital platforms have become increasingly important in brokerage, lending, payments and wealth management.
- They benefited from India’s expanding financial participation: More households and individuals are participating in formal credit and investment markets than in earlier decades.
A new generation of Indian financial wealth
Bloomberg’s first India Finance Rich List ultimately tells a broader story than who has the most money.
It shows how the country’s financial system has become one of the most powerful wealth-creation engines in the Indian economy.
The fortunes of Uday Kotak and the Muthoot family demonstrate the scale that traditional banking and secured lending can achieve. The businesses created by Motilal Oswal, Raamdeo Agrawal and Anand Rathi show how the expansion of capital markets and wealth management generated another route to financial wealth.
The Kamath brothers and Sachin Bansal represent a newer generation that built fortunes at the intersection of technology and finance.
Meanwhile, entrepreneurs such as Sanjay Agarwal and Rajesh Sharma demonstrate how serving underserved borrowers can become a large-scale financial enterprise.
Together, the 15 individuals and families on Bloomberg’s list have accumulated more than $65 billion through financial services. Their combined wealth is a measure of how dramatically India’s financial landscape has changed.
But the same transformation also raises questions about household debt, speculative investing and the distribution of the gains created by expanding financial markets.
The defining story of India’s financial sector may therefore be bigger than the billionaires themselves. It is the transformation of finance from a relatively specialised industry into a mass-market ecosystem in which millions of Indians now borrow, invest, trade, insure themselves and manage wealth through institutions and digital platforms.
That transformation has already created a new class of financial billionaires. The next phase will depend on whether the expansion of credit, investment and fintech can continue while keeping the risks to households and retail investors under control.
For breaking news and live news updates, like us on Facebook or follow us on Twitter and Instagram. Read more on Latest Business on thefoxdaily.com.


COMMENTS 0